The Example of Europe: Austerity Programs Are Indeed Contractionary


Europe GDP Growth, 2007Q4 to 2012Q3 - 1A.  Introduction

As the US comes closer to the so-called “fiscal cliff” (actually, more of a “fiscal slope”, as many have noted, as the impact will build over time rather than hit abruptly), it is worth reviewing the experience of Europe with the type of austerity programs that many are now pushing for the US.  The fiscal cliff we are now facing in the US is a manufactured crisis, created at the insistence of Republicans in August 2011 when they finally approved a higher statutory federal government debt limit.  It is a set of measures that will automatically enter into force on January 1, 2013, unless an agreement had been reached before then on actions to drastically cut back the federal deficit.

Unfortunately the debate underway in Washington is not on whether it is wise now (with the still weak economy) to enter into an austerity program of some sort.  Rather, it is solely on how severe that austerity program should be.  Any agreement will lead to a reduction in government spending and to increases in taxes, relative to what they would have been without the measures being negotiated.

The Republican argument is that adoption of such an austerity program is necessary for the US to be able to continue to grow.  Similar arguments were made in Europe.  Much of the continent has now adopted austerity programs, either willingly (such as in the UK) or due to pressure from other EU members and in particular pressure from the German government (such as in the cases of Greece, Spain, and Italy).  Our aim here is not to review in each case the reasons why the different countries may have chosen to adopt these austerity programs, which as noted was sometimes by policy choice and sometimes as a result of outside pressure.  Rather, the aim is to see what the impacts on growth have been since the programs were adopted (for whatever reason).

It is worth recalling what was said when these programs were first being pushed by prominent European authorities.  While critics forecast that such austerity programs would kill the incipient recoveries from the 2008/09 collapse (that started in the US and then spread globally), the European authorities in favor of these austerity programs argued that there was no need to worry.  They argued that such austerity programs would in fact be expansionary rather than contractionary.

The most prominent example is perhaps in the arguments made by the then President of the European Central Bank, Jean-Claude Trichet.  For example, in a June 2010 interview with La Repubblica (the largest circulation newspaper in Italy), Trichet said:

Trichet:  … As regards the economy, the idea that austerity measures could trigger stagnation is incorrect.

La Republicca:  Incorrect?

Trichet:  Yes. In fact, in these circumstances, everything that helps to increase the confidence of households, firms and investors in the sustainability of public finances is good for the consolidation of growth and job creation.  I firmly believe that in the current circumstances confidence-inspiring policies will foster and not hamper economic recovery, because confidence is the key factor today.

Trichet did not mis-speak.  He made a similar statement a month later in an interview with the newspaper Libération of France:

Libération:  Do the austerity plans announced amid monumental disarray by the Member States pose the risk of killing off the first green shoots of growth?

Trichet:  It is an error to think that fiscal austerity is a threat to growth and job creation. … Economies embarking on austerity policies that lend credibility to their fiscal policy strengthen confidence, growth and job creation.

But that has not been the case.

B.  The Larger European Economies, and Europe as a Whole

The figure above shows the paths of real GDP for the US, for several of the larger European economies, and for the Eurozone area as a whole, relative to the fourth quarter of 2007 (the peak before the start of the downturn in the US, and just before the start of the downturn in Europe, which for most was in the first quarter of 2008).  Some points to note:

  • The early path of the downturns were similar between the US and Europe, with a collapse in 2008 and into the first half of 2009, and then a start of a recovery with the stimulus packages adopted in the US as well as in much of Europe in 2009.
  • But then growth faltered in several of the European economies:  in mid-2010 in the UK, in early 2011 in the Netherlands, and more broadly in the 17 countries making up the Eurozone (who use the euro as their currency) in mid-2011.
  • The turnaround in the UK is particularly interesting for the US, as the UK (like the US) has its own currency and central bank, and can follow its own fiscal policy.  The abrupt end to the UK recovery in mid-2010 followed directly from new measures enacted by the then newly elected Conservative-led government (elected in May 2010, with initial emergency measures implemented from June, and a broader program implemented from October).  This was discussed in a previous blog post on this site.  Many of the Conservative government measures are similar to those being pushed by the Republicans in the US, with a sharp-cut back in government expenditures and in particular cuts in expenditures that provide support to the poor, accompanied by cuts in corporate taxes and more recently cuts in the top tax rates on the rich.
  • But while the Conservative Party argument for the UK austerity program was that this would lead to growth and to a reduction in government debt ratios, it is widely acknowledged now that the downturn that resulted from the austerity measures instead means that the program failed in terms of its originally stated objectives.  The austerity measures did not lead to an acceleration of growth, but rather to stagnation.  (And note that while there was an uptick in GDP by one percentage point in the third quarter of 2012, this has been attributed to the stimulus in spending resulting from the staging of the 2012 Olympics in London.  Indeed, the Bank of England in November, in its official forecast for the economy, noted GDP could fall back again in the fourth quarter of 2012 and downgraded its expected growth in 2013 to only 1%.)
  • Germany appears to be an exception, with a path followed for GDP above that of the US, although with a narrowing since mid-2011.  But while Germany has argued most strenuously and forcefully on the need for other European countries to follow austerity policies, its own internal government spending policies have been expansionary.  This is surprising given its rhetoric, and will be reviewed in a separate post on this blog which will be prepared after this one.  And it is also important to note that even with this performance, German GDP was only 2% higher in the third quarter of 2012 than it was in the first quarter of 2008, for a compound growth rate of only 0.4% per annum over four and a half years.
  • Each country has its own story, and it is not possible to review them all here.  But it is clear that for the Eurozone area as a whole, as well as for the UK but with the exception of Germany (which kept to expansionary government spending), the austerity programs launched in 2010 and 2011 have led to stagnation at best and falling output for most.

C.  Southern Europe and Ireland

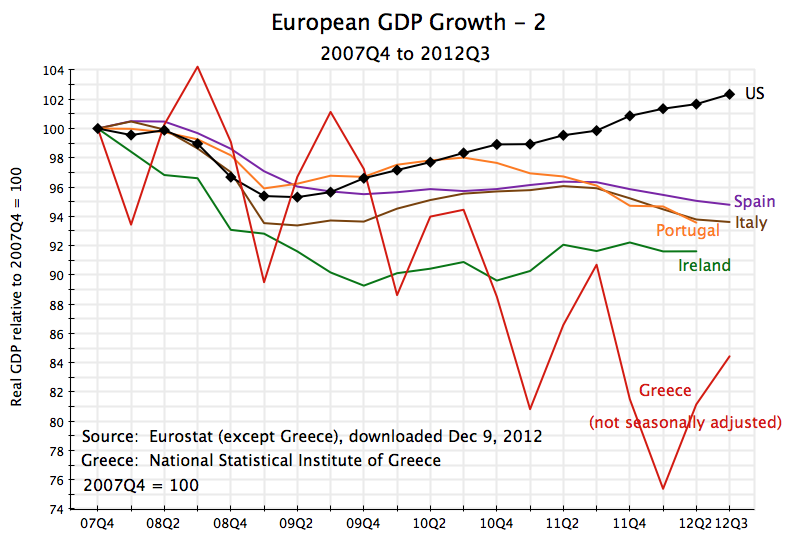
There are two other groups of European economies where the response to austerity programs is of interest.  The first is the group of mostly Southern European economies were strict austerity policies were imposed as conditions of support programs from the IMF and the rest of Europe.  Funds were lent in these programs to those governments to enable them to continue to repay their creditors (who were in large part banks from Northern Europe).  This is the group affectionately known as the PIIGS, for Portugal, Italy, Ireland, Greece, and Spain.

The austerity measures led to collapses in output.  (A seasonally adjusted series is not available for Greece, but its path is clear.):
Europe GDP Growth, 2007Q4 to 2012Q3 - 2

D.  The Baltics

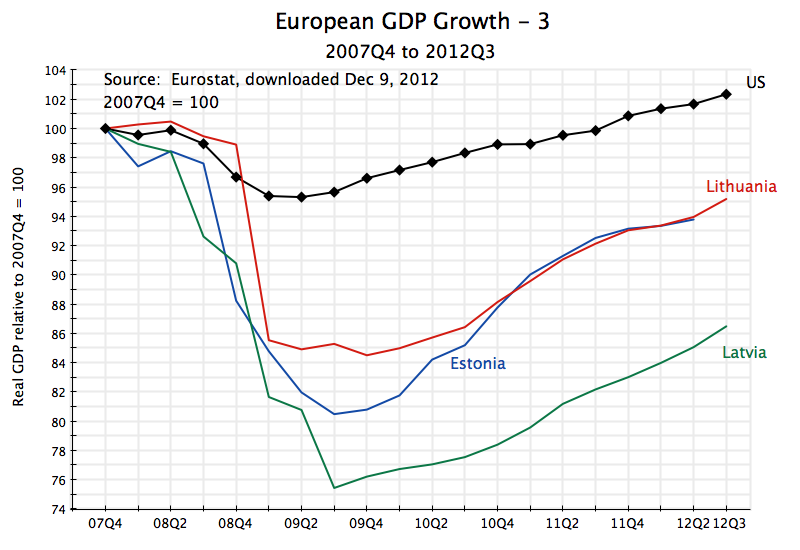
The other group of interest is the three small Baltic countries:  Estonia, Latvia, and Lithuania.  They were each severely impacted by the 2008/09 financial collapse, and each responded with stern austerity programs.  With strong growth over the last three years in each of them, these countries are sometimes held as examples of how austerity programs can lead to growth.  But this ignores the depth of the downturns that resulted from their austerity measures.  From the fourth quarter of 2007 to their troughs in 2009, GDP fell by 15% in Lithuania, by almost 20% in Estonia, and by an astounding 25% in Latvia.  There has been growth since then, but their current output remains far below where it was in 2007:
Europe GDP Growth, 2007Q4 to 2012Q3 - 3

Some have argued that the countries had no choice.  Estonia is a member of the Eurozone, and could not as a result depreciate an independent currency without leaving the Eurozone.  As in the other Eurozone members, monetary policy for Estonia is determined centrally by the European Central Bank, and fiscal policy is constrained by the extent to which the country will be able to borrow in the financial markets to finance any deficits.  But as noted above, the aim here is not to ascertain whether or not the countries had any policy choice on whether to follow some austerity program (or how severe that austerity program should have been), but rather what the impacts on growth have been of the austerity programs followed.  And the impacts have been negative.

Lithuania and Latvia had more scope in terms of policies they could have followed, since their currencies, while tied (by government decision) to some rate vis-a-vis the euro, are still independent currencies.  The governments could have chosen to devalue these currencies, which would have spurred their exports.  However, they decided not to, and instead decided to follow programs of severe fiscal austerity.  Output collapsed.

E.  Unemployment

The fall in output resulting from the austerity measures is bad enough by itself.  The loss in output is a loss in real resources, which could have been used for productive purposes.  But the tragedy is in fact much worse, as the pain from falling output is not spread evenly over the population, but rather is concentrated among a few.  In particular, those who lose their jobs and become unemployed see a drop not only in their current living standards, but for many also a permanent loss in their real standard of living, and for all a psychological burden as well.

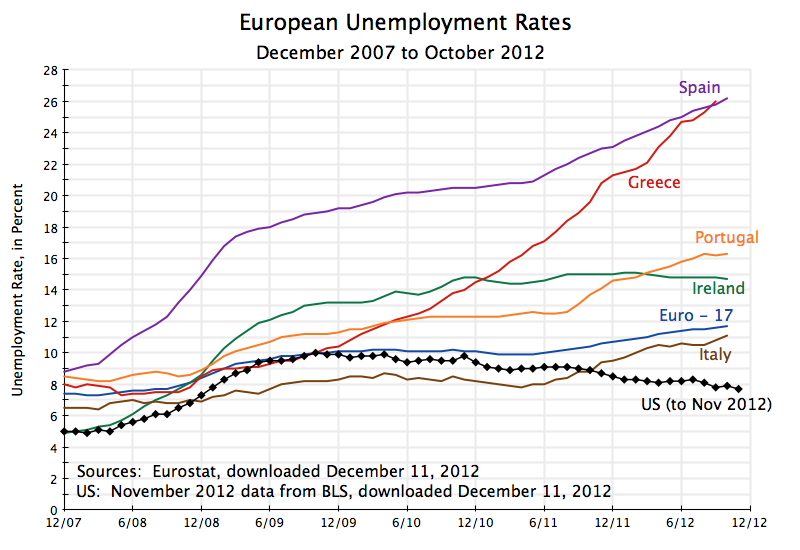
It is therefore tragic to see how unemployment rates have risen, to almost 12% for the Eurozone as a whole, and to 26% in Spain and Greece following their particularly severe austerity programs:
European Unemployment Rates, Dec 2007 to Oct 2012F.  Conclusion

The austerity programs implemented in Europe killed the recoveries which were underway in 2009/2010, and led to double-dip recessions.  Unemployment had started to decline in the Eurozone area as a whole, but then rose following the new austerity programs, reaching a rate of almost 12% recently.  The US economy has so far fared better, with positive growth and a decline in the unemployment rate from a peak of 10.0% to a rate of 7.7% in November 2012.

But there is now the strong danger that if the negotiations under the threat of the fiscal cliff leads to new austerity measures, with expenditure cuts and tax increases starting in 2013 in order to reduce rapidly the federal fiscal deficit, that the consequences in the US will be similar to that which has been seen in Europe.
The Impact of the Fiscal Austerity Program in the UK: A Comparison to the US and to the Great Depression

UK and US real GDP, comparison of growth since 2008 downturn by quarter

Both the US and the UK released last week (on July 25 by the UK Office for National Statistics, and on July 27 by the US Bureau of Economic Analysis) their initial estimates for GDP growth in the second quarter of 2012.  Both were disappointing:  The estimated US growth was a positive 1.5% at an annual rate, down from growth of 2.0% in the first quarter and a now estimated 4.1% in the last quarter of 2011.  But the UK figure was abysmal, showing growth at a negative 2.8% at an annual rate.   (The headline figure commonly quoted in the UK was a negative 0.7%, but the tradition in the UK is to express this on a quarter on quarter basis.  It comes to four times this, or a negative 2.8%, when annualized.  In the US, the figures are traditionally expressed on an annualized basis.)

The US growth figures were discussed in a post on this blog yesterday.  The focus in this post will be on the UK numbers, and in particular the path followed by the UK in the downturn that was sparked by the US financial collapse in 2008, in the last year of the Bush administration.  Comparison to the path followed in the US economy is especially interesting as both countries have followed similar aggressive monetary policies (with independent Central Banks pushing short term interest rates essentially to zero, plus the use of quantitative easing to provide ample liquidity to the economy), both have independent floating currencies (unlike the economies tied together with a common currency in the Eurozone), and both moved aggressively at the onset of the crisis to keep large banks from failing through official loans which were later repaid.

But there is one important difference, and this sets up a natural experiment which is rarely possible in economics.  Following elections in May 2010, a Conservative Party led government in the UK (in coalition with the Liberal Democrats as a minority partner) moved to an aggressive austerity focused fiscal policy, with major cut-backs in government spending.  With other policy factors being similar, one can see what the impact of such a fiscal austerity program will be, not only in comparison to what was happening immediately before in the UK, but also in comparison to a US economy which was otherwise following similar policies.

In the UK parliamentary system, the fiscal austerity program was passed via an Emergency Budget in late June 2010.  Such a dramatic change in policy is possible in a parliamentary system as the ruling government will always enjoy a majority in Parliament (perhaps in coalition with other parties), so Parliament will not hold up the program of the government as it can in the US congressional system.  Indeed, in the US now a minority of 40% of Senators will veto any measure they wish due to abuse of Senate rules (rules which are not reflected in any way in the US Constitution, which does not call for a super-majority of 60% to pass such measures).  These Senate rules have been in place for a century and a half, but until recently were used only in rare exceptional circumstances.  This use of these Senate rules have blocked Obama from implementing many, although not all, of the programs he has sought.

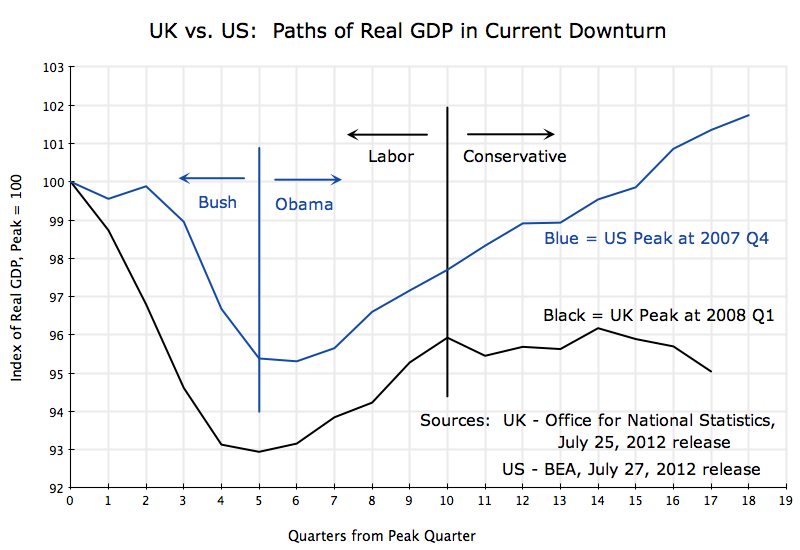
The graph above shows the path of GDP growth in the UK and in the US by calendar quarters from the pre-recession peaks in GDP (set equal to 100).  This peak was in the fourth quarter of 2007 for the US, and in the first quarter of 2008 for the UK.  The downturn started in the US.  The UK economy then dropped further and faster, as the financial sector was at the center of the collapse and the financial sector (with London as the most important international center) is a larger share of the UK economy than it is in the larger and more diversified US economy.

The US economy began to recover soon after Obama was elected and was able to pass and start to implement the fiscal stimulus package (along with aggressive measures by the US Fed and other actions).  The UK economy also began to turn around at about the same time.  The Labor Party Government under Gordon Brown was following similar measures as were being implemented under Obama in the US.  Both economies then began to grow, at roughly similar rates.

But then the UK held the May 2010 elections, which the Labor Party lost.  The Conservatives (in coalition with the Liberal Democrats) took control of the Parliament and of the government.  David Cameron became Prime Minister.  He immediately announced that an aggressive austerity budget would be drawn up and implemented, and it was, starting in the summer of 2010.  This was the tenth quarter from the pre-recession peak for the UK of the first quarter of 2008.

The impact has been clear and stark, as shown in the diagram above.  The economy reached a peak in its recovery in the tenth quarter, but then the recovery stopped.  The UK economy has now fallen for three straight quarters, going into a double-dip recession.  The US economy, in contrast, has continued to grow.

The UK fiscal austerity package has clearly been a failure.  The economy stopped growing when that program began.  The Conservative Party argument in favor of their austerity package was that it would induce “confidence” among investors, and that their increased investment would off-set the cut-backs in government.  This has not happened, despite ample liquidity in the markets and interest rates that are at historical lows.  The alternative view, which I share, is that investors will invest to expand capacity only if they see a market for what they would then be able to produce, and only if they do not have an existing excess of capacity to produce it without further investment.  Fiscal austerity will reduce that market, not expand it.  To argue that contractionary fiscal policies will be expansionary is just wrong and is inconsistent with the facts.  Contractionary policies are contractionary.

The austerity program has also failed in its announced aim of rapidly bringing down the fiscal deficit at a faster pace than was forecast before.  With the economy flattening out and then declining, tax revenues have fallen below what was anticipated.  After close to a year and a half of experience under their fiscal austerity program, the Conservative Government had to admit last November that their plan to bring down the budget deficit to zero would require two more years than they had originally said.  Since then the economy has deteriorated even further, with GDP falling for three calendar quarters now rather than merely remaining flat.  The date by which their avowed aim of budget balance will be achieved will have receded even further.  The austerity program has failed even by its own objective of seeking to bring down the deficit rapidly.

These results are important for the US.  Mitt Romney and the Republican Party in the US have argued for a fiscal austerity program similar in nature to what the Conservative Party is implementing in the UK.  But the UK results have been abysmal.  Even business leaders gathered in London for meetings surrounding the Olympics now underway, have called for David Cameron and his Conservative Party to reconsider his fiscal program, according to a report in today’s Financial Times.  The Cameron Government has argued that the 2.8% decline in GDP in the second quarter was in part a consequence of special factors (the celebration of the Queen’s Diamond Jubilee and unusually wet weather; but celebrations normally spark growth, and one would have thought that the UK knows how to cope with wet weather).  It also may well be the case that the Olympic Games now underway in London will lead to growth in the third quarter due to high tourist and other expenditures linked to the games.  But even discounting such special factors, one cannot hide the abrupt flattening out and then decline in the economy since the fiscal austerity program was initiated.  The contrast to the US path is stark.

Finally, it is of interest to compare the 2008 downturn and aborted recovery in the UK to the path the UK economy followed in the 1930s, during the world-wide Great Depression.  As seen in the graph below, the UK path is now well below where it was at the same point during the recovery from the 1930 downturn.  Economic performance in the UK is worse now than it was during the Great Depression.  The record of the austerity program in the UK, a program that the Repubicans want to duplicate in the US, has been truly terrible.

UK real GDP, comparison of growth since 2008 and during Great Depression, by quarter

GDP Growth in the Second Quarter of 2012: Even Slower

BEA release of 7/27/12. Seasonally adjusted annualized rates       Percent Growth Contribution to GDP      Growth
2011Q4 2012Q1 2012Q2 2011Q4 2012Q1 2012Q2
Total GDP 4.1 2.0 1.5 4.1 2.0 1.5
A.  Personal Consumption Expenditure 2.0 2.4 1.5 1.45 1.72 1.05
B.  Gross Private Fixed Investment 10.0 9.8 6.1 1.19 1.18 0.76
 1.  Non-Residential Fixed Investment 9.5 7.5 5.3 0.93 0.74 0.54
 2.  Residential Fixed Investment 12.1 20.5 9.7 0.26 0.43 0.22
C.  Change in Private Inventories nm* nm* nm* 2.53 -0.39 0.32
D.  Net Exports nm* nm* nm* -0.64 0.06 -0.31
E.  Government -2.2 -3.0 -1.4 -0.43 -0.60 -0.28
Memo:  Final Sales 1.5 2.4 1.2 1.52 2.38 1.23
    nm* = not meaningful
$ Value of Change in Private Inventories (2005 prices) $70.5b $56.9b $66.3b

The initial estimates for US GDP growth in the second quarter of 2012 were released by the BEA of the US Department of Commerce on July 27, and indicated that a slowly growing economy was growing even more slowly than before.  GDP growth of 4.1% in the last quarter of 2011 (based on revised figures issued on July 27 as well), had slowed to just 2.0% growth in the first quarter of 2012, and then to an estimated 1.5% growth in the second quarter.  The figures are subject to revision, but it is unlikely that the basic story will change significantly.

This slowdown in growth in 2012 had in fact been predicted on this blog in a posting on January 27, when the initial estimates for growth in the last quarter of 2011 were issued.  While growth at the end of 2011 was relatively robust, it was noted there that much of this had occurred due to an increase in private inventory accumulation.  As has been explained in an Econ 101 posting on this blog, it is the change in the change in private inventories which contributes to GDP growth, and that change in the change in private inventories had been large in the fourth quarter of 2011.  Using the figures from the current BEA estimates, the change in private inventories was essentially zero in the third quarter of 2011 (a fall of just $4.3 billion at 2005 prices), but then rose by $70.5 billion in the fourth quarter.  This increase by a net $74.8 billion added 2.53% points to GDP in the fourth quarter, accounting for over 60% of the now estimated 4.1% growth in that period.  Without this (that is, if inventory accumulation had been at the same pace as before), GDP growth would not have been 4.1% but only 1.5% in that period (the growth of final sales).  Since over time the pace of inventory accumulation is relatively steady on average, even though there can be significant swings in any given quarter, it was predicted that GDP growth could well slow in 2012.

That is what happened.  GDP growth slowed to a pace of just 2.0% in the first quarter of 2012 and to an initial estimate of just 1.5% in the second quarter.  There are many other changes going on of course, but the swings in the change in change in inventory accumulation can have a significant impact in any given quarter.  In the first quarter of 2012, the pace of inventory accumulation slowed to $56.9 billion.  This was still positive (inventories grew), but was a slower pace than the $70.5 billion accumulation in the fourth quarter of 2011.  That is, inventories were still growing at a fairly high rate in the first quarter of 2012, but by not as rapid a rate as they had in the last quarter of 2011, so this subtracted from GDP growth.  It subtracted 0.39% points from what GDP growth otherwise would have been (see the figure on Contribution to GDP Growth in the table above).  The initial estimate for the second quarter of 2012 is that private inventories grew by $66.3 billion, which was an increase from the $56.9 billion pace of the first quarter, and so contributed 0.32% points to GDP growth.  But will this continue?

Inventories are held only because of an expectation that the goods will be sold, and businesses do not wish to hold too much in inventories.  Inventory accumulation must be financed, and goods can deteriorate in value if not soon sold (this is especially the case for anything where technology changes rapidly, such as the latest electronic gadgets).  Rapid accumulation of inventories is indeed normally a sign that goods are not being sold as rapidly as the producers of these goods had expected, so a rapid rise in inventories is often a disturbing sign.  Production is still going on, and hence GDP is being generated, but a rapid accumulation of inventories will often then lead producers to cut back on production, and GDP growth will slow or even become negative.

This could happen now.  Private inventories have grown by a total of almost $200 billion in the last three quarters together (at constant prices of 2005), and have not grown by so much over a three quarter period since 2006.  Should producers decide to limit production so that total inventories stay where they are now in the next quarter (and succeed in doing this, as there is unpredictability in what sales will be), inventory accumulation will drop back to zero.  This is not unusual:  As noted above, inventory accumulation was essentially zero (in fact slightly negative) in the third quarter of 2011.  But if this happens, GDP growth would fall by 2.0% points (given the current pace of inventory accumulation) below what it would otherwise be, and could easily push GDP growth into negative territory.

Because of these swings in inventory accumulation from quarter to quarter, it is wise to look at what is happening to final sales.  This will often provide a better picture of what is happening in the basic underpinnings to short run growth.  As seen in the table above, final sales have grown at rates of 1.5%, 2.4%, and 1.2% in the most recent three quarters, respectively.  On average, GDP growth will tend to match these rates over time.  They show that the economy has been fundamentally weak over this period.

And the concerns are not just with what may happen to inventories.  Aside from inventory accumulation, the other elements making up GDP growth all show a weakening in the second quarter of 2012 compared to what their growth had been in the first quarter.  Private consumption expenditure only rose by 1.5% (at annualized rates) in the second quarter, compared to growth at a rate of 2.4% in the first quarter.  Private fixed investment only grew at a 6.1% rate, vs. a 9.8% rate in the first quarter.  Of this, non-residential fixed investment grew at a 5.3% rate vs 7.5% before, and residential fixed investment (a bright spot in the first quarter) slowed to a 9.7% rate of growth vs. 20.5% before.  Net exports (the net between exports and imports) subtracted from growth, and once again, government expenditure contracted and acted as a drag on growth.  As has been discussed before in this blog, if government expenditure had been allowed to grow during the Obama term by as much as it had during the same period under Reagan, the economy would likely now be at full employment.

There is therefore little to be encouraged by in these initial estimates for growth in the second quarter of 2012.  With Europe already in a double-dip recession, as they have foolishly pushed fiscal austerity policies despite their high unemployment, there is a good chance that US growth will slow to below 1%, and quite possibly even to something negative, in the second half of 2012.  Regardless of who should be blamed for this, it is likely that Obama will be the one blamed.