Taxes as a Share of Income Are the Lowest in Decades, While Income Distribution is Close to the Worst

US Federal Government Revenues as Share of GDP, 1960-2011, Federal Taxes, Federal Receipts

An excellent report from the Congressional Budget Office was issued yesterday, and has received a fair amount of publicity for noting that taxes in the US as a share of income are the lowest in at least 30 years (their analysis went back to 1979).  See, for example, this article in today’s Washington Post.  The CBO findings are correct, and carefully done, but readers of this blog may recall a posting from April 22, which also noted that taxes as a share of income are the lowest in over a half century (and indeed the lowest since 1950).  The graph above is copied from that post.

The CBO report looks at taxes as a share of household incomes, relying on data from the IRS and the Census Bureau, and hence had data only through 2009.  The data I used comes from the National Income and Product Accounts (GDP Accounts) of the Bureau of Economic Analysis in the Department of Commerce, which had data through 2011 (and now up to the first quarter of 2012).  But both come to the same basic conclusion:  That taxes as a share of income are the lowest in decades.  Republicans have asserted that high and rising taxes are the reason the economy has not recovered from the 2008 downturn, and that therefore further tax cuts are needed.  But there is no factual support for this.

Taxes are low in part precisely because of the 2008 collapse, with conditions only turning around in mid-2009, soon after Obama took office.  Incomes fell, and therefore taxes due fell as well and indeed fell by more.  But the low taxes are not simply a result of the downturn.  The economic downturn in 1982-83 under Reagan was also sharp, and the unemployment rate then hit a peak of 10.8%, or much more than the 10.0% peak reached in the current downturn.  But taxes during this Reagan period as a share of income did not then fall to as low a share as they have now.  The reason is the Bush tax cuts, which had already put taxes on a falling trend, plus an additional $1.5 trillion in tax cuts signed by Obama since he took office.  Tax cuts are one of the few areas where Obama can get support from a Republican congress for passage.  See the April 22 post for details on these tax cuts under Obama.

With the data it had access to, the CBO report could go into other areas as well, including distributional issues.  It merits a close look.  Figure 6 on page 15 is particularly interesting.  It shows that real after tax income growth for the bottom 80% of the population over the last 30 years (basically since Reagan), has been modest at best, while it has been spectacular for the top 1%.  Based on data published along with the report (in the Supplementary Tables), one can calculate that income growth for the bottom 80% of the population has averaged just 1.1% a year, and was fairly similar for each of the quintiles (i.e. for the 0 to 20%, 21 to 40%, 41 to 60%, and 61 to 80% quintiles), with a range of only between 0.9% and 1.2% for the annual average growth rates.  After 30 years, real incomes grew by a total of only 38% for the bottom 80% of the US population.

In contrast, real income was 155% higher in 2009 than it was in 1979 for the top 1%.  And the 2009 income was relatively low due to the 2008 economic collapse (and we know from other sources that the income of the very rich then bounced back in 2010 and 2011).  In 2007, real after tax incomes of the top 1% was 304% above where it was in 1979.  For the bottom 80%, changing to a 2007 base makes little difference:  it was only 38.6% higher.  It is also interesting to note that it is really only the top 1% that has gained so spectacularly in this post-Reagan period.  Total real after tax income growth between 1979 and 2009 was 50% for the 81 to 90th percentile, was 61% for the 91 to 95th percentile, and was 70% for the 96 to 99th percentile.  The spectacular growth is only seen in the top 1%.

The results are similar to what was shown in a graph I had in a January 29, 2012, post on this blog, on the impact of Reagan, reproduced here and which uses data from Thomas Piketty and Emmanuel Saez:
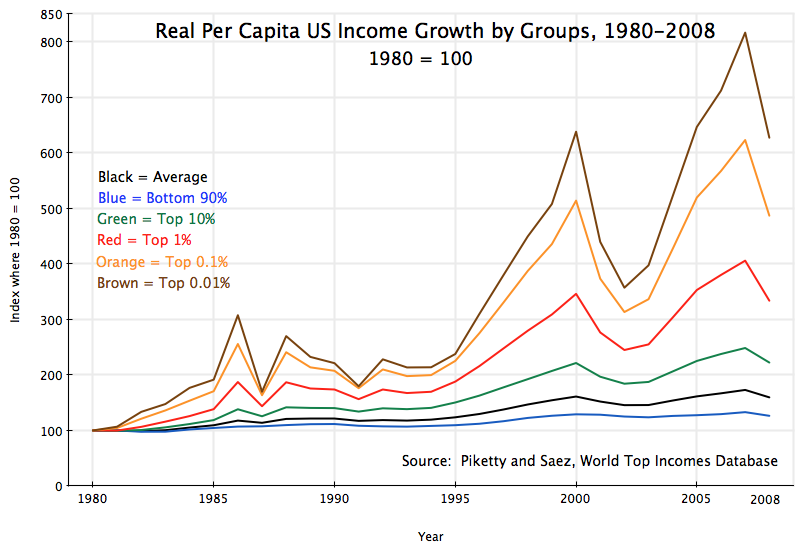
impact of Reagan on growth of real incomes, bottom 90%, top 10%, top 1%, top 0.1%, top 0.01%, 1980-2008

The pattern is similar.  There has been spectacular income growth since Reagan for the top 1%, and even more so for the top 0.1% or top 0.01%, but not for everyone else.
The Impact of Reagan: Good for the Rich, Bad for Most

No belief is more firmly held in Republican dogma than that the Reagan “Revolution” turned the US economy around from perpetual stagnation to strong growth, with consequent benefits for all.  It is now 30 years since Reagan took office and started his program of tax cuts, financial deregulation, and other measures, and we therefore now have 30 years of data to see what the impact has been.  We can compare this to how the US economy performed in the 30 years before Reagan, 1950 to 1980, to see what the differences have been.

We will do this with a series of graphs, starting with:

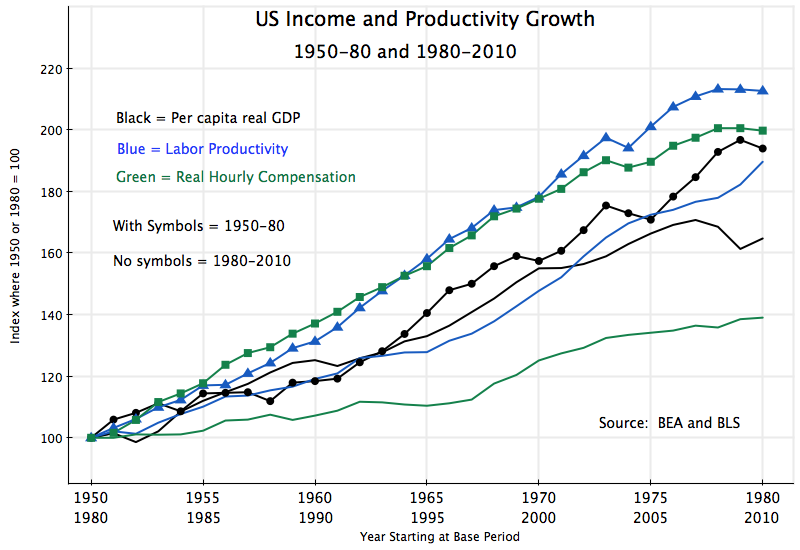
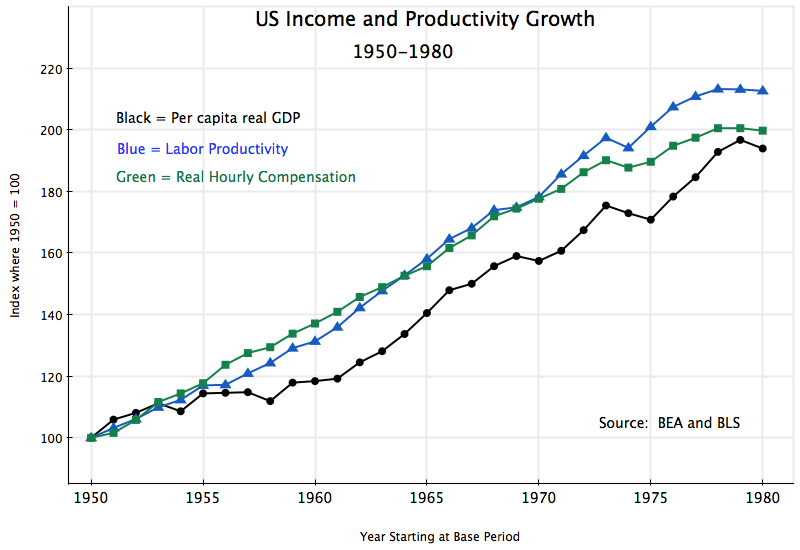
This shows the path of per capita real GDP, real labor productivity, and real hourly compensation (everything will be in real terms in this note).  Per capita GDP grew by 94% over this 30 year period, or an average of 2.2% a year, while labor productivity grew by a bit more, by a total of 113% or 2.5% a year.  Real hourly compensation grew similarly, by 100%, for a 2.3% annual rate.  In “normal” times one would expect these three measures of productivity and real incomes to grow at similar rates and to track each other, and this is basically what one observes in the pre-Reagan period.

If the Reagan measures helped spur growth, then these growth rates should have shot upwards in the next 30 years.  But one finds:

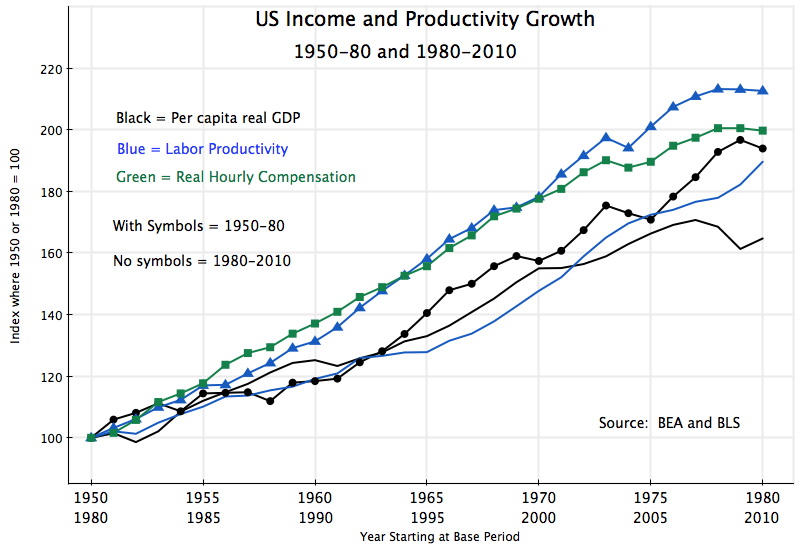
Per capita real GDP and labor productivity still grew following Reagan, but at a slower rate than before.  Per capita GDP grew only by 65% in the thirty years following Reagan (1.7% a year), vs. 94% (i.e. 45% higher) in the thirty years before.  Much of this difference is due to the weak economy at the very end of the period, due to the 2008 collapse at the end of the Bush administration and only weak recovery after, and it could be argued that one should allow for this.  Growth in the 25 years to 2005 was almost as high as the growth in the 25 years to 1975.  But then growth was strong during the Carter years (despite the widespread and oft-repeated incorrect assertion that the economy was stagnant then), while it collapsed at the end of the Bush Administration.

Growth in the economy ultimately comes from growth in labor productivity, and here the record post-Reagan is consistently weaker relative to before.  Labor productivity over 1980 to 2010 consistently tracks below where it was over 1950 to 1980, and grew by a total of 90% (2.2% a year) vs. 113% (2.5%) before Reagan.

But the really startling difference is in real hourly labor compensation:

Instead of tracking closely to the growth in labor productivity, as one would normally expect, real hourly compensation was well below.  For all workers, average real hourly compensation grew only by 39% (1.1% a year) over the thirty years post-Reagan, vs. 100% in the thirty years before.  There clearly was a change, post-Reagan, but if you were a worker, it was sharply for the worse.

The figures so far have been about overall averages:  for per capita GDP, productivity per worker, and hourly compensation per worker.  But it is also of interest to see how the average gains have been distributed across income groups.

First, for 1950 to 1980:

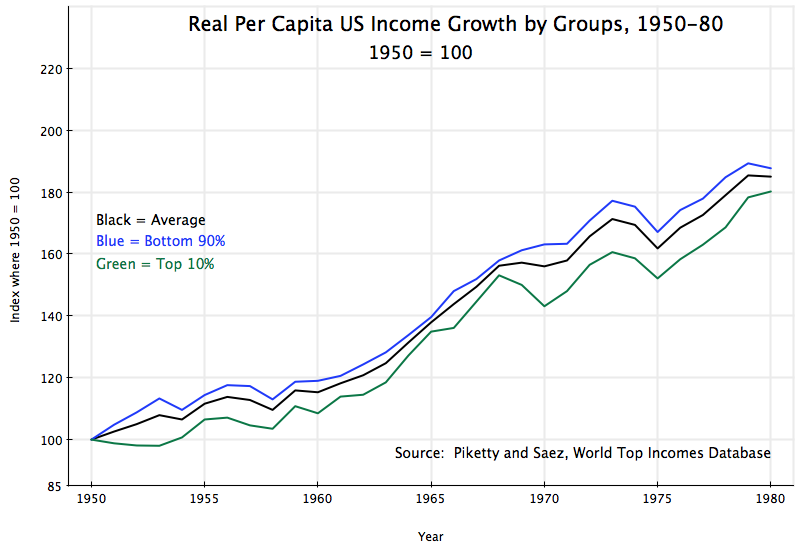
This data comes from Piketty and Saez, and is based on incomes as reported in US income tax returns (deflated to real terms using the GDP deflator).  Taxable income (including income from capital gains) is a different concept from income as defined in the GDP accounts, but the two concepts track each other fairly well over time, so comparisons in terms of growth relative to a base period will be similar.

For 1950 to 1980, one sees that average real incomes, the real incomes of the bottom 90%, and the real incomes of the top 10%, all track each other within a relatively narrow band.  Overall growth (of taxable income) was 85% (2.1% a year), with slightly more (88%, still 2.1% a year) for the bottom 90%, and a bit less (80%, or 2.0% a year) for the top 10%.  Pre-Reagan, all income groups shared similarly in income growth.  A rising tide lifted all boats.  And with incomes of the bottom 90% growing a bit faster than that of the top 10%, income equality improved some.

But things changed post-Reagan:

First of all, note that the scale here is very different than that in the previous graphs.  Note also that the data goes only up to 2008, the most recent year for which such US income tax return data has been released in a form that Piketty and Saez could analyze.  Note also that with the economic collapse in 2008, some comparisons can better be made using 2007 instead of to a trough in the business cycle.

For the full period of 1980 to 2008, average real taxable income for everyone grew by 60% (1.7% a year).  This is a somewhat slower pace than that for the thirty years before Reagan (where average real taxable income grew by 2.1% a year), consistent with and similar to the slower pace noted above for per capita real GDP.  But real incomes of the bottom 90% grew only by a total of 26% over 1980 to 2008, or 1.1% a year.  In contrast, the top 10% saw their incomes grow by 122% in the post-Reagan period, or 2.9% a year.  Distribution became more unequal, with incomes of the top 10% growing substantially faster than the incomes of the bottom 90%.

But what is startling is the growth in the shares of income going to the increasingly rich.  The top 10% enjoyed income growth over 1980 to 2008 of 122% (2.9% a year), vs. just 26% for the bottom 90%, as noted above.  But the top 1% enjoyed income growth of 234% (4.4% a year) over this period, while the top 0.1% saw their real incomes grow by 387% (5.8% a year), and the top 0.01% saw their incomes grow by 527% (6.8% a year).  The super-rich became far far richer.

Furthermore, the last year of the Bush Administration, 2008, was a year of economic collapse, with the stock market also crashing.  There were few capital gains to report as part of taxable income.  If one takes 2007 rather than 2008 as a more reasonable point of comparison, real income growth over the 27 years post-Reagan was only 33% for the bottom 90%, but 149% for the top 10%, 306% for the top 1%, 523% for the top 0.1%, and 716% for the top 0.01%.  Distribution became sharply worse.

To summarize:

1)  Overall growth in per capita GDP and in labor productivity was not higher post-Reagan, but rather was lower.  Per capita GDP, relative to the starting point, grew by 45% more in the 30 years before Reagan than in the 30 years after Reagan.

2)  Before Reagan, the paths of per capita GDP, labor productivity, and hourly compensation, tracked each other fairly closely.  After Reagan, hourly compensation rose at a far slower rate than labor productivity or per capita GDP.  Wage earners did far worse relative to others post-Reagan.

3)  Before Reagan, the incomes of the bottom 90% and the top 10% grew at fairly similar rates.  Indeed, income growth of the bottom 90% was a bit higher than that of the top 10%, indicating some move in the direction of greater equality of incomes.  But this was shattered post-Reagan, with the bottom 90% seeing income growth of just 26% over the 28 years from 1980 to 2008, while the top 10% enjoyed income growth of 122%.  But even this growth by the top 10% was small compared to that enjoyed by the top 1%, top 0.1% and especially the top 0.01%.

In other words, if you are among the rich, and especially the super-rich, you have benefited post-Reagan.  It is this elite that account for most of the money given to political campaigns, who drive the political discussion, and from the evidence considered here, have good reason to believe Reagan was positive.

But for the economy as a whole, and especially for those in the middle and lower classes all the way to the 90% mark, growth in living standards was far better before Reagan than it has been after.

The Worsening Distribution of Income: The Top 1% vs. the Other 99%

The Occupy Wall Street and related groups have brought to the fore concerns about the distribution of income in the US.  And there is validity to these concerns, as the distribution of income has deteriorated markedly in recent decades, starting with the Reagan period in the 1980s.  The share of the top 1% has well more than doubled, to a level not seen since the 1920’s just prior to the Great Depression, with this coming out of a declining share of the bottom 90%.

The graph above is taken from material assembled by Professor Emmanuel Saez and his colleagues and co-authors, and is available through his web site (link here). The specific data here is from a July 2010 update of material originally published by Professor Saez with Professor Thomas Piketty in 2003, with data now through 2008.  Professor Saez and colleagues from around the world have assembled an amazing set of data for a large number of countries, using tax return data to produce long time series of family (tax unit) income levels.  Such data can go much farther back in time than available income surveys will allow, to produce historical data otherwise unavailable.  While there are drawbacks (for example, tax units are not always the same as the household units one would prefer), nothing else can span such periods of time.

The US data show that there was a previous boom in the 1920s in the income share of the top 1%, peaking at 23.9% of national income in 1928.  But the share then fell in the Great Depression and during World War II, and with the reforms and structural changes implemented during that period, eventually came to about a 10% share in the 1950s and 1960s, and to about 9% in the 1970s.  But it then started to grow, and reached a 23.5% share in 2007.  It fell back in 2008, with the onset of the financial collapse in the last year of the Bush Administration.  But as noted in this blog posting of November 26 on this site, profits rebounded in 2009 to now, so it is likely the top 1% share has also rebounded.

It is also interesting that this increase in income concentration is essentially only at the very top:  the top 1% is seeing almost all of the increase.  Those in the 90 to 95% percentile, and in the 95 to 99% percentile, have seen some trend rise in their income shares in recent decades, but they have been close to flat.  Rather, the higher share of the top 1% has come out of a falling share of the bottom 90% (the shares of all groups together must sum to 100%).  The share of the bottom 90% has dipped to about 50%, from a level of about 65% (plus of minus a percentage point or two) from 1942 to 1982.  This is a remarkable change after four decades of such stability.

Another interesting calculation, done by Professor Saez, found that 52% of the increase in real national income between 1993 and 2008 accrued to the top 1% of families, even though this top 1% only had a 14% share of national income at the start of this period (and 21% at the end).  That is, more than half of income growth over this 15 year period went to just the top 1% of the population, and where this group accounted for only a 14% share of income at the beginning.  Had the growth been balanced, the top 1% would have obtained 14% of the income growth, not 52% of it.

The data here does not explain why there has been this increasing concentration of income in the US.  One has also seen increasing concentration in other countries around the world in recent decades (the data is available here), which suggests some basic global structural changes are part of the cause.  But the global pattern has not been as extreme as in the US, suggesting that policy changes in the US begun under Reagan and continued since, are also part of the cause.