The Impact of Increasing the Minimum Wage on Unemployment: No Evidence of Harm

Minimum Wage vs. Unemployment Rates, 1950-Jan 2013

Minimum Wage vs. Ratio of Unemployment Rates, 1950-Jan 2013

A.  Introduction

In his State of the Union speech last month, President Obama called for a rise in the federal minimum wage from the current $7.25 per hour to a new rate of $9.00 per hour.  This would be a 24% increase, but would still mean that someone working full time, 40 hours per week, 52 weeks a year (no vacation), would earn only $18,720 a year.  Such a full time worker would still be earning well less than the current federal poverty line for a family of four of $23,050 per year.  The proposed increase is modest.

Republican leaders nonetheless immediately denounced the proposal, asserting that raising the minimum wage would hurt, not help, the poor, as they would lose their jobs.  They assert that instead of seeing an increase in their wage, the minimum wage workers would be fired.  And unlike in many other areas (such as the impact of fiscal policies) the Republican leadership here is making an argument that one would find in an introductory economics course.  Elementary economics would indeed argue that in perfectly competitive markets, an increase in the minimum wage would lead to such workers losing their jobs rather than being paid more.

B.  Have Increases in the Minimum Wage Led to Higher Unemployment of Such Workers in the Past?

But what is the evidence?  If increases in the minimum wage lead to such workers being fired, one would see higher unemployment among such workers very quickly in the months following each increase in the minimum wage in the past.  The graphs above show what in fact has happened.

The first graph shows the federal mandated minimum wage since 1950, in real inflation adjusted terms (using the CPI), plus the unemployment rates for all workers and separately for workers aged 16 to 24.  The data comes from the Bureau of Labor Statistics, but was downloaded for convenience from FRED, the Federal Reserve Economic Data web site maintained by the Federal Reserve Bank of St. Louis.  The unemployment rate for workers aged 16 to 24 is shown separately as one would expect that increases in the minimum wage would increase unemployment especially sharply in that group, if the assertion is correct that increases in the minimum wage lead to such workers losing their jobs.  Approximately 51% of the hourly wage workers earning the minimum wage are in this 16 to 24 age group.

First of all, it is worth noting that the minimum wage, when adjusted to reflect general inflation, is a good deal lower now than a half century ago.  It reached a high (in prices of January 2013) of $10.82 in February 1968, and lows of $6.02 in March 1990 and $5.75 in June 2007.  It averaged close to $9.00 an hour over the twenty-five years of 1957-81 (inclusive), and is only $7.25 currently (almost 20% less).  The Obama proposal is modest, as he has only asked Congress to bring it back to that $9.00 an hour, the rate of a half century ago.

But does one see in the history that increases in the minimum wage lead to a jump in unemployment rates, particularly of the young (and decreases in the minimum wage leading to lower unemployment rates)?  Actually, no.  Unemployment rates do fluctuate a good deal, as they depend on macro conditions in the economy.  But it is hard to see any obvious jump in unemployment rates in the months following the sporadic increases in the real minimum wage we have had over the last more than 60 years.

It is also worth noting that due to the politics of the minimum wage, and the resistance of conservatives and businessmen to higher rates, increases in the minimum wage have been generally infrequent and then relatively large in percentage terms.  This thus provides good material for a test of whether increases in the minimum wage lead quickly to jumps in the unemployment rate (particularly of the young).  Yet one does not see it.

Any relationship might be hard to recognize in part because of the independent rises and falls in unemployment rates due to macro conditions.  The second graph therefore charts the real minimum wage along with a line that shows the ratio of the unemployment rate of those aged 16 to 24 to the unemployment rate for the entire labor force.  This ratio exploits the fact that a relatively high share (about 51%, as noted above) of minimum wage workers are young.  Thus, if it is in fact true that increases in the minimum wage will lead those making the minimum wage to become unemployed, the higher share of such workers in the ages 16 to 24 category will lead to an increase in that ratio.

But the graph does not show such a relationship.  While the real minimum wage has seen many sudden changes, the ratio of unemployment rates often does not then change, and in fact sometimes moves in a direction that is the opposite of what those opposed to increases in the minimum wage would predict.  The one possible exception appears to be a blip seen following the February 1968 increase in the minimum wage.  But this blip occurs in fact four months later (in June 1968; the time scale is compressed as the chart covers 63 years) and then drops back.  But one also sees that the steady decline in the real minimum wage during the 1980s in the Reagan years was accompanied by a rise in the ratio (the opposite of what they would predict), and that the ratio then declined (instead of rising) when the minimum wage was finally moved up in 1990 and 1991.  Similarly, increases in 2007-09 were accompanied by  a decline in the ratio.  One could pick out other examples, but basically what is shown is that there is no systematic pattern.

C.  More Rigorous Work on the Impact on Employment from Raising the Minimum Wage Also Shows No Harm

Graphs such as these are, however, simplistic.  While looking at the history is of interest, and should show at least some indication that increases in the minimum wage will lead to higher unemployment (especially of the young) if the minimum wage critics were correct, there is much more going on in the economy which should be taken into account.  Fortunately there have been rigorous studies that do this, and they too have found that the impact of increases in the minimum wage (of the magnitude historically seen) on unemployment rate is either non-existent or small.  Some studies have indeed found that increases in the minimum wage have reduced unemployment.

The seminal paper that launched the modern literature on the impact of the minimum wage was co-authored by economists David Card (of University of California, Berkeley) and Alan Krueger (then of Princeton, and now Chairman of the Council of Economic Advisors in the White House).  Card and Krueger controlled for extraneous effects that might be going on in the economy at the time a minimum wage is increased, by exploiting the fact that states may have separate minimum wage requirements from the federal requirements, and that states change their minimum wages at different times.  Specifically, they looked at employment in fast food establishments along the border between New Jersey and Pennsylvania on an occasion when New Jersey raised its minimum wage while there was no change in Pennsylvania.  They found no negative employment impact from New Jersey’s action.  Indeed, there might have been a small positive impact on employment following the increase in New Jersey’s minimum wage.

The Card and Krueger study, while rigorous, was limited as it looked at only one instance of a change in the minimum wage, and the impact on only one industry.  But more recent studies, following a similar approach, have extended the Card-Krueger work to many more cases.  A particularly comprehensive recent example is a paper by the economists Arindrajit Dube, William Lester, and Michael Reich.  Like Card-Krueger, they too found that increases in the minimum wage that have been periodically enacted in the US at the state level have not had a negative impact on employment of minimum wage workers.  And since changes at the state level would presumably have a bigger impact than changes at the national level (as jobs could in principle shift across state lines), there is no reason to believe the impact of a federally mandated change would be negative.

There is of course much more work on this issue, and a paper by John Schmitt issued last month provides a good summary of where the literature stands.  Less technical reviews of the issues and what economists have found are available here and here.  There are, of course, economists who would disagree, but the preponderance of the work done so far has found little or no evidence that increases in the minimum wage that we have seen in the past have led to decreases in employment of such workers.  Indeed, some studies have found that increases in the minimum wage increases employment.

D.  Why Does Standard Economic Theory Get This Wrong?

The real world evidence matters more than the theory.  But why would standard elementary economic theory appear to have gotten this wrong?  The truth is that there are many matters in the real world that do not behave as one might predict based purely on an economic abstraction.  Unemployment exists, for example, even though economic theory would predict that in a world of perfect competition, with full information and no transactions costs, and many other conditions, we should only see full employment.   But the assumptions of abstract economic models might well not apply in critically important ways once one faces the specifics of a particular issue.  That is why real world testing is important, as well as examination of the underlying assumptions and abstractions.

In the case of employment of workers at or close to the minimum wage, there are many reasons why the predictions of pure economic theory might well not apply.  Such labor markets are far from the perfect competition ideal.  There is a different balance of bargaining and other power between the employer and the potential minimum wage employee; the information available to each side of the transaction (on how productive the worker might be, and what his or her alternatives are) will differ; workers once they are in a job gain a good amount of job specific knowledge and abilities (not only on how to do the specific job, but also how best to work in a team with the specific colleagues there, where things are kept, and a million other details); that due to such job specific knowledge and imperfect information on who else might be available in the market, there will be substantial transactions costs incurred when an employee quits a job or is fired and a new one must be hired; and more.  Standard theory predicts that workers (in a perfect market) will be paid the value of their marginal product, but it can be difficult even to know what the marginal product of a specific worker might be when they work, as they typically do, in a team with others.  And one finds in the real world that wages are typically paid according to seniority and according to some hierarchy, rather than according to some strictly measured marginal productivity.

Good economists are therefore not surprised that markets in the real world can act quite differently from how the simple models might predict.  And they therefore accept as quite possible the finding of the real world empirical studies that increases in the minimum wage, such as those observed in the past, might well not have led to jumps in unemployment of workers earning the minimum wage.

E.  Conclusion

Full time workers in minimum wage jobs are poor, despite their evident willingness to work.  Even if the minimum wage is raised to $9.00 an hour from the current $7.25 an hour, as Obama has proposed, these working poor will still be earning well less than poverty line income.  And bringing the minimum wage to $9.00 an hour will only bring it back to where it was more than a half century ago.  Real GDP per capita has more than doubled over this period.  Yet minimum wage workers are currently earning 20% less.

Rigorous empirical studies do not show that increasing the minimum wage by an amount such as this will lead to an increase in unemployment of such workers.  Nor does one see such an increase in unemployment in a more casual examination of the evidence, such as in the graphs above.  While the poor need more assistance than just from this, increasing the minimum wage as Obama has proposed would certainly be an important help.

The Shift from Equitable to Inequitable Growth After 1980: Helping the Rich Has Not Helped the Not-So-Rich

I.  Introduction

Central in the debate in this year’s presidential election is whether government provision of new benefits and additional tax breaks to the rich will in the end also help the not-so-rich.  Mitt Romney, himself a good representative of those who have become extremely rich through finance, as well as other Republicans, argue that the rich must be helped and given further tax breaks as they are the “job creators” who in the end help us all.  The alternative view is that at best the help to the rich will be kept by the rich, and whatever goes to the rich (whether through additional government provided benefits to the rich, or through how the economy itself benefits the rich) will come dollar for dollar from what would otherwise go to the not-so-rich, thus worsening their position.

This blog posting will examine evidence behind this issue, through a look at long-term growth in the US (going back to 1870), and how this growth has been distributed between the rich and the not-so-rich (for the period we have data, from 1917).  It will find that long-run growth (growth in economic capacity) has been remarkably constant since 1870, which calls into question whether government policies have had much of an effect one way or the other on growth over the long term.

But it will also find that how this growth is distributed among income groups has changed markedly over time.  Growth was equitable from World War II (following the reforms of the New Deal era) until 1980, with all income groups (rich and not-so-rich) benefiting similarly.  But this changed markedly after about 1980, following the measures deemed the “Reagan Revolution”.  Since 1980, the rich have become much richer indeed, while the bottom 90% of households have seen their real incomes stagnate or even decline.

II.  The Growth in GDP per Capita in the US

We start with a look at the growth of per capita GDP in the United States, going back to 1870:

Levels of US GDP per capita, 1870 to 2011, in constant dollars, long-run growth

The numbers are principally from data put together by the late Angus Maddison, who in his career at the OECD and elsewhere assembled a remarkable set of data on growth over the long term of not only the US, but also of much of the rest of the world.  The Maddison numbers were extended to cover 2007 to 2011 based on figures in the regular GDP accounts of the US issued by the BEA in the US Department of Commerce.

The figure shows the growth of US per capita GDP from about $3,500 in 1870 (in terms of 2005 prices) to $43,000 today.  By way of comparison, China’s GDP per capita is currently about $4,800 (in 2005 prices), which is about where the US was in the late 1880s.

While there have been some fluctuations (notably in the downturn in the 1930s during the Great Depression, and then the spike in the early 1940s during World War II), it is difficult to see in a figure such as this whether growth in recent decades has been faster or slower or the same as in earlier periods.  But this can be easily seen if the numbers are converted into their logarithmic equivalent.  In logarithms, a constant rate of growth will be a straight line; an increasing rate of growth will be seen as a line bending upwards; while a decreasing rate of growth will be seen as a line bending downwards.  If you are not familiar with logarithms, you can either take my word for this or consult your high school math textbook.

Converting the GDP per capita numbers into their logarithmic equivalent (these are in 1990 prices, which Maddison had used, but the base year for this does not matter), one finds:

Natural logarithms of US GDP per capita, 1870 to 2011, straight line growth

The red line drawn through this is a straight line, indicating a steady rate of growth of per capita GDP over this 141 year period (at a rate of 1.9% per year, or 1.869% per year to be more precise).  This is remarkable.  REMARKABLE!   There are significant year to year variations, and sometimes decade long variations (such as in the 1930s during the Great Depression, and the spike during World War II).  But eventually, even after the shocks of the Great Depression and of World War II, the economy has always returned to the same path it had been on before, not to a different one.

The path can perhaps best be interpreted as the growth in productive capacity when all resources, and in particular all labor resources, are being fully employed.  This capacity limit for the economy grows over time based on growth in technology and in the skills applied in using that technology as well as in using labor and other resources.  And for some reason we do not understand, the rate of growth on that path has been the same for over 140 years.

It is remarkable that that rate of growth in productive capacity was the same in the closing decades of the 20th century as it was in the closing decades of the 19th century, and in the connecting periods in between.  That is, the rate of growth in the age of steam and rail in the latter 1800s, or growth in the age of microchips and information in recent decades, and everything in between, has always been the same.

This finding should be rather disconcerting to economists.  Hardly a week goes by that a book is not published which says that the key to faster growth is to do … (with each saying something different).  Yet the steady pace of long-term growth at 1.9% per capita a year suggests that for a developed country like the US, operating close to what technology allows in terms of overall production, growth in capacity will be little affected by less regulation or by more regulation, by more investment in education or by less investment in education, by more spending on research and development or by less spending on research and development, and so on.  All of these have varied greatly over time.  But the long-run rate of growth has not.

To be fair, merely showing such constancy in long-run growth does not prove anything.  It is possible that policies have varied over time in such a way that changes which would have raised the long-run rate of growth were offset by policies that reduced the long-run rate of growth by the same amount.  This is possible, but it would be an amazing coincidence if there were always such exact offsets.

What is fair to say is that the reasons behind this long-term constancy in the rate of growth are not well understood, and that economists, politicians, and others should be modest when they advocate one policy or another.

III.  The Distribution of the Income Produced by That Growth

While there has been constancy in the growth of average per capita income, this does not mean that different income groups have necessarily shared equally in that growth.  But while such distributional data are not assembled in the regular national income (GDP) accounts, Thomas Piketty and Emmanuel Saez (as part of a larger international effort) have assembled such data based on US income tax returns.  The concept of income is not exactly the same.  GDP measures the value of all production in any specific year (which ultimately accrues to someone), while tax returns report on taxable household incomes in any year, including realized capital gains but not items such as unrealized capital gains.  But over long periods of time they will move similarly.  By using US income tax return data, Piketty and Saez are able to arrive at estimates going back to 1917 (and 1913 for some of the data, the year the modern US Income Tax system began).  And by using tax return data, Piketty and Saez are able to arrive at accurate figures on the incomes of the very rich (including the top 1%, top 0.1% and top 0.01%), which survey based methods cannot cover well as the numbers in such groups will be relatively small in any broad-based sample.

Using the Piketty-Saez data, one can arrive at the following:

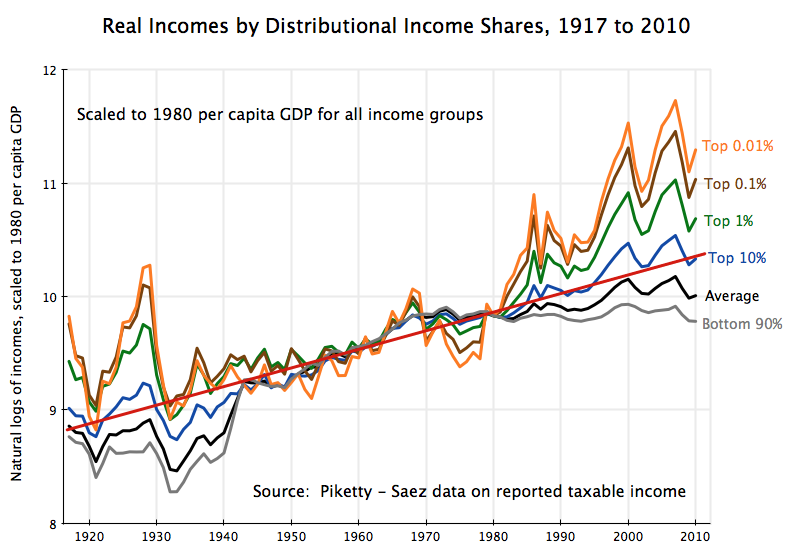
real incomes by distributional shares, 1917 to 2010

This is an unconventional presentation, as the aim is to focus on how real per capita (actually per tax unit, which is normally a household) distributional shares have varied against each other over time.  In this presentation, the incomes (in logarithms) are presented relative to what they were in 1980.  The 1980 figures could have all been set equal to 100.  But to facilitate comparison with the figure above on average GDP per capita (in logarithms), the scale is set to average per capita GDP in 1980.  To state this point again:  All incomes were not equal in 1980.  The top 0.01% earned far more than the bottom 90%.  But to show the changes relative to 1980 as the base year, all incomes were scaled to the same number in 1980 (which could have been anything, such as 100, but which in this case was set to the log of per capita GDP in 1980).

Several things are clear in this figure.  First, the very rich (top 1% and higher) did very well in the 1920s, even though the bottom 90% saw their incomes stagnate.  The “Roaring 20s” were not a boom for everyone.  But everyone then saw their incomes collapse with the on-set of the Great Depression in the 1930s, with only a slow and partial recovery during the decade until the largest fiscal stimulus program in history (spending in World War II) was implemented in the early 1940s.

Then, from the middle of World War II to 1980, the incomes of all of the groups rose by similar proportions (with each of the groups enjoying an increase in real incomes of about 80% per household), with only limited differences between the groups.  This was a period of not only growth, but equitable growth.

Things then changed in the early 1980s.  While overall growth continued (although perhaps at a somewhat slower rate, depending on the precise dates chosen), all of the benefits of this growth was accruing to the rich (the top 1%) and especially the very rich (the top 0.1%, and the top 0.01% even more so).  The bottom 90% saw their incomes stagnate, or even decline depending on the year chosen for comparison.

Note that there is no mathematical reason leading to the top 0.01% seeing their incomes necessarily grow by more than the top 0.1%, who in turn saw their incomes grow by more than the top 1%, and so on.  The figure shows the proportional changes in the real incomes in these different groups defined relative to what they were in 1980, and one can see in the diagram periods in the past where the top 0.01% fared worse than the top 0.1%, for example.  It is only since 1980 that one sees this non-overlapping stratification, with the incomes of the absolute richest increasing by more than the incomes of the very rich, with these increasing by more than the incomes of the moderately rich, and so on down the scale.  The changes in the economy since 1980, whether due to Reagan or for other reasons, not only benefited the rich, but benefited the absolute richest the most of all.

But what is true mathematically is that if the average per capita income is growing at some rate as it has historically, as it appears to have since 1870, then a higher share going to the rich and especially the very rich must be matched by a lower share going to the not-so-rich.  This is then not a story where helping the rich will help us all, but rather a story that what goes to the rich must be coming from the not-so-rich.  And that, unfortunately, seems to be consistent with the data depicted above, where the rich have done very well since 1980, while the bottom 90% have seen their real incomes stagnate and indeed decline to below 1980 levels following the 2008 collapse.

IV.  The Changes in the Real Incomes of the Different Groups Since 1980

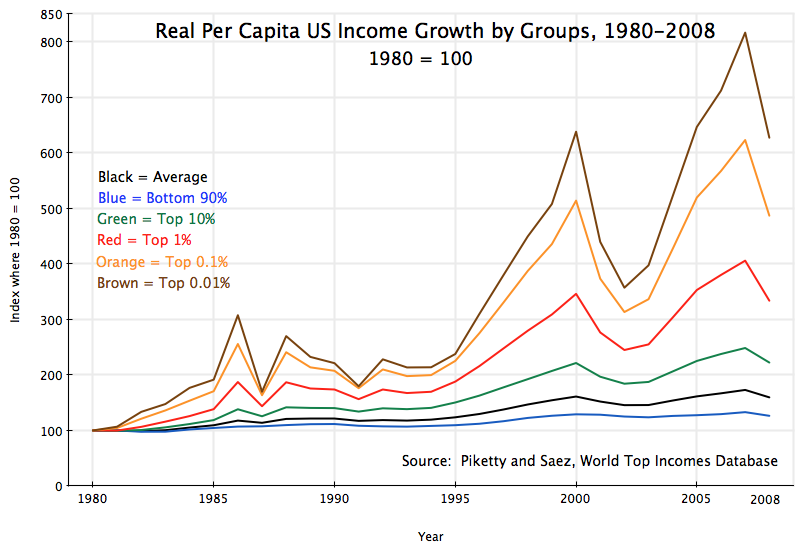
The proportional changes in the incomes of the different groups in absolute values (not logarithms) since 1980 has been as follows:

US real income growth by distributional shares, 1980 to 2010

The rich have done very well since the 1980s and the start of the “Reagan Revolution”.  Even following the 2008 economic and financial collapse in the last year of the Bush Administration, the top 0.01% in 2010 earned 333% more in real terms than what they earned in 1980.  The average income of those in the top 0.01% bracket in 2010 was $23.8 million.  And they were doing much better in 2007 before the 2008 economic collapse, when their income was 570% above what it had been in 1980 in real terms, and they earned an average of $36.9 million (in prices of 2010) each.

In contrast to the rich, the bottom 90% have seen their incomes stagnate since 1980.  In 2010, their income was 5% below what it was in 1980.  They were doing modestly better during the Clinton years, and their real incomes peaked at 11% above their 1980 level in 2000.  But their incomes then fell, to only 3% higher in 2003 than in 1980, recovered a bit to 9% higher in 2007, but then fell again in the 2008 collapse.

Note also that it really is the super-rich who have benefited in this post-Reagan economic system.  Even the top 10% saw their incomes grow by only 65% over the thirty years from 1980 to 2010.  Thirty years of growth at the long-term rate for US per capita GDP of 1.9% would have led to a 76% increase in their real incomes.  And the top 10% includes the top 1% (and richer), whose huge income increases will raise the average for the top 10%.  Excluding the top 1%, the real incomes of the remaining 9% (i.e., those with incomes between the 90th and 99th percentiles) rose by only 35% over this thirty year period.

V.  Summary and Conclusion

In summary:

a)  The long-run rate of growth in the US has been remarkably stable since 1870, at 1.9% a year.  It has maintained this rate from the age of steam and rail, to the current age of microchips and information.  Economists have no good explanation of this, which suggests a good deal of skepticism is warranted when economists, politicians, or others suggest they know the secret to how to raise the rate of long-term growth.

b)  In contrast to this stable rate of long-term growth, the pattern of how this growth has been distributed across the population has varied a good deal, at least back to 1917 (the earliest year for which we have complete data).  Distribution worsened in the 1920s and became less unequal only with the start of the massive stimulus program of World War II.  Then from the middle of that war to 1980, the economy grew with both the rich and the not-so-rich sharing similarly in growth.

c)  This then changed after 1980, with massive growth in real incomes for the very rich, while the bottom 90% saw their incomes stagnate or get worse.

The Republican policies launched by Reagan of low taxes on the rich plus financial and other deregulation were justified on the basis of the assertion that they would lead the economy to grow faster, and that all income groups would benefit from this.  There is no evidence in the data that this has occurred.  Growth has not accelerated.  If anything, growth has decelerated, although this could still reflect a downswing from which the economy could eventually recover as it did following the 1930s.  The rich have nonetheless gotten very rich since 1980, while the bottom 90% have suffered.  The data suggest that the Reagan policies have not acted to accelerate growth for all, but rather have acted to transfer the gains that there were to the rich from those in not so advantageous a position.

Given how Mitt Romney himself has benefited from this Reagan program, it should not be surprising that not only does he support it, but that he wants to extend it even further.  But it is not clear why those not in his super-rich class should agree.

_______________________________________________________________________

Update – April 19, 2013

A reader of this blog has asked me a very good question through the Contact Me form.  As others may have a similar question, I thought it best to try to provide an answer here, for all to see.

The question raised was that in the final graph shown on the blog (titled “Changes in Real Per Unit  Incomes by Distributional Shares”), average real income per unit is reported to have risen by only 19% between 1980 and 2010.  Yet if real GDP per capita had grown at the long term trend of 1.9% per year over this period, real GDP per capita would have increased by 76%.  Why the big difference?

The difference is indeed very large.  One would not normally expect such a divergence.  But there are several reasons for this.  I had noted one in the original posting, but there are others as well.

In the original post I noted that the Piketty-Saez data, based on incomes reported on tax returns, will differ from incomes as reported in the GDP accounts as they are measuring different concepts of income.  The GDP accounts measure the value of all production in any given year.  While that income will eventually accrue to someone, it will differ from incomes reported by households on their annual tax returns.  A major part of income in the GDP accounts, for example, will first be earned by corporate entities.  While corporations do pay a portion of this in dividends to their owners, a portion is retained and not immediately paid out.  The portions can vary over time.  And household taxable income includes not only what is currently earned in wages or received in dividends, but also capital gains that are realized through the purchase and sale of assets.  Such capital gains are not part of the GDP accounts, as they do not reflect the value of current production.

But there are other reasons as well for the difference.  Specifically:

  1. First, while growth at the trend rate of 1.9% per year would have led to a rise in real GDP per capita of 76% over 30 years, the actual GDP per capita growth over 1980 to 2010 was 65%.  Due to the 2008 downturn, from which there has been only a partial recovery, GDP in 2010 was about 6% below the capacity level of GDP in that year. One can see in the graph above of GDP per capita in logarithms how the actual per capita GDP fell below the trend from 2008.  And while all economists expect the economy to recover eventually, it is not known how long this will take (it will depend on policy).
  2. The change in real GDP is determined using the GDP deflator for the price index. The GDP deflator is based on the prices of all goods that make up GDP, which includes not only the goods that households consume, but also investment goods as well as the prices of imports and exports.  Piketty-Saez, in contrast, are focused on household real incomes, and therefore have used the Consumer Price Index (CPI) as their price deflator.  The two price indices differed markedly over the 1980 to 2010 time period:  the GDP deflator rose by 32% while the CPI used by Piketty-Saez rose by 52%.  Had GDP per capita been deflated by the CPI rather than the GDP deflator, measured real per capita GDP would have risen by 43% instead of 65%.
  3. Real GDP per capita is based on the whole US population, while the Piketty-Saez data is based on reporting tax units.  Tax units are generally households.  Over the 1980 to 2010 period, the number of households rose at a faster pace than population, as the average household size fell (fewer children as well as more households reflecting a single adult).  Over 1980 to 2010, population rose by 36% while the number of tax units (households) rose by 57%.  Adjusting for this, real per unit GDP (based on the CPI, as per above) would have risen by 25% based on the number of tax units rather than 43% based on population.
  4. The final difference between this 25% increase and the 19% increase in real per unit average incomes reported in the Piketty-Saez data can be accounted for by the differences in definition between taxable household income and GDP.

Taxes as a Share of Income Are the Lowest in Decades, While Income Distribution is Close to the Worst

US Federal Government Revenues as Share of GDP, 1960-2011, Federal Taxes, Federal Receipts

An excellent report from the Congressional Budget Office was issued yesterday, and has received a fair amount of publicity for noting that taxes in the US as a share of income are the lowest in at least 30 years (their analysis went back to 1979).  See, for example, this article in today’s Washington Post.  The CBO findings are correct, and carefully done, but readers of this blog may recall a posting from April 22, which also noted that taxes as a share of income are the lowest in over a half century (and indeed the lowest since 1950).  The graph above is copied from that post.

The CBO report looks at taxes as a share of household incomes, relying on data from the IRS and the Census Bureau, and hence had data only through 2009.  The data I used comes from the National Income and Product Accounts (GDP Accounts) of the Bureau of Economic Analysis in the Department of Commerce, which had data through 2011 (and now up to the first quarter of 2012).  But both come to the same basic conclusion:  That taxes as a share of income are the lowest in decades.  Republicans have asserted that high and rising taxes are the reason the economy has not recovered from the 2008 downturn, and that therefore further tax cuts are needed.  But there is no factual support for this.

Taxes are low in part precisely because of the 2008 collapse, with conditions only turning around in mid-2009, soon after Obama took office.  Incomes fell, and therefore taxes due fell as well and indeed fell by more.  But the low taxes are not simply a result of the downturn.  The economic downturn in 1982-83 under Reagan was also sharp, and the unemployment rate then hit a peak of 10.8%, or much more than the 10.0% peak reached in the current downturn.  But taxes during this Reagan period as a share of income did not then fall to as low a share as they have now.  The reason is the Bush tax cuts, which had already put taxes on a falling trend, plus an additional $1.5 trillion in tax cuts signed by Obama since he took office.  Tax cuts are one of the few areas where Obama can get support from a Republican congress for passage.  See the April 22 post for details on these tax cuts under Obama.

With the data it had access to, the CBO report could go into other areas as well, including distributional issues.  It merits a close look.  Figure 6 on page 15 is particularly interesting.  It shows that real after tax income growth for the bottom 80% of the population over the last 30 years (basically since Reagan), has been modest at best, while it has been spectacular for the top 1%.  Based on data published along with the report (in the Supplementary Tables), one can calculate that income growth for the bottom 80% of the population has averaged just 1.1% a year, and was fairly similar for each of the quintiles (i.e. for the 0 to 20%, 21 to 40%, 41 to 60%, and 61 to 80% quintiles), with a range of only between 0.9% and 1.2% for the annual average growth rates.  After 30 years, real incomes grew by a total of only 38% for the bottom 80% of the US population.

In contrast, real income was 155% higher in 2009 than it was in 1979 for the top 1%.  And the 2009 income was relatively low due to the 2008 economic collapse (and we know from other sources that the income of the very rich then bounced back in 2010 and 2011).  In 2007, real after tax incomes of the top 1% was 304% above where it was in 1979.  For the bottom 80%, changing to a 2007 base makes little difference:  it was only 38.6% higher.  It is also interesting to note that it is really only the top 1% that has gained so spectacularly in this post-Reagan period.  Total real after tax income growth between 1979 and 2009 was 50% for the 81 to 90th percentile, was 61% for the 91 to 95th percentile, and was 70% for the 96 to 99th percentile.  The spectacular growth is only seen in the top 1%.

The results are similar to what was shown in a graph I had in a January 29, 2012, post on this blog, on the impact of Reagan, reproduced here and which uses data from Thomas Piketty and Emmanuel Saez:

impact of Reagan on growth of real incomes, bottom 90%, top 10%, top 1%, top 0.1%, top 0.01%, 1980-2008

The pattern is similar.  There has been spectacular income growth since Reagan for the top 1%, and even more so for the top 0.1% or top 0.01%, but not for everyone else.