The Growing Inequality in Wealth in the US, Part 1 – Basic Facts

Chart 1

A.  Introduction

The extreme, and growing, inequality in wealth ownership in the US has been receiving increasing attention.  In its most recent annual listing of the 400 most wealthy Americans (from September 15, 2026), Forbes estimates that 15 individuals (and their immediate families) each have a wealth of $100 billion or more, seven have a wealth of $200 billion or more, and the top one – Elon Musk – had a wealth (as of the date of publication) of over $900 billion.  Concern with such concentration of wealth has also grown as a number of these ultra-wealthy individuals have become increasingly politically active, using their wealth in ways that can determine election outcomes and overwhelm basic democratic institutions.  This became especially evident in the 2024 presidential election, with consequences that are now clear.

This post, and several to follow, will review the basic data that estimate the inequality in wealth holdings and how that inequality has grown in recent decades.  This first post will look at wealth per household (more precisely net worth, but the terms will be used interchangeably) with the households ranked by their level of wealth from least to most:  the bottom 50%, the 50 to 90%, the 90 to 99%, the 99.0 to 99.9%, and the top 0.1%.

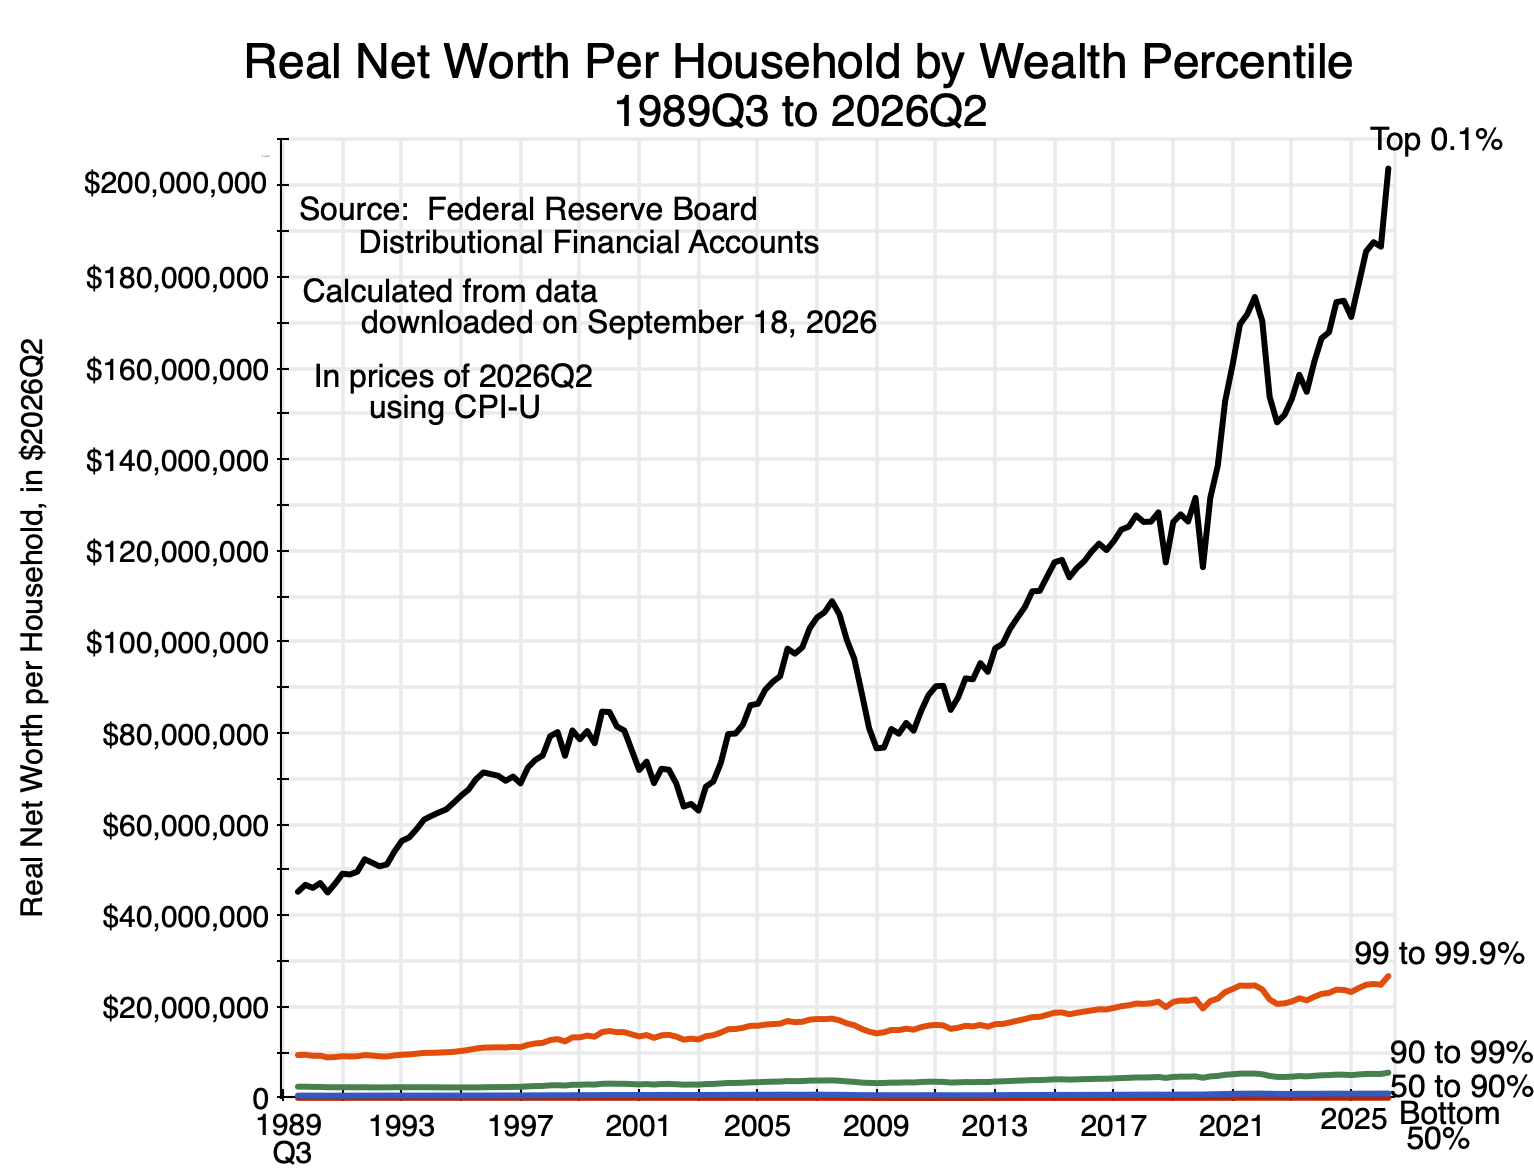
The chart at the top of this post shows how that net worth has grown (in real terms) over the last several decades.  Because of the immense wealth of the top 0.1% – whose average net worth grew to over $200 million per household – it is hard to see on the chart the average wealth of the bottom 99% of the population.  Their net worth is just too small.  Charts below will split out the bottom 99% to show their histories, but the point is that the disparity between the top 0.1% and the rest is so large that – other than for the top 1% – their average holdings disappear on the scale of the chart.

The post will first discuss in Section B below the data for these estimates.  They were calculated from data estimated by staff at the Federal Reserve Board and released as its Distributional Financial Accounts.  This source is widely considered the best set of estimates on household wealth available for the US.  These are, of course, estimates, however, and while the best available, it is important still to recognize their limitations.  Wealth is difficult to estimate, for both conceptual and practical reasons.

Section C will then present the basic estimates of per-household wealth (net worth) when grouped by households ranked by the wealth they hold.  The figures going back to 1989Q3 for all five groups the Fed distinguishes are as in the chart at the top of this post, and charts will then be provided also for the bottom 99% (and its sub-groups) and for the bottom 50%.  Each has a story to tell.

Section D examines how the wealth estimates have changed over time in real terms and per household relative to what they were in the earliest period in this data series (1989Q3).  Inequality was already high in 1989, but then grew much more.  Section E will decompose the figures for average overall wealth, linking their increase to the growth in GDP over the period, to the increasing share of profits in GDP (at the expense of wages), and to the increase in how that wealth is valued as a multiple of the profits the owners of the assets are entitled to.

Section F will conclude.  Future posts will examine other aspects of wealth holdings, using the same Fed data, including on wealth holdings when households are ranked by their income levels rather than their wealth levels, and on wealth holdings at the same age for different generations – i.e. for Baby Boomers compared to generations before and after.  A final post will then examine what might – or might not – be done through policy to address these issues.

B.  The Fed’s Distributional Financial Accounts

The measurement of wealth is not at all straightforward, and poses both conceptual and practical issues.  This is in contrast to the measurement of incomes.  For incomes, there are actual market transactions where firms earn revenues from what they sell.  Out of those revenues the firms pay a portion for the inputs used and for the wages of their employees, with the remainder then being the gross profits that will cover taxes, the interest they pay on their debt, and their investment costs (counted as depreciation).  What remains is their net profits.  All of these transactions (other than depreciation) are measurable in cash being transferred and can be observed.

The measurement of wealth is different.  Wealth is the value that others would be willing to pay for the assets owned.  That is not observed and can only be estimated.  Guessed may be a better term.  It is also in a fundamental sense socially determined, as the measured value of the wealth is not inherent in the asset itself, but rather an estimate of what others – given the state of the economy, their expectations of what the future might be, the availability of financing, and other such factors – might be willing to pay for the asset.  The transfer of the asset does not take place, however, and hence cannot be observed in the manner that incomes are observed.  The value can only be estimated as a hypothetical.

Thus if someone is willing to pay twice as much for an asset (perhaps real estate, or a company, or whatever) than what it was valued at the previous day, the owner of the asset would be richer.  His wealth would be greater.  But nothing fundamental has changed in the economy; the assets are all the same as before.  Only the valuation has changed.

In the face of such issues, statisticians do the best they can.  They need to make assumptions about what others might be willing to pay for the assets.  And they can assemble data on transfers of assets that have recently taken place and hence can be observed, where those assets may be similar – to a greater or lesser degree – to those they are trying to value.  This can inform – to some extent – the valuations they assign to assets that did not change hands.

The calculations discussed in this post (and those that follow in this series) are based on data assembled by staff at the Board of Governors of the Federal Reserve System in Washington, DC, and specifically its Distributional Financial Accounts (DFA).  The DFA estimates are published quarterly, usually about 11 weeks after the end of each calendar quarter.  The accounts for the second quarter of 2026 were released on September 18, and provide estimates for wealth held by households as of the end of the quarter, i.e. on June 30.

The DFA data sets include quarterly data going back to the third quarter of 1989, but were only first produced starting in 2019.  They are based on a combination of two other data sets produced by staff at the Fed Board of Governors, the Survey of Consumer Finances (SCF) – a survey undertaken once every three years –  and the quarterly Financial Accounts of the United States (FA).

The SCF is a survey of households undertaken on behalf of the Fed where household assets and liabilities are recorded in detail, along with household income and characteristics of the household such as the age, education, race, and similar of its members.  Because of this, the Fed can then produce estimates of wealth not simply of households in general, but also of households categorized by their income, their age, education, and/or race, and similar.

A representative sample of households across the country is chosen for the SCF, along with an oversampling of higher-income households in order to get meaningful sample sizes of the more wealthy households that hold a substantial share of household wealth.

The response rate of the general sample is reasonably good – at about 70% – but that for the oversampled wealthy households is only 10%.  This may lead to biases in the results.  While it would not matter if the wealthy households not responding were random (one could then simply start with a sample size ten times larger), it is likely that the relatively more wealthy households within that group are less likely to respond.  The share of the nation’s wealth held by the most wealthy would then be underestimated.  Despite this possible bias in the estimates, we will see below that the share held by the most wealthy groups is nonetheless extremely high.

A point to note is that the SCF specifically excludes any sampling of the extremely wealthy households on the Forbes 400 list of richest Americans.  This might be due to privacy concerns, or simply the recognition that they would be unlikely to respond to the SCF survey even if asked.  However, the DFA accounts specifically add them back in, with assets and liabilities either obtained from Forbes or drawn from the same sources used by Forbes.  The net worth of the top 400 is significant.  In the most recent September 2026 ranking, their total net worth came to $8 trillion.  The DFA estimate of the net worth of the top 0.1% of households as of June 30, 2026, was $28 trillion.  Thus the top 400 alone account for 29% of the total wealth of the group, even though they account for less than 0.3% of the approximately 135,000 households in the top 0.1%.

The SCF is, as noted, conducted only once every three years.  To arrive at the quarterly estimates, the Fed staff use the quarterly Financial Accounts of the United States (FA) data to estimate how the wealth holdings of the households in the groupings analyzed may have changed quarter to quarter.  The FA accounts date back to 1955, and were formerly called the Flow of Funds Accounts.  They track – for the nation as a whole – both the stocks and flows of capital assets (both real and financial) in all their forms across economic sectors such as households, businesses, governments, and financial intermediaries.  They are normally released ten weeks after the end of the quarter, and present financial flows during that quarter along with end-of-period stocks.

The DFA estimates combine the triennial SCF estimates on wealth holdings of categories of households with the quarterly FA estimates of total assets and liabilities held by households in the country as a whole.  But this is not always a simple scaling, for several reasons.  For a full discussion, see this chapter from a NBER conference held in March 2020 (and published in 2022) where Fed staff describe in some detail how the then new DFA accounts were assembled.

Arriving at household holdings of wealth – both assets and liabilities – consistent with national-level estimates of the totals of such assets and liabilities in the economy is not always straightforward.  A couple of examples illustrate this.

One is the accounting of the assets backing up commitments to retirees in defined benefit pension plans.  The SCF does not attempt to include at the household level the assets held in such schemes.  Workers expect they will receive a pension of some amount, which will be tied to how many years they ended up working for the firm and what their final income was (often averaged over some period, such as their final three years).  They will have little idea what assets are being invested to back up those commitments.  But at the national level, the assets of the company pension plans backing up those commitments have been invested and are reflected in the totals in the FA accounts.

To resolve this, the DFA makes an estimate of what a household’s share of the assets held by the pension fund managers would be given the characteristics of the households.  For those who are already retired and are receiving such a pension, plus for those who expect to receive a pension at a certain level based on their past employment with some firm, they calculate the present discounted value (which will depend on their age) of their expected future pension benefits.  They then subtract those present value totals from the assets of the defined benefit pension plans at the national level to arrive at a figure for the pensions of workers still employed, who will start to receive pension benefits once they retire at some future date. They use a similar approach for the determination of the value at the household level of wealth held indirectly in annuity schemes and in life and other insurance plans.  This approach can be easily criticized, but is probably the best that can be done.

As another example of the type of assumptions they had to make, there is an issue with how equity in privately held businesses as well as closely-held corporate entities should be valued.  The SCF reported figures based on the household responses for both the cost basis of such equity and for what the households believed the market value would be.  Aggregated to the national level, the market value estimates were well above the totals in the FA accounts while the cost basis estimates were well below.  However, the average of the two turned out to be close, so they used that.

It should be noted that while estimates are made of the value to the household of the assets held (directly or indirectly) in their defined benefit pension plans as well as their defined contribution plans (401k’s, IRAs, and so on) and annuities from insurers, the DFA accounts do not include the implicit value of their Social Security retirement (and other) benefits.  But the value of those Social Security commitments are significant, and especially so (as a share of their total wealth) for lower-income households.

To illustrate, a standard rule-of-thumb in retirement calculations is to spend each year no more than 4% of the balance of assets held in the retirement accounts at the time of retirement.  The remaining assets will continue to grow in value, but at that 4%, retirees are unlikely to outlive the savings they had to cover retirement.  Based on this, one can calculate the assets that would be required in a private pension savings account to cover benefits equal to those paid by Social Security.

As of December, 2025, the average monthly benefits paid to retirees, along with the average paid to the bottom 50% of retirees and top 50%, were:

Average Monthly Benefit

Annual Equivalent

Capital-Value Using 4% Rule

All Retired Workers

$2,071

$24,854

$621,350

Bottom 50%

$1,338

$16,060

$401,505

Top 50%

$2,813

$33,761

$844,017

Source:  Calculated from data at Social Security – Beneficiaries by benefit level.  For December 2025.

To cover the average benefit to retirees of $2,071 per month, assets of over $620,000 would have been needed if one followed the 4% rule.  For the bottom 50% of retirees (bottom 50% of the recipients of Social Security benefits), it would have been over $400,000, and over $840,000 for the top 50%.  These could be counted as part of household wealth (assuming Social Security keeps to its commitments – which certainly can be done but will require Congress to act).

These are significant amounts.  As will be discussed in the following section below, the average net worth as of June 30, 2026, of the bottom 50% of households (as ranked by their net worth) is only $63,000 in the DFA figures.  For those in the 50 to 90% percentile, the average net worth was $988,000.

At the same time, keep in mind that the assets required by the 4% rule to match what Social Security is paying retirees would be the assets as of the year they retire and start collecting Social Security retirement benefits.  Any individual builds up this entitlement to benefits over their working life, and thus the equivalent value when they are younger would be proportionally less.  Similarly, retirement assets will be drawn down during the years one is retired, so the equivalent assets as one ages after retirement will then also be less.

However, the important point is that Social Security could be seen as a significant addition to household wealth, and especially so for the least wealthy.  The DFA could have included that implicit wealth (with then a suitable adjustment in the treatment of the Social Security Trust Account in the federal government accounts) just as they did for private defined contribution pension plans, but chose not to.

I have given these examples to make clear that the wealth figures really are estimates, where those estimates need to be based on assumptions that can be questioned.  The approach taken is probably the best that has been done to estimate the distribution of wealth in the US, but the limitations should not be forgotten.

C.  Real Net Worth per Household, Stratified by Rank in Terms of Net Worth

There is extreme disparity in the distribution of wealth in the US.  Specific figures by category of household may provide a better sense of this, along with the ownership of the types of assets of each group.  As of the end of the second quarter of 2026:

2026Q2 per Household – in $thousands

Bottom 50%

50 to 90%

90 to 99%

99.0 to 99.9%

Top 0.1%

A.  Total Assets

$152

$1,153

$5,906

$27,454

$205,938

1) Real Estate

$71

$429

$1,240

$3,876

$14,377

2) Consumer durables

$32

$71

$158

$347

$5,413

3) Bank deposits & Money mkt accts

$12

$113

$583

$2,345

$17,790

4) Bonds/Loans

$1

$24

$214

$1,066

$9,418

5) Equities

$8

$180

$2,412

$17,164

$153,056

6) Retirement accts

$19

$304

$1,210

$2,234

$3,873

7) Other

$8

$30

$90

$421

$2,012

B. Total Liabilities

$89

$164

$346

$732

$2,200

1) Home mortgages

$47

$126

$280

$373

$857

2) Consumer credit

$39

$33

$43

$92

$383

3) Other

$3

$5

$23

$267

$960

C.  Net Worth

$63

$988

$5,559

$26,722

$203,738

o/w Net Real Estate

$25

$303

$959

$3,503

$13,520

Source:  Calculated from the data at Fed Board of Governors, Distributional Financial Accounts.  Downloaded September 18, 2026.

Households are ranked here by their net worth – from those with the least (and indeed negative) net worth to those with the most.  The DFA shows the totals held in categories for the bottom 50% of households, for those ranked between 50 and 90%, between 90 and 99%, between 99.0 and 99.9%, and for the top 0.1%, along with the number of households in each group (so one can calculate the per household averages).  As of the end of 2026Q2, there were approximately 135 million households in the US, so the bottom 50% covered the 67.5 million with the least net worth, and then so on to the top 0.1% with approximately 135,000 households.

The DFA data (in what is made publicly available) identify 15 categories of assets and 5 categories of liabilities.  The table above aggregates some of these into broader categories of interest.  The figures shown here are rounded to thousands, and for the reasons discussed in the preceding section of this post, need to be taken as approximate estimates.

Keep in mind also that these are averages over the households in each of the given categories.  The minimum net worth to be included in the categories (in 2022Q2 – the date of the most recent SCF survey used for this categorization) was $240,000 for the 50 to 99% group, $2.1 million for the 90 to 99% group, $11.0 million for the 99.0 to 99.9% group, and $46 million for the top 0.1%.

Also keep in mind that the categories cover individuals of all ages.  The trends over time do not follow the experience of any given individual, who might start out their working life with a very low net worth – and thus is in the bottom 50% of households – but who then accumulates wealth as they grow older and ends up in one of the wealthier groups.  Rather, the figures on the wealth holdings over time are for those in each of the groups (the bottom 50%, the 50 to 90%, and so on) at each point in time.

Furthermore, because the distribution of net worth is highly skewed to the right – both overall and within each category of net worth – the average holdings of a group will be greater than the median holdings.  That is, the median holding – the net worth where half of the households in the group hold less and half hold more – will be less than the averages shown in this table.  Since the DFA files released by the Fed only show total holdings (in nominal terms) and the number of households in each group, one can calculate averages but not medians.

The one exception where a median can be found is the dividing line in net worth between the bottom 50% of households and the next group up (the 50 to 90%).  As noted above, that dividing line in 2022Q2 was $240,000.  Since 50% of households have a net worth less than this, that will be the median for the nation as a whole.  But the average net worth of households in the nation as a whole was $1,043,000 as of the end of 2022Q2.  The average is more than four times the median.  As of the end of 2026Q2, the average net worth was $1,373,000.  (The figures in this paragraph are all in current price terms.)

But even with the qualifiers on the impact of age and the difference between the average and the median due to the skewness of the distributions, I still find it mind-boggling that the DFA estimates indicate that the top 0.1% – 135,000 households in the US – have on average a net worth as of the end of June 2026 of $203.7 million.

The chart at the top of this post shows how the average net worth of households ranked by their wealth percentile has grown since 1989Q3.  To allow for meaningful comparisons over time, these have been adjusted for inflation using the CPI-U index – the most commonly used consumer price index measure in the US.  They are expressed in terms of the prices of 2026Q2.

The average net worth of the top 0.1% of wealth-holders rose from $45.2 million in 1989Q3 (in prices of 2026Q2) to $203.7 million as of the end of 2026Q2.  The substantial increase in wealth of those in the 99.0 to 99.9% group can also be seen in the chart (from $9.4 million on average at the start to $26.7 million now).  But the scale of the chart is such that what happened for those in the bottom 99% is not clear.

Limiting the chart to just the groups in the bottom 99%, one has:
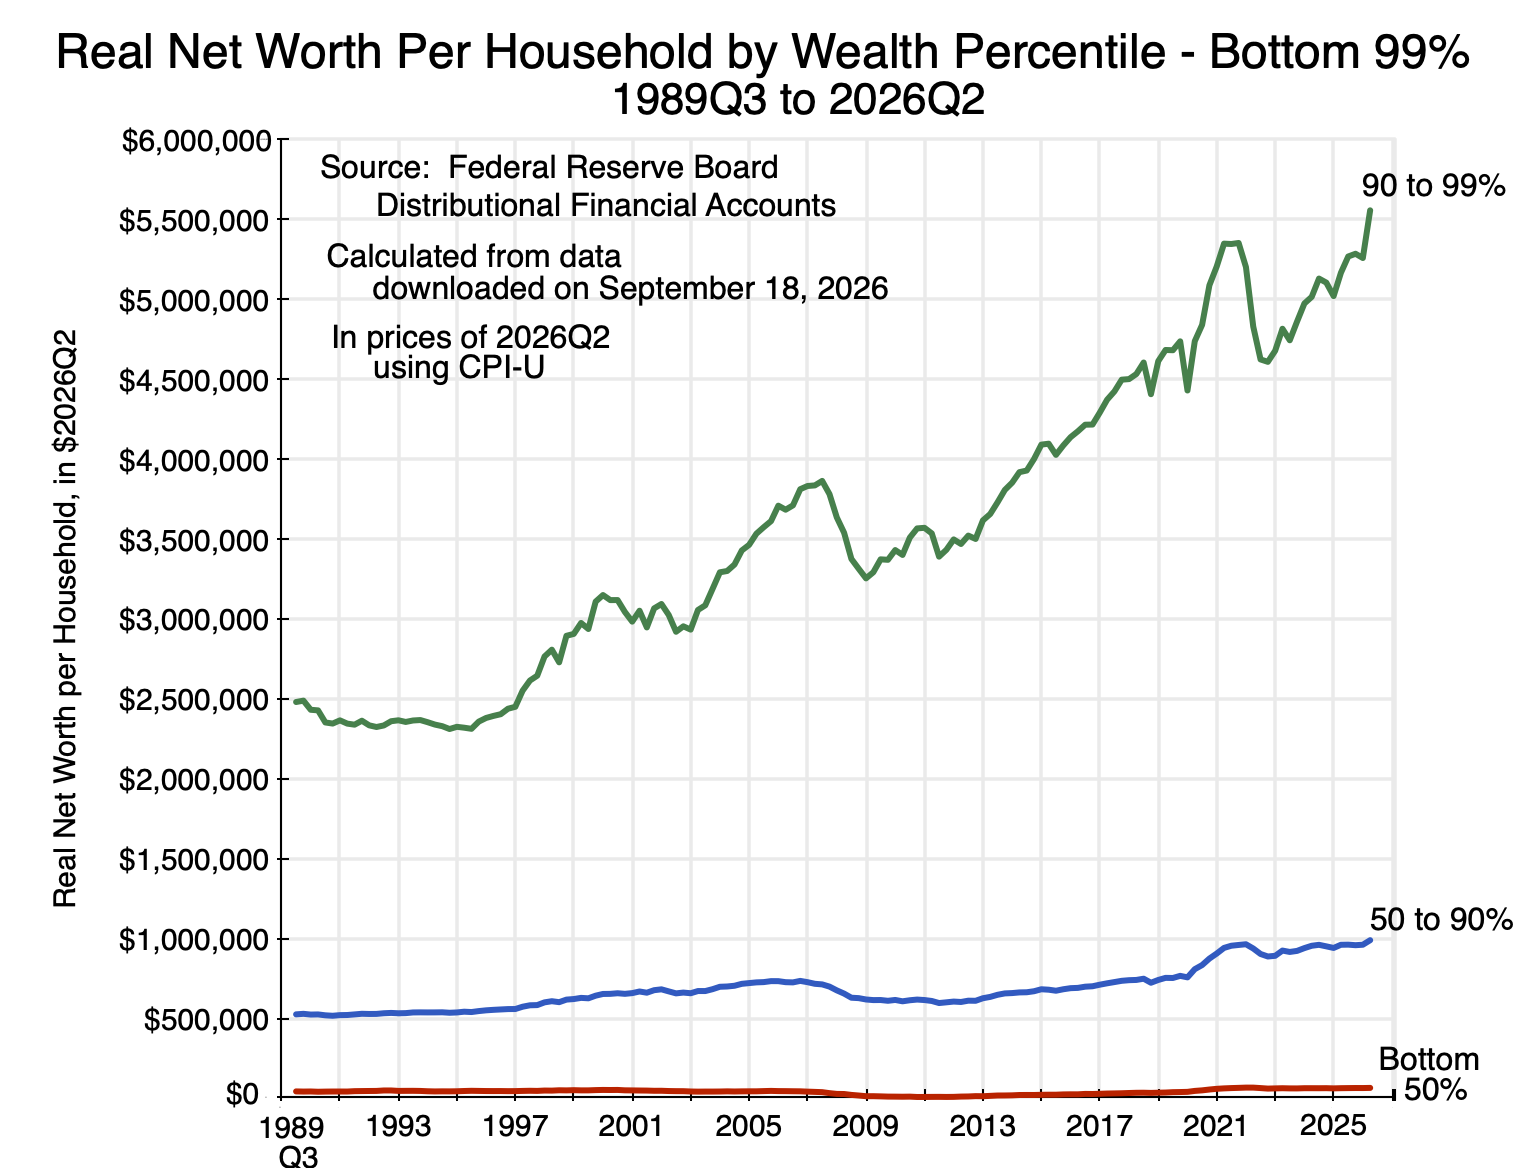
Chart 2

The average net worth of the 90 to 99% group rose over the period from $2.5 million to $5.6 million as of the end of 2026Q2.  The average net worth for the 50 to 90% group rose from $524,000 to $988,000.

The line for the bottom 50% is still not clear, so in a chart on its own:
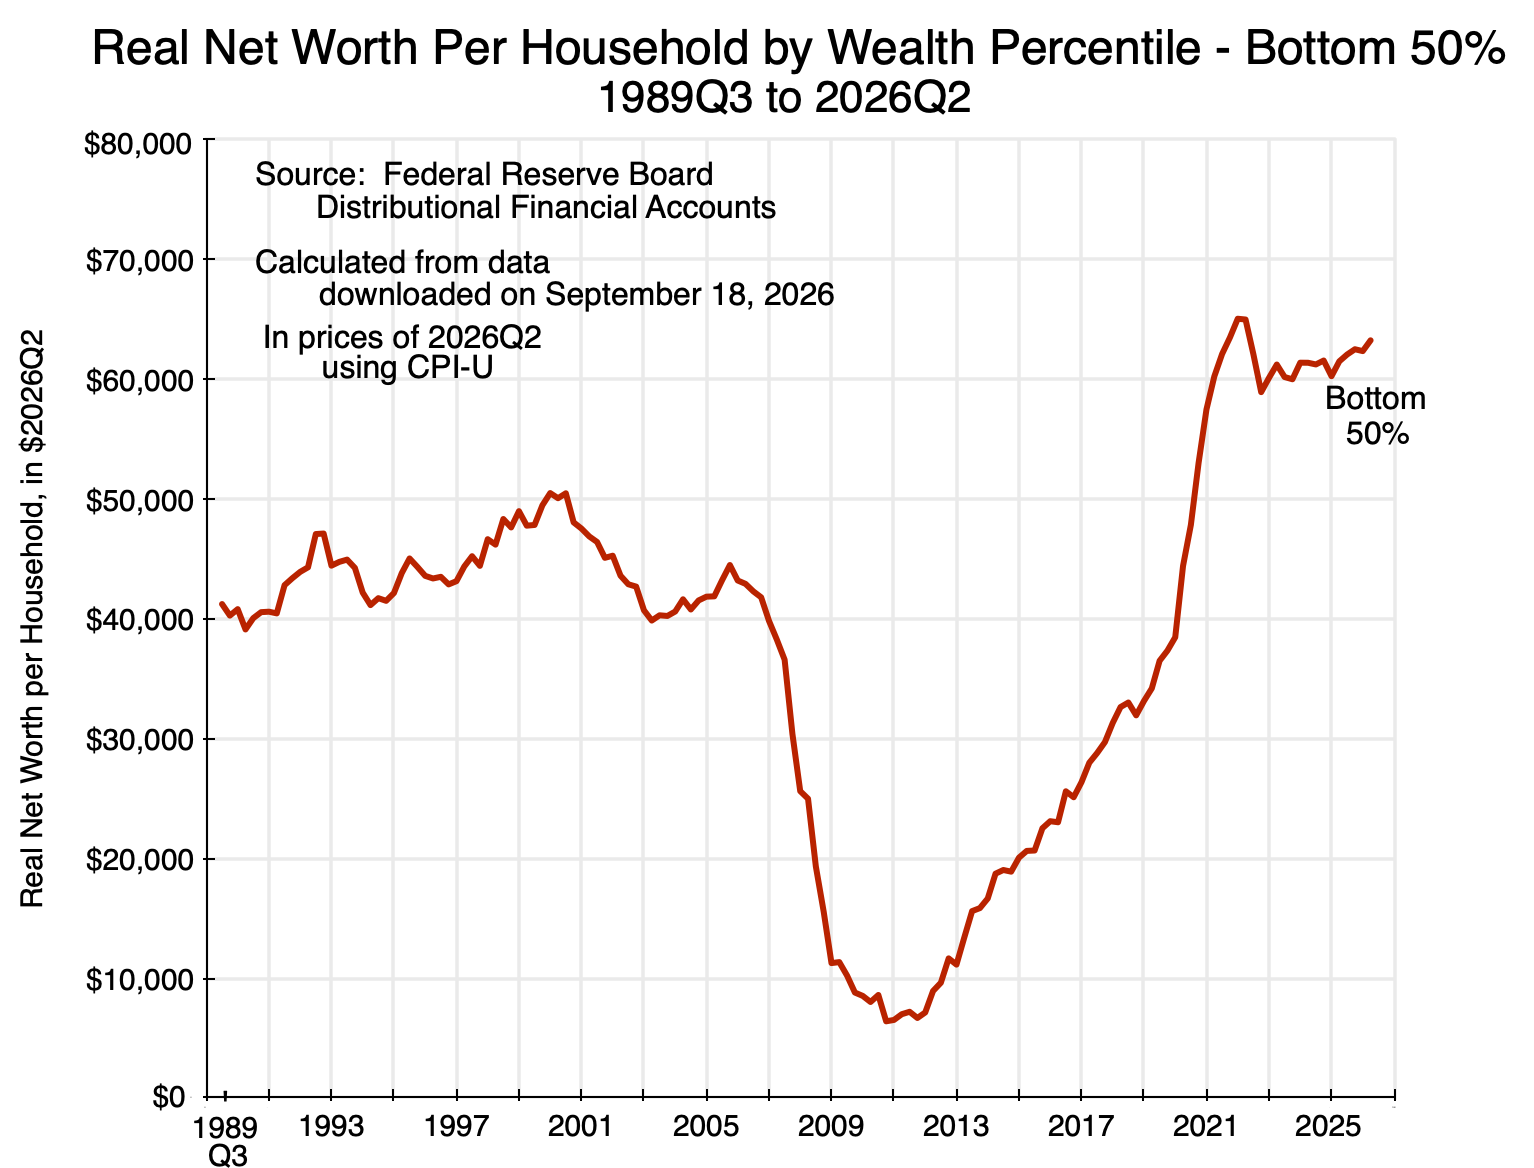
Chart 3

The path is far from steady:  While average net worth for the bottom 50% rose over the full period from $41,200 to $63,300, it fell to a low of just $6,400 in 2010Q4 as a result of the 2008/09 economic and financial crisis.  This primarily reflected the crash in real estate values – assets which account for a disproportionate share of the wealth of the bottom 50%.  The average net value of their real estate wealth (i.e. the value of their real estate assets less that owed on home mortgages) was a negative $15,850 at the end of 2010.

Furthermore, while their net worth then recovered, it did not recover fully until 2020.  The average net worth of the bottom 50% was $44,500 in 2005Q4, and an even higher $50,500 in 2000Q3 near the end of the Clinton presidency.  But as of the end of the third quarter of 2016 (September 30, just before the November election that Trump won), the average net worth of the bottom 50% was only $25,600.  This was only half of what it had been 16 years before.  The disquiet and concern on economic prospects among many in the bottom half of the population should not be surprising.

There is tremendous inequality in net worth across households.  As of mid-2026, the bottom half had an average net worth of only $63,300.  The average net worth of the top 0.1% was over $200 million.  That is over 3,200 times as much.

D.  Inequality is Not Just High, But Also Has Grown

The disparities are gigantic.  But the disparities aren’t only huge:  they’ve grown.  Taking the net worth of each group as a ratio to their level in 1989Q3 (with all in real terms per household), one has:
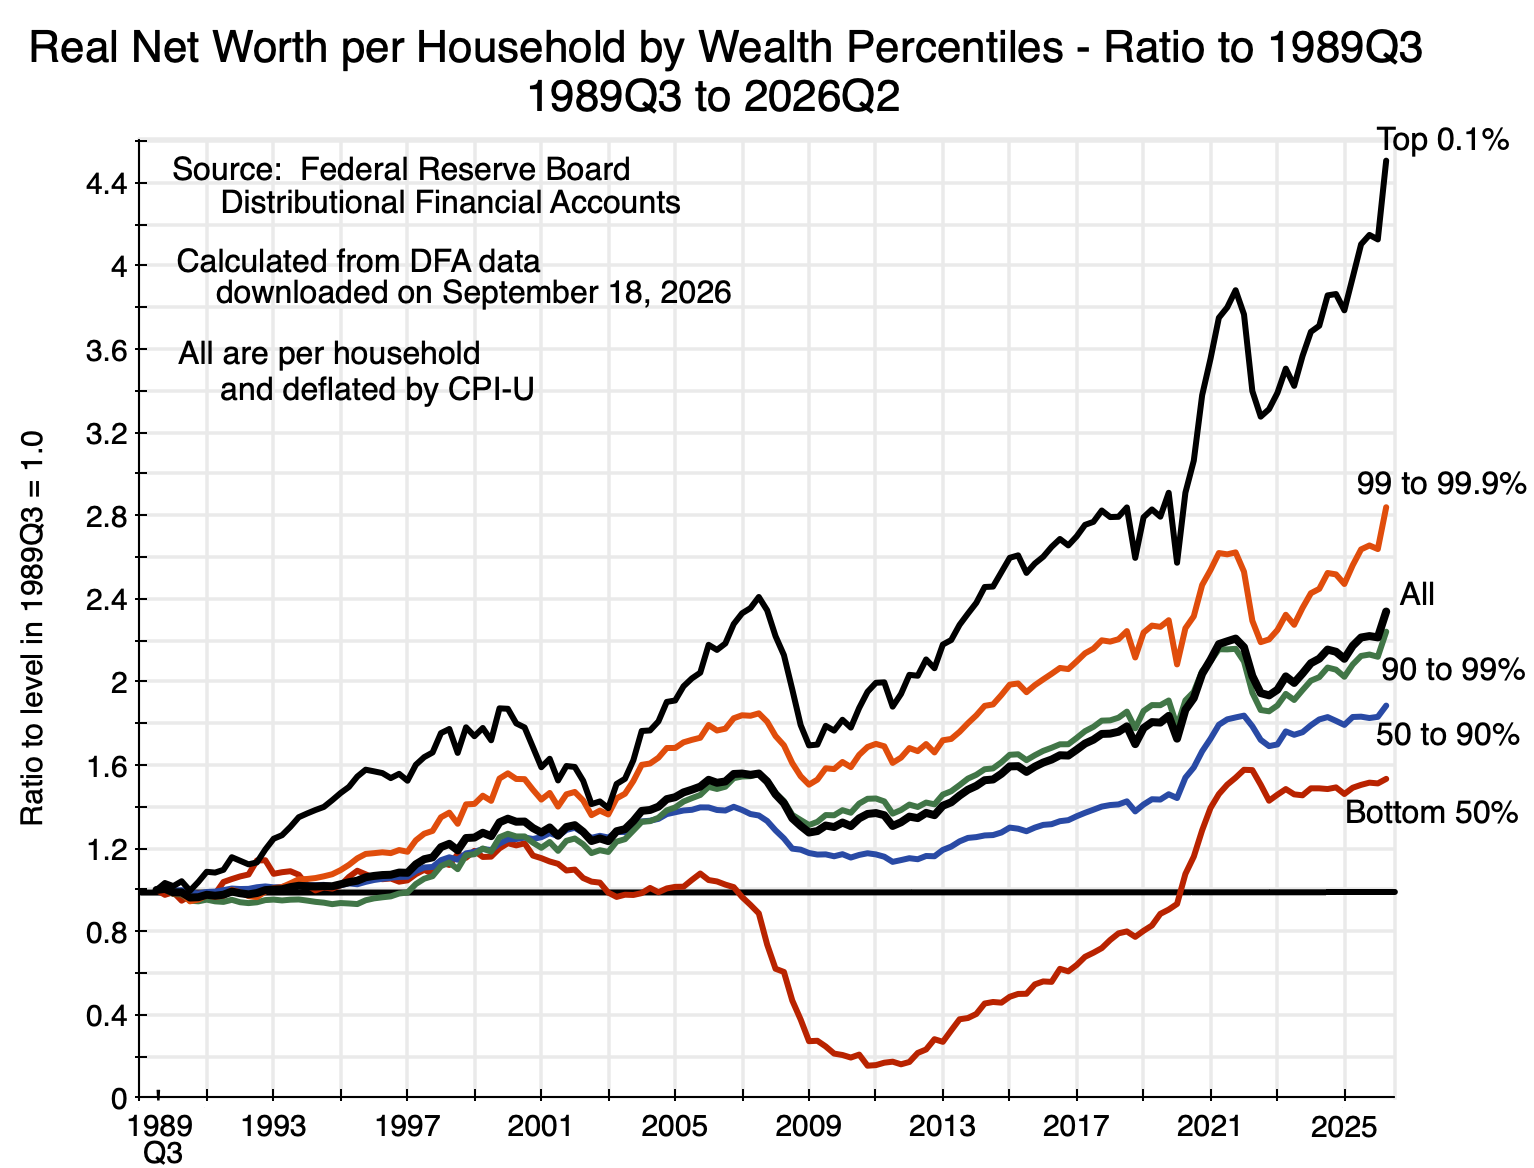
Chart 4

The real net worth per household of the top 0.1% at the end of 2026Q2 grew to be 4.5 times what it was at the end of 1989Q3.  That of those in the 99.0 to 99.9% stratum was 2.8 times as high.  And so on to the bottom 50%, where it was 1.53 times as high.  The wealthier the group to start, the greater the growth in their wealth over the period.

There was no necessity for this.  Indeed, until around 2005, there were times when the relative growth in the net worth of less wealthy groups grew by more than that of some of the more wealthy groups.  But over extended periods, they did not.

But it is also not terribly surprising.  The more affluent can invest in riskier assets, and over extended periods such assets will generally achieve a higher rate of return.  The returns on riskier assets are subject to greater volatility, but over time their higher growth will win out.  This is aside from advantages the wealthy can engineer for themselves through their advantageous capacity to intervene in political processes and decision-making.

E.  Decomposing the Growth in Overall Wealth

The average real value of wealth per household in the US as a whole has gone up substantially over this time period.  It is shown as the thick line in black in Chart 4, and is – as one would expect – in the middle of the increases recorded for the various groups.  Overall net worth (in real terms and per household) in 2026Q2 was 2.34 times higher than what it was in 1989Q3.

What accounts for this?  To start, GDP has grown, but as we will see, the value of wealth has grown by far more.  Breaking this down, the rise has been due to a combination of real GDP growth, an increase in the share of GDP going to earnings on assets (profits), and a higher valuation multiple being placed on those earnings.

To start, profits grew as a share of GDP while the share of wages fell:
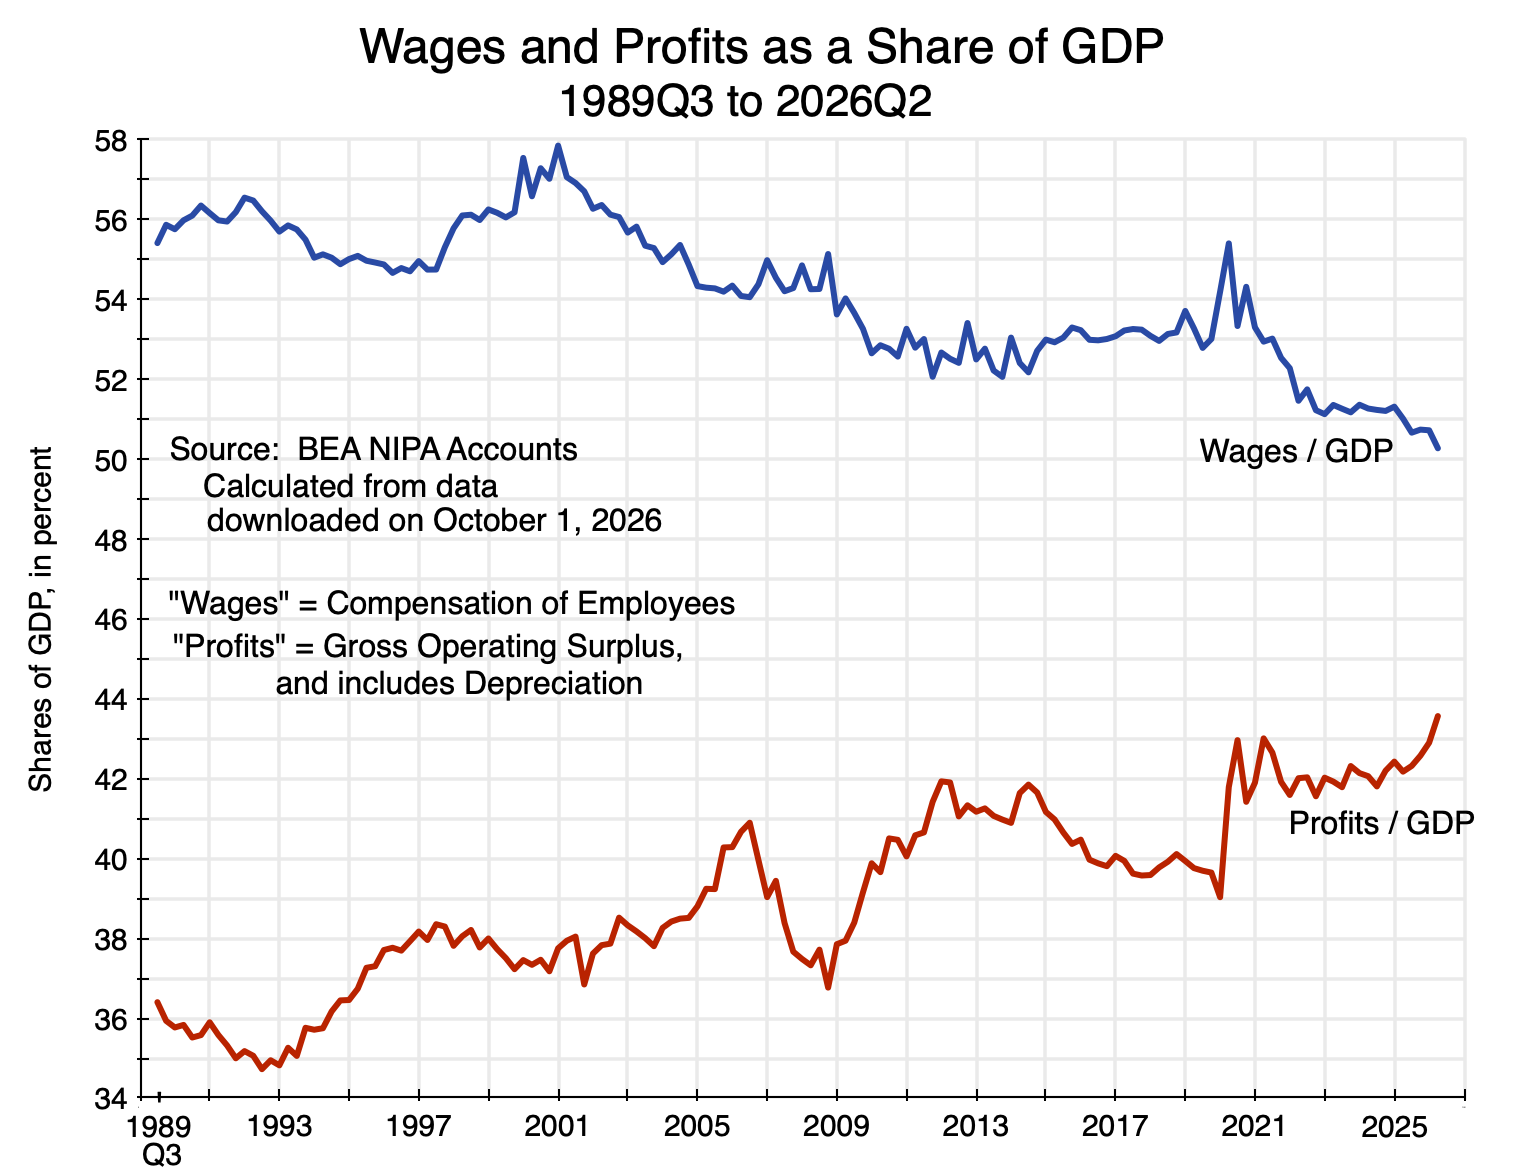
Chart 5

Gross profits (i.e. including depreciation allowances) rose from 36.4% of Gross Domestic Product as of the end of 1989Q2 to 43.6% as of the end of 2026Q2 – an increase (relative to the 36.4% share at the start) of almost 20%.  The share paid to employees (wages) fell from 55.4% of GDP to 50.3%.  As lower income groups are more dependent on wages for their income rather than profits, that fall in the wage share is significant.

[Side note:  The shares of wages plus profits in the chart do not add up to 100% of GDP.  The difference primarily reflects indirect taxes (such as excise taxes on fuels and tobacco, tariffs on imports, state and local property taxes, and more).  Indirect taxes are not counted as being paid out of wages or profits (direct income taxes are), and hence constitute a third category of income in the National Income and Product Accounts.  Those taxes have totaled a steady 6 to 7% of GDP throughout this period (except for a short period in 2020-2021 when they fell with the fall in spending due to Covid), and hence do not affect the trends seen for the wage and profit shares.

There will also be variation in the “statistical discrepancy” – the name the BEA uses for the difference between the estimated values of Gross Domestic Product (GDP) and Gross Domestic Income (GDI).  GDP and GDI should in principle be identical, as the value of all that is produced (GDP) will be someone’s income (GDI).  The statistical discrepancy is small – less than +/- 2% of GDP – but varies over time.  Wages, profits, and indirect taxes are estimated in the GDI accounts, and will sum to 100% of GDI.  But they are expressed here as shares of GDP, which, while close, will not sum to 100% of GDP due to the statistical discrepancy.]

A “valuation multiple” can next be defined as the ratio of wealth (i.e. net worth) for the country as a whole to the profits being earned.  It is akin to a price/earnings ratio often used in valuation measures of equity.  The valuation multiple over this period also rose:
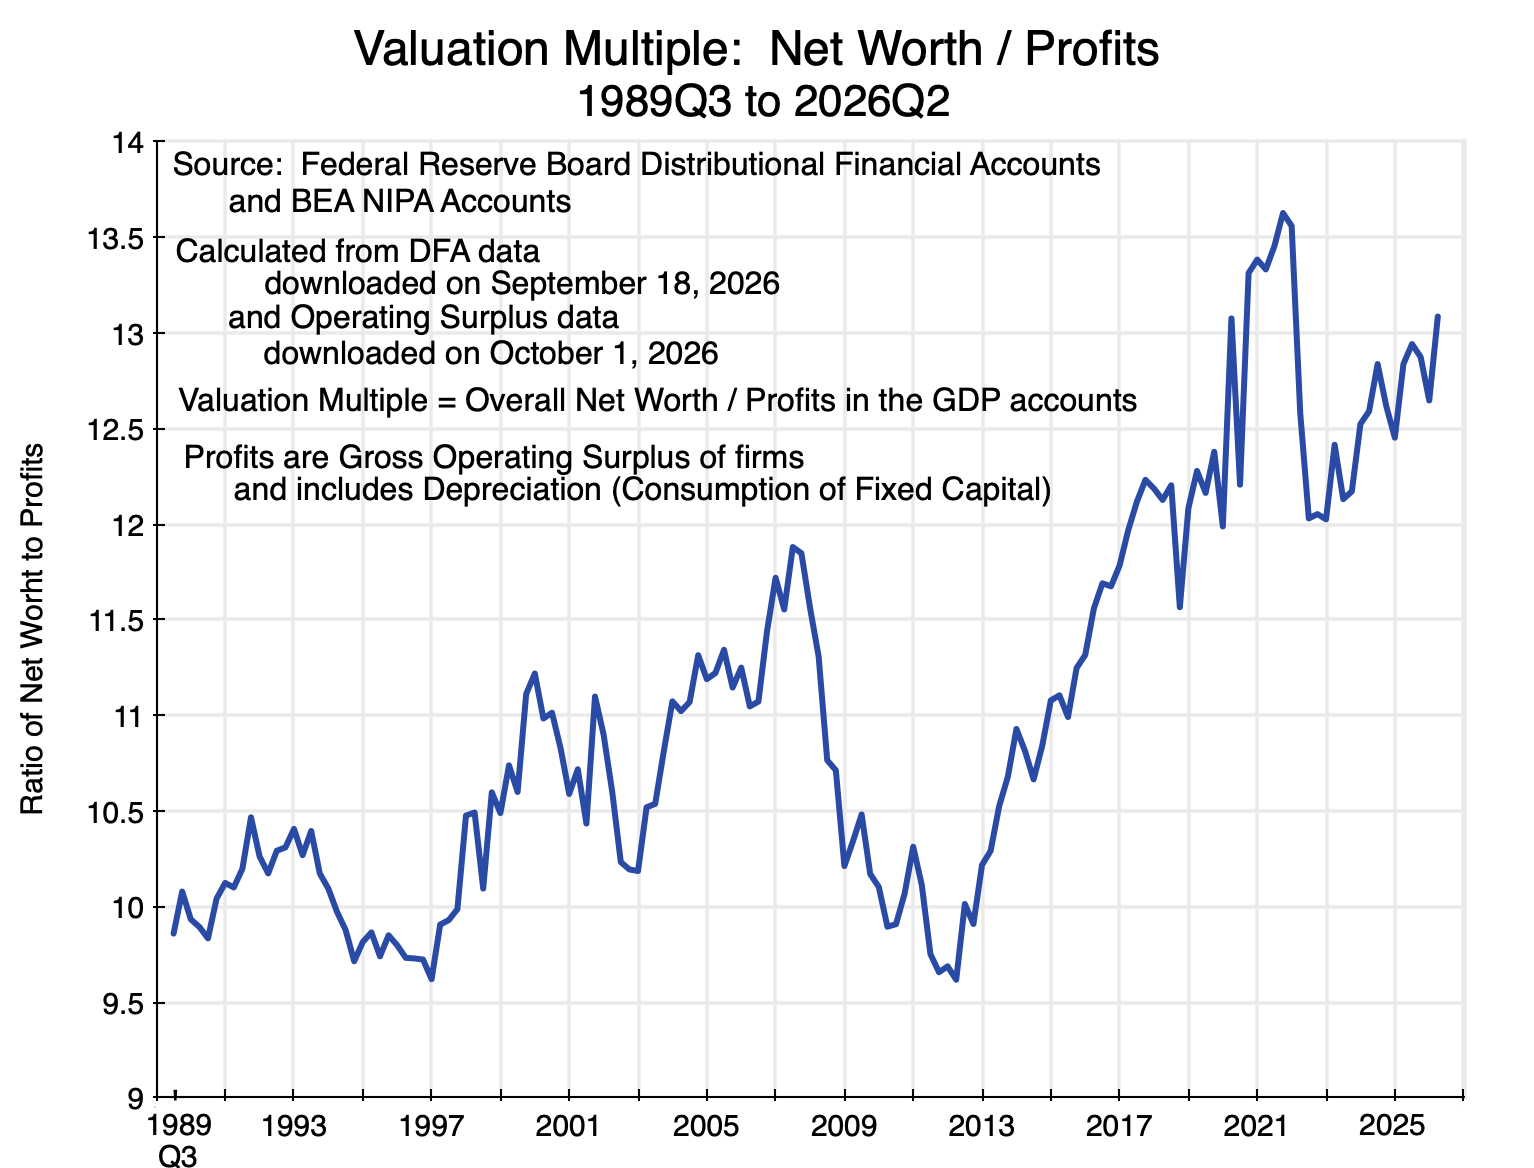
Chart 6

The valuation multiple rose from 9.9 in 1989Q3 to 13.1 in 2026Q2 – an increase of 33%.  But it fluctuated a lot.  It rose to 11.9 in 2007, fell to as low as 9.6 in 2012 following the economic and financial collapse of 2008/2009, and then rose again.  It reached 13.6 in the last quarter of 2021, fell to 12.0 in 2022Q3, and ended at 13.1.

An astute observer might note that the gross profits being assessed here (as a share of GDP in Chart 5, and then as the denominator in the ratio in Chart 6) are the overall profits in the economy.  The corresponding wealth being valued based on those profits is then the wealth held by households.  Will this coincide with the total wealth in the economy as a whole?  The answer is that it will be close, although not exact.  The Fed’s Financial Accounts of the United States (FA), discussed in Section B above, estimates that the aggregate wealth of the US economy as of the end of 2026Q2 was $181.0 trillion (Table S1.b). The Fed’s Distributional Financial Accounts (DFA) estimate the aggregate wealth of households as of the end of 2026Q2 was $185.7 trillion.

These are close to each other but not the same for several reasons.  One is that some of the estimation methods and definitions are different in the DFA accounts than those in the FA accounts, as discussed in Section B above.  But they are close because the ownership of most assets and liabilities is ultimately attributed to households in the DFA.  Households may hold assets directly (such as homes), or via their ownership of equity in both corporate and non-corporate businesses, or their ownership of financial assets (e.g. deposits in banks, or direct ownership of bonds).  These account for most assets in the economy.

The main exception will be government assets – including federal, state, and local government assets.  These totaled $23.1 trillion as of the end of 2026Q2 in the FA accounts.  But largely offsetting this is the net claims on US assets by foreign entities.  These totalled $20.7 trillion, leaving a small net difference.  Coupled with definitional and estimation differences, the total net worth of all US households is reasonably close to the net assets of the economy as a whole and adequate for the purposes here.

Putting this together:  GDP per household rose in real terms, profits rose as a share of GDP, and the valuation multiple assigned to those profits also rose:
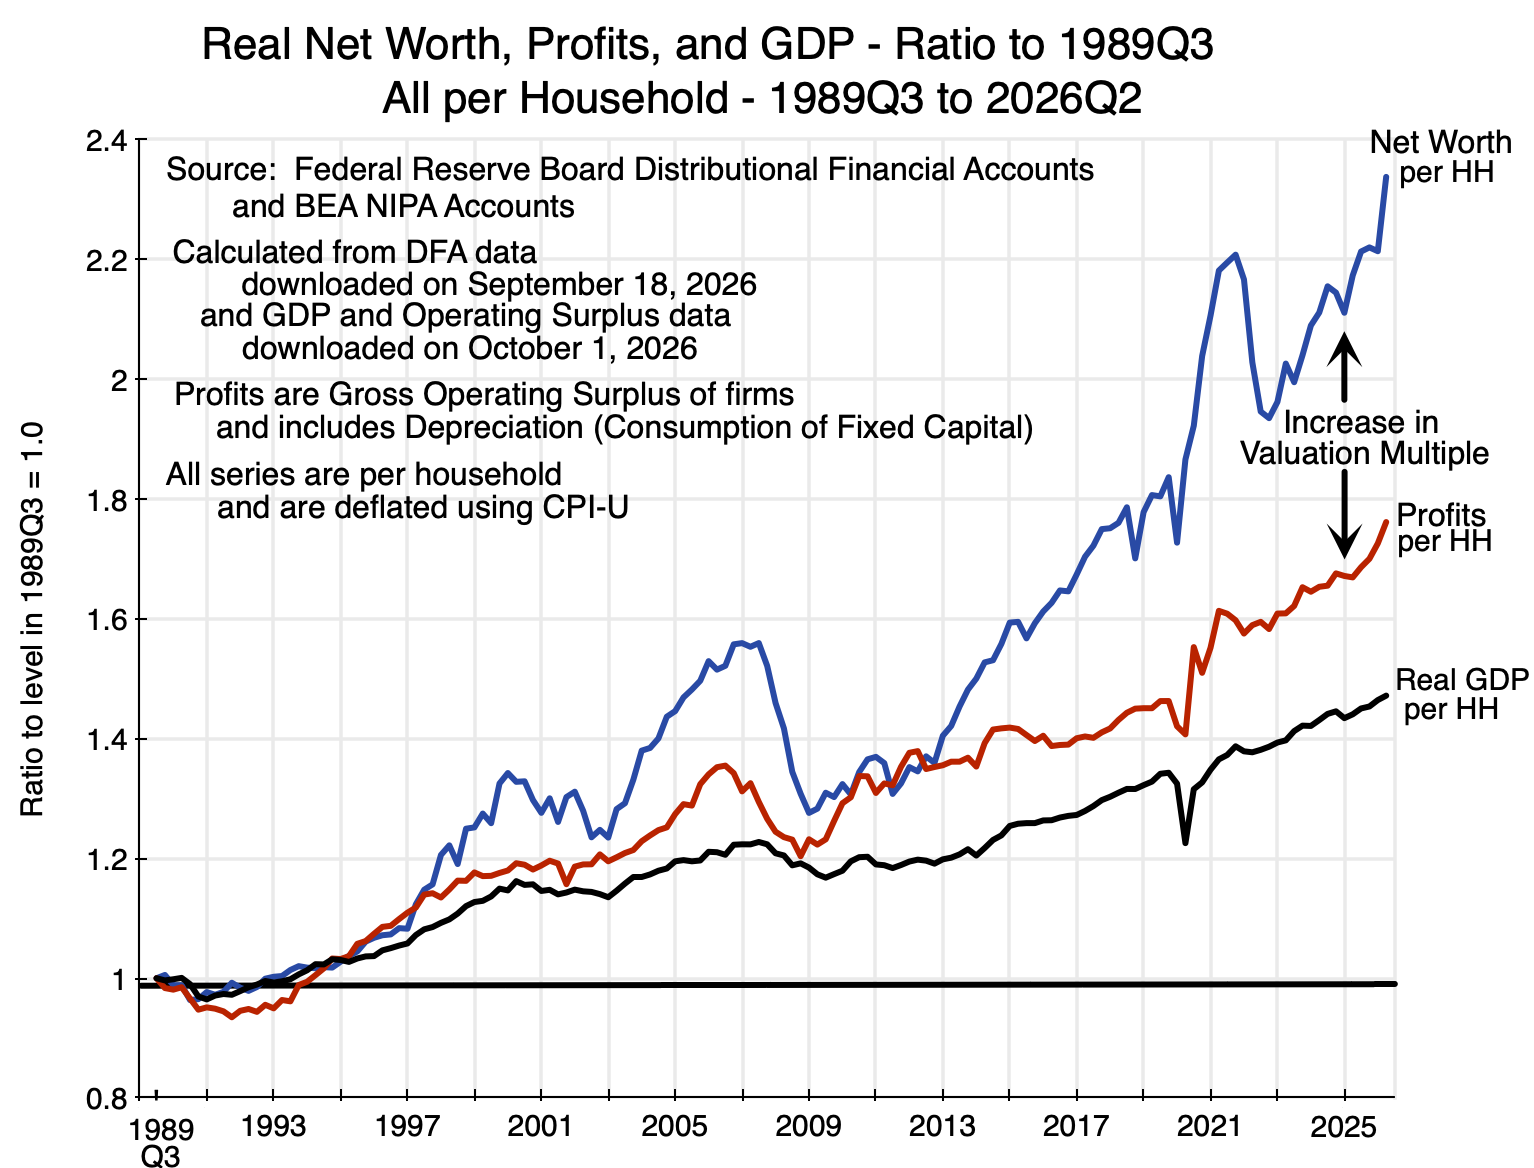
Chart 7

Putting numbers on this, real GDP per household rose by 47.2% over the period, profits as a share of GDP rose by 19.7%, and the valuation multiple rose by 32.7%.  Multiplying this out, the result is:  1.472 x 1.197 x 1.327 = 2.338.  That is, as of 2026Q2, overall real net worth per household rose to 2.338 times what it was in 1989Q3.  That corresponds to the line in blue in Chart 7, as well as the identical line for households as a whole in Chart 4 above (the thick black line).

Decomposed in this way, one sees that the increase in real GDP per household was the largest single factor behind the increase in overall wealth (with its increase of 47.2%).  The economy is producing more now than before.  The increase in the valuation multiple (by 32.7%) was the second most important factor.  Higher valuations are being assigned to assets for any given level of current profits.  And these were then amplified by profits growing as a share of GDP (by 19.7%).  All three were significant, and together led to wealth that is now valued at 2.338 times (i.e. 133.8% higher than) what it was in 1989Q3.

In stable conditions, one would expect wealth to grow in line with the growth in GDP.  But it increased by substantially more over the past 37 years because an increasing share of the income being generated in the economy (GDP) is going to profits rather than wages, and because the value being placed on the assets for a given level of profits (the valuation multiple) has also increased.  Together, they led to an increase in the value placed on that wealth for any given level of GDP by almost 59% (since 1.197 x 1.327 = 1.588).  A good question is why, but that is a topic for a separate discussion.

F.  Conclusion

Overall real wealth per household has grown significantly over the almost 37 years covered by this data series.  Adjusting for inflation using the CPI, it is now 2.338 times what it was at the start in 1989Q3.

But its distribution is highly skewed.  Ranking households by their net worth, the average net worth of the bottom 50% of households was an estimated $63,300 as of 2026Q2.  The average in the 50 to 90% group was an estimated $988,200.  In contrast, the average net worth of the top 0.1% was an estimated $203.7 million, and that in the 99.0 to 99.9% range was $26.7 million.

The disparities were already huge in 1989Q3 – the earliest period in this data series.  But those disparities then grew, with the estimated real net worth per household of the top 0.1% growing to 4.5 times what it was at the start, and that of the 99.0 to 99.9% growing to 2.8 times what it was at the start.  In contrast, while the real net worth per household of the bottom 50% grew, it grew to just 1.53 times what it was at the start.  It also fluctuated widely, and for 13 years (from 2007 to 2020) was less than what it was in 1989Q3.  This was primarily due to depressed values for their net real estate assets.  The value of those assets collapsed in 2007/08, remained depressed for several years, and recovered only slowly.  And real estate accounts for a high share of the net worth of the bottom 50%.

The purpose of this post has been to provide some of the basic figures on the distribution of wealth in the US and to describe how the underlying basic data were estimated by the Fed.  Future posts will examine other aspects of the distribution of wealth, including its distribution when groups are classified by income rather than their wealth holdings, and how wealth accumulation has changed across generations.  A final post will discuss what might be done to address these disparities.
More Evidence on the Damage Trump’s Policies are Doing to the Economy

Chart 1

A.  Introduction

On May 28, the Bureau of Economic Analysis (BEA) of the US Department of Commerce released its Second Estimate of GDP for the first quarter of 2026.  Along with it, it released its estimates of Personal Income and Outlays for April 2026.  Together, they provide further evidence on the damage that Trump and his misguided (as well as erratic) policies have done to the US economy.

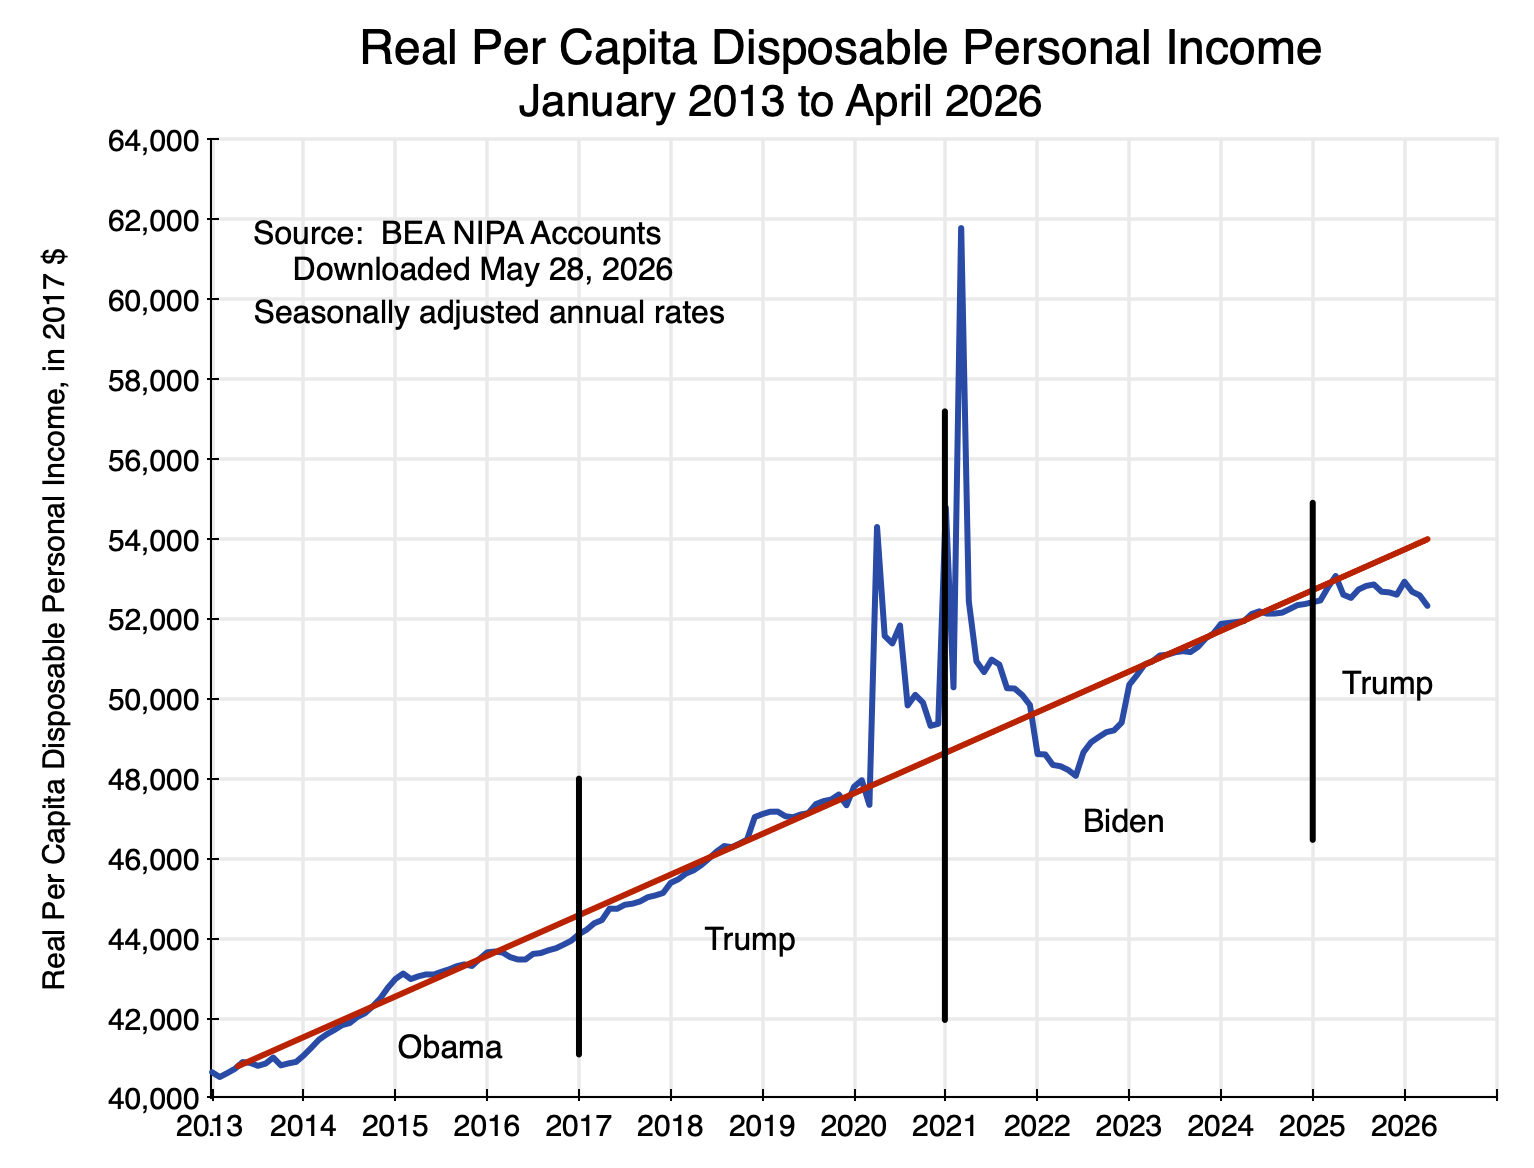
This note will review some of the figures that came out.  The chart above shows in a longer-term context what has happened to real per capita disposable personal income – perhaps the best measure in the GDP accounts of average real incomes of Americans.  It stagnated in the first year of Trump’s return to the presidency and is now falling in 2026.  It is also now well below what it would have been had it continued to follow the rising trend path of the last 13 years.  The figures will be discussed in the next section below, as well as figures on the divergent paths of what has happened to wages and salaries (stagnant in real terms) in contrast to corporate profits (up by 12.0% in the first quarter of 2026 over the year earlier in nominal terms, and by 8.7% in real terms).

The section that follows will then discuss a few points that can be found in the new GDP estimates.  GDP growth in the first quarter was weak, with a revised estimate that real GDP grew at a 1.6% annual rate in the quarter (down from 2.0% in BEA’s initial estimate released in April).  But this includes the effect of the return to normal levels for a full quarter of government production following the end of the federal government shutdown in the fourth quarter of 2025.  That recovery already happened in mid-November.  The previous post on this blog discussed that impact and how it is measured.  The bounce back to normal levels led to GDP as measured that was 0.6 percentage point higher in the first quarter than otherwise by my calculations (and 1.0 percentage point higher in figures cited by the BEA when discussing the negative impact of the shutdown in the fourth quarter).  Excluding this impact of government workers returning to their offices, GDP growth in the first quarter would have been only 1.0% (using the 0.6% figure) or just 0.6% (using the BEA figure).

Furthermore, more than all of this growth was a consequence of the AI boom.  The contribution to the growth in GDP in the first quarter from private investment in information processing equipment and software totaled 1.4 percentage points in the BEA figures.  That is, after taking into account the impact on measured GDP from government workers returning to their offices for the full quarter and private investments linked to the AI boom, production in the entire rest of the economy fell.  Production in the entire rest of the economy other than AI investments would have led to a fall in GDP at a rate of – 0.3% using the 0.6% figure for the impact of the government shutdown (or at a rate of – 0.7% using the 1.0% figure the BEA cited for the impact of the government shutdown).

On top of this, inflation is now high.  As discussed in Section D below, the upturn in inflation started already in late 2025 / early 2026, i.e. before Trump’s decision to start a war with Iran on February 28.  The resulting jump in fuel prices led to inflation being even higher.

The economy is doing poorly.  Living standards are falling.  Only investments linked to the AI boom are keeping GDP growth positive.

B.  The Impact on Living Standards

Per capita disposable personal income in real terms was stagnant in the first year of Trump’s second presidency and falling in 2026.  It is now well below where it would have been had it continued on the previous upward trend.  The figures are shown in the chart at the top of this post.

The BEA provides an estimate of personal income monthly, and it can be found with its underlying components in Table 2.6 of the NIPA Accounts.  Personal income includes all sources of income accruing to individuals, including from wages and salaries (along with supplements to wages, such as company contributions to health and pension plans), income from unincorporated businesses (sole proprietorships and partnerships – i.e. most small businesses), rental incomes accruing to persons, personal interest income and dividend income, and current transfer receipts (such as from Social Security and Medicare) net of taxes paid for such programs (e.g. Social Security and Medicare taxes).

Personal income minus personal taxes (primarily income taxes) will then be disposable personal income.  The BEA deflates these figures using its estimates of the personal consumption expenditures price index (often referred to – not quite correct technically, but close – as the PCE deflator) to put them in real terms, and divides them by current population levels (with estimates from the Census Bureau) to put them in per capita terms.

Per capita disposable personal income in real terms was close to its long-term trend in January 2025, as Trump took office, and continued close to that trend until April 2025.  But that was the month when Trump announced huge and essentially arbitrary tariffs would be charged on imports on almost every country and region in the world (including an island populated only by penguins and seals).  He called this “Liberation Day”.  Erratic changes in tariffs since then, as well as in other policies (such as the granting of special favors or special penalties to various firms depending on Trump’s whims), have since continued.  Real personal income then came down from its April 2025 peak, stagnated to the end of the year, and fell to just $52,330 in the BEA estimate for April 2026.  This is below where it was when Trump took office, and $750 below where it was in April 2025.  This is in 2017 prices.  In current prices and as of April 2026, real personal income (at an annual rate) is now $980 per person less than it was on “Liberation Day”.

But a more appropriate measure of performance would be relative to where it would have been had it continued to rise as it had under Biden and before.  Compared to what it would have been, the shortfall in living standards by April 2026 came to $1,700 per person in terms of 2017 prices, or $2,200 for every man, woman, and child in the country in current prices.  For a family of four, the reduction in living standards as of April 2026 was $8,800 at an annual rate.  This is not a small amount.  Households could make good use of the higher income they would have had, had it continued to grow as it had under Biden and before.

Furthermore, the gap between what it could have been and what it actually has been under Trump is widening over time.  It is also an average, and hence does not take into account the increases in inequality of recent years.  There has been much discussion of the so-called “K-shaped” economy, where higher-income individuals are doing increasingly well while lower-income individuals are doing poorly.  With growing inequality, the reduction in the overall average real personal incomes under Trump has been especially stark for the lower and middle income classes.

Defenders of Trump might well point out that there was also a substantial dip in real personal incomes in 2022 during the Biden administration.  This is true and is seen in the chart at the top of this post.  It was, however, temporary.  Real personal incomes returned to their previous growth path by the end of that year, and then continued on that path until Trump took office.  The dip was a consequence of the severe disruptions to the US (and indeed world) economy due to the sudden lockdowns due to Covid in 2020 that continued into 2021, and then the time needed to re-establish the regular functioning of supply chains once the production plants and transportation networks could be reopened.  The impact of this on disposable personal incomes in 2020 and 2021 was masked by the numerous (and massive) emergency government support programs under both Trump and Biden – as seen by the sharp upward spikes in personal incomes in those years.  Much of this was saved (stores were often still closed), and the drawdown on such savings could then support purchases in 2022 despite real incomes being temporarily low while supply chains were still not fully functioning.  Real personal income then rapidly recovered, and by late 2022 it was back to its prior trend.

Another indicator in the recently released BEA estimates of the increasing stress that American households are experiencing can be found in the estimates of the personal savings rate.  This is also provided in Table 2.6 of the NIPA accounts.  The personal savings rate is personal savings as a percentage of disposable personal income.  That rate has been falling during Trump’s second term to just 2.6% as of April 2026 – less than half the rate of 5.5% of April 2025.  It is also now well below its recent longer-term average.  Between January 2013 and February 2020 (before the Covid disruptions began), it varied between about 5% and as much as 8%, and averaged 5.9%.

The 2.6% rate is low, and the fact it has been falling is an indication that households are stressed.  Given urgent current needs, they are saving less for retirement and other future objectives.  As with personal income, the BEA can only estimate personal savings as an average over all households.  Thus the 2.6% rate is an average that includes both upper income households who are likely saving a relatively high share of their income and lower and middle income households, who may not now be saving much at all.

At the same time as personal income has been falling, corporate profits have been rising at a fast rate.  The BEA estimates corporate profits only on a quarterly basis, and the initial estimates of these profits are released only with the release of the second estimates of the GDP accounts each quarter (as in the estimates released on May 28).  See specifically Table 6.16D in the NIPA Accounts.  Between the first quarter of 2025 and the first quarter of 2026, corporate profits in all industries rose by 12.0% in nominal terms.  Using the PCE deflator to put this in real terms, the increase was 8.7%.  In contrast, wages and salaries rose by just 3.5% in nominal terms between those two quarters, or 0.4% in real terms using the PCE deflator.  Adjusting also for population growth, the increase was essentially zero (less than 0.1%).

Corporate profits have been going up, and at a rapid pace.  Wages have not.

C.  The Growth in GDP in the First Quarter of 2026

The BEA’s estimate of GDP growth in the first quarter of 2026 was revised down from 2.0% (at an annual rate) in the BEA’s initial (“Advance”) estimate released on April 30 to 1.6% in the Second Estimate released on May 28.  But as noted above, this 1.6% rate includes the impact of the bounce-back to normal levels of federal government production of services for a full calendar quarter.  It had been curtailed during the shutdown that spanned almost one-half of the fourth quarter of 2025, and GDP measures the flow of goods and services provided over a full quarter.  Taking this effect into account, growth in the first quarter of 2026 was even less.

The impact of the government shutdown was discussed in the previous post on this blog.  GDP is the sum total of a flow of goods produced and services provided during a period of time (a calendar quarter here), and the reduction in the provision of those government services in the first half of that quarter meant a reduction in GDP in the quarter.  As discussed in that blog post, the impact (by my calculations from the figures the BEA provided) reduced measured GDP by about 0.6 percentage points (at an annual rate) below what it otherwise would have been.  The BEA, in commentary it provided with its releases of the GDP estimates for the fourth quarter of 2025, indicated the impact was about 1.0 percentage point of GDP.  The reason for the discrepancy is not clear, but one guess would be that some higher official at the BEA or the Department of Commerce took the 0.6% figure and rounded it to 1%, and that someone else started to write this as 1.0%.

With either figure, GDP in the fourth quarter of 2025 was reduced by some amount.  By simple arithmetic, there would then be a bounce-back effect on GDP in the first quarter of 2026 of a similar magnitude, as the government returned to normal operations for the full quarter.  Taking this into account, the rate of growth in GDP in the quarter other than from this return to normal government operations would have been 1.0% rather than the 1.6% reported (or 0.6% rather than 1.6% based on the 1.0% figure for the impact of the shutdown that the BEA cited).

But in addition, GDP growth – such as it was – is more than fully accounted for by the continuing boom in private investments linked to building the data centers, developing the software, and supplying the other equipment needed for the new artificial intelligence (AI) systems.  This AI boom accounts for much of the growth in GDP in 2025, with this continuing into 2026.

While the NIPA sector categories will not match precisely the investments related to the AI boom, a reasonable approximation is the sum of private investments in information processing equipment and in software.  The NIPA accounts provide figures for private investment in these categories, and from this the BEA provides figures (in Table 1.5.2 of the NIPA accounts) of the contribution from the growth of each to the overall growth in real GDP.  For technical reasons (the use of chain-weighted price indices), the sum of the individual contributions to the growth in GDP may differ slightly from the estimated growth in real GDP, but they are well close enough for the purposes here.  Of greater importance is that investments in information processing equipment and in software will be for more than that just for AI, plus there will be AI-linked investments in other categories as well.  These will in part offset each other.

What is clear is that in 2025 and continuing into 2026, there has been a major increase in private investment in these AI-related categories.  Their contribution to the growth in GDP in the BEA calculations (Table 1.5.2 in the NIPA accounts) was an average of a 0.90% point contribution to the GDP growth rate each quarter (at annual rates).  This is triple the average contribution to GDP growth of investments in information processing equipment and in software between the first quarter of 2013 and the last quarter of 2024, when its contribution was on average 0.30% point.

Subtracting from overall GDP growth the contribution of the AI boom, as well as accounting for the impact of the federal government shutdown, yields the contribution to the growth in GDP of the entire rest of the economy:

Contributions to GDP Growth

GDP Growth Contribution of      Info Processing                   + Software Impact of Gov’t Shutdown Contribution of All Else
2025Q1  -0.65%        1.30%     -1.95%
2025Q2   3.84%        0.80%      3.04%
2025Q3   4.38%        0.26%      4.12%
2025Q4   0.48%        0.78%   -0.57%      0.27%
2026Q1   1.62%        1.36%    0.56%     -0.31%

Seasonally adjusted annual rates.

(The figures for the impact of the federal government shutdown (-0.57% of GDP and +0.56% of GDP) have been rounded in the text to 0.6%, and are shown here at two digits of accuracy to be consistent with the rest of the table.  Also, they differ very slightly between the two quarters – 0.57% vs. 0.56% – as the impact is taken as a share of GDP, and GDP is slightly higher in the first quarter of 2026 than what it was in the fourth quarter of 2025.)

Taking into account the impact of the government shutdown and of the boom in AI investments, growth in the rest of the economy was essentially zero over the past half year.  It was relatively high in the second and third quarters of 2025, but was substantially negative in the first quarter.  While the quarter to quarter figures will bounce around (due both to real changes and to statistical noise), the economy – other than for investments related to AI – is clearly weak.  This is consistent with the findings discussed above on the stagnation in real personal incomes in 2025 and its fall in 2026.

Another sign of weakness in the US economy has been a continued decline in private investment in business structures (e.g. office buildings, commercial structures, warehouses) and in residential housing.  See Table 1.1.1 of the NIPA accounts.  Each has declined in real terms in every quarter since Trump took office at the start of 2025, most recently with real investment in business structures falling at an annual rate of 5.4% in the first quarter of 2026 and real investment in residential housing falling at a 6.2% rate in the quarter.  Other than for AI, private investors are wary of committing to investments in the economy.

A proviso on the AI investments should, however, be noted.  The figures above are based on the BEA calculations of what it terms the “contributions to the percent change in real gross domestic product”.  It is, however, a calculation from the demand side measure of GDP, where all the components of demand for GDP (private consumption, private investment, government, and exports less imports) are added up.  This provides an estimate of domestic production during the period, as private investment includes investment in inventory accumulation and changes in inventories act as a balancing item.  Increases in imports are therefore a negative contribution to the growth in GDP in this framework, and the BEA is only able to make an estimate of the change in total imports during the period – not imports that in some way both directly and indirectly provided part of the supply to fill a specific demand.

With imports equal to only about 14% of GDP, the approach is not unreasonable, as 88% of what is used to fulfill the various demands will come from domestic production.  (With imports at 14% of GDP, total supply will be 100 + 14 = 114, and the share domestically supplied will be 100 / 114 = 88%.)

But while the average import share in total supply is 12% ( = 14 / 114), the share is likely substantially higher for the investments linked to the AI boom.  How much higher is not clear.  Many of the semiconductor chips and much of the specialized equipment are imported, but the investments in the data centers supporting AI and in the software used for this will be more than just imports.  The data centers need to be built, the equipment put together, and the centers then connected to power, water, and information networks.  And the software, in contrast to the chips, is primarily from domestic production.

The relatively high share that is imported will matter for the impact such AI investments will have on domestic production rather than direct imports, and GDP is a measure of domestic production.  It is impossible to say how much that impact will be, but it will reduce the “contribution” of such investments to the growth in GDP (as depicted in the table above).  However, even with this, the contribution of the “all else” category to the growth in GDP is likely still to be small – just not as small as the figures indicate.

D.  Inflation is Now High

Inflation is now also a concern.  Table 2.8.4 of the NIPA accounts provides monthly estimates of the price indices estimated by the BEA for personal consumption expenditures – both overall and for the major types of products making up personal consumption.  (Technically these are price indices rather than price deflators, but in practice they are almost always the same within round-off and the terms – price indices or deflators – are often used interchangeably.)  The Fed uses the core PCE deflator (the deflator excluding food and energy) as the primary indicator of inflation that it focuses on, with the objective of keeping it at around 2.0% on an annualized basis.

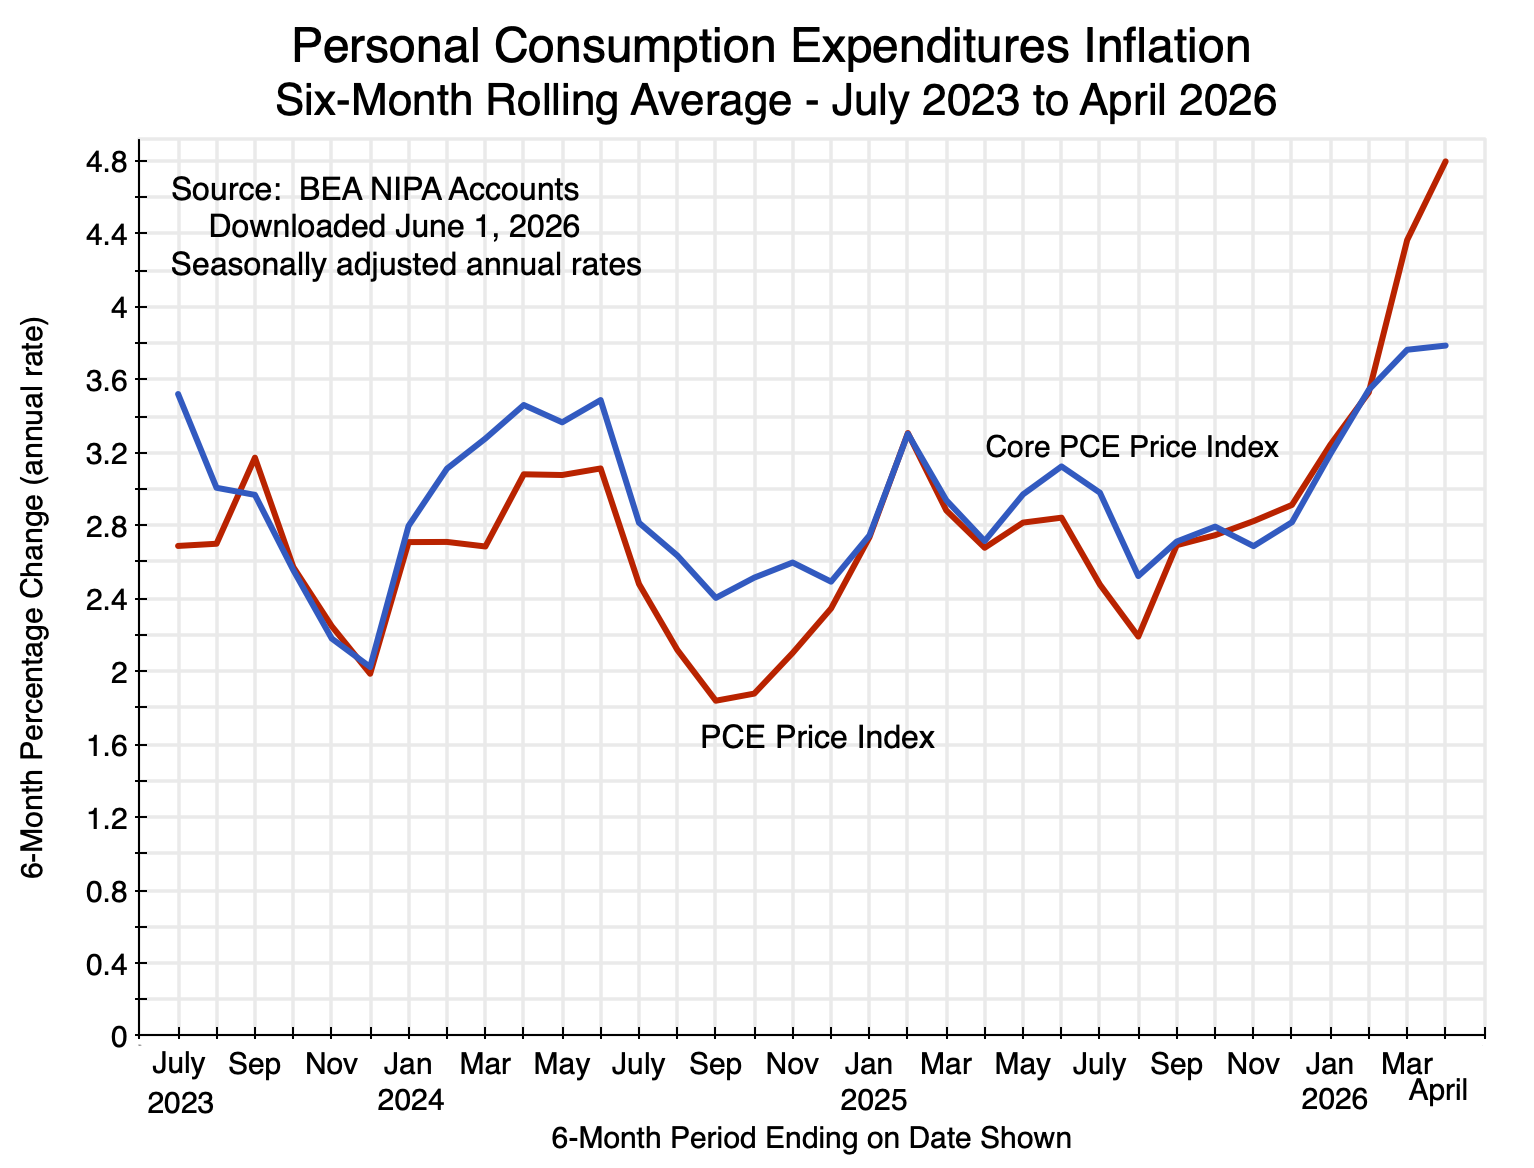
Monthly changes in the price indices are volatile and often not meaningful, while changes in the indices over year-earlier periods will miss turning points due to the long lag.  Changes over six-month periods are usually a good compromise to show when a turning point has been reached.  And it is clear from this that inflation turned decidedly higher in late 2025 / early 2026:

Chart 2

The overall PCE price index over the six months ending in April 2026 rose at a 4.8% annualized rate.  The core PCE price index rose at a 3.8% pace.  Both of these are now far above the Fed’s 2.0% goal.  And this is not just due to energy prices:  By April, the six-month core PCE price index had risen by a full percentage point from the 2.8% rate of the six-month periods ending in late 2025.  Furthermore, energy prices in the months of January and February 2026 were in fact relatively low and below their levels of the last several months of 2025.  Trump did not launch his war against Iran until February 28, after which energy prices skyrocketed.  This then compounded what was already becoming an inflation problem.

Inflation by itself will not necessarily lead to a reduction in average real personal incomes in the NIPA accounts – the topic of Section B above.  Higher prices mean that the loss of one party is a gain to another.  And the stagnation in real personal incomes began in 2025 well before the recent jump in inflation.  But to the extent the inflated prices end up benefiting corporate entities (such as the big oil companies), average real personal incomes will be reduced as corporate profits go up.  This has likely been an additional factor in the more recent fall in 2026 in the absolute levels of average real personal incomes.

The recent rise in inflation does not in itself account for the slump in living standards under Trump.  The stagnation in real personal incomes was already underway in 2025.  Trump’s misguided policies led to that.  High inflation is now compounding those difficulties.

E.  Conclusion

There is another figure in the recently released NIPA accounts that is of interest as an indicator of what has happened to the living standards of lower-income Americans.  It has in fact had a positive contribution to GDP as mechanically measured.  Included within the goods and services that add up to overall personal consumption expenditures, the BEA has the category labelled “Final consumption expenditures of nonprofit institutions serving households (NPISHs)”.  These are the net expenditures of nonprofit groups serving lower-income households, such as food banks, health clinics, and other providers of similar services.  The “net” is net of any payments they receive from those receiving those services.  Table 2.8.11 in the NIPA accounts shows the percentage change in real expenditures on this consumption category over the same month one year before.

The net consumption of these goods and services provided through nonprofits was 10.6% higher in real terms in April 2026 than what it was in April 2025.  This is major growth (and a contribution to GDP as measured), and is the highest percentage increase since 2022 (when the disruptions of the Covid crisis were being finally resolved).  This need to resort to food banks and other services provided through non-profits is another indication that lower-income households are stressed in this economy, and need to find support somewhere.

This indicator of stress among American households is consistent with the stagnation – and more recent decline – in real personal incomes shown in the chart at the top of this post.  It is also consistent with the fall in the average personal savings to just 2.6% – half of what it was when Trump took office.  When times are difficult, households set aside their savings plans.  It is also consistent with slow growth in GDP outside of investments in the booming AI sector.  And it is consistent with the more recent rise in inflation – affecting some households more than others – where the inflation rate was already going up before Trump chose to bomb Iran and drove up the price of fuels.

Trump’s policies are doing real damage to the economy and to living standards, that are evident in data that cover only a little over a year since he took office in his second term.  But there is no indication that Trump recognizes this and that he intends to change what he has been doing.

The Performance of the Stock Market During Trump’s Term in Office: Not So Special

A.  Introduction

Stock market performance is often taken to be a good measure of how the economy as a whole is performing.  But it is not.  For most Americans it is simply irrelevant, as the overwhelming share of investments in the stock markets are held by only a small segment of the population (the wealthy).  And its track record as a broader indicator of how the economy is performing is imperfect at best.

Still, many do focus on stock market returns, and Trump brags that the performance of the market during his term in office has been spectacular.

That is not the case.  This post will look at how the stock market has performed during Trump’s term in office thus far, and compare it to what that performance was under presidents going back to Reagan up to the same point in their terms.

First, however, we will briefly discuss to what extent one should expect stock market prices to reflect actions a president might be taking.  And the answer is some, but there is much more going on.

B.  Presidential Policies and the Stock Market

Owning shares of a firm entitles the owner to a share of the profits generated by that firm, both now and into the future.  And while there are many complications, a simple metric commonly used to assess the price of a share in a firm, is the price/earnings ratio.  If earnings (profits) go up, now and into the future, then for a given price/earnings ratio the price of the stock would go up in proportion.

Economic policies affect profits.  And in a thriving economy, profits will also be rising.  The policies of a presidential administration will affect this, and although the link is far from a tight one (with important lags as well), policies that are good for the economy as a whole will generally also lead to a rising stock market.

But there is also a more specific link to policy.  What accrues to the shareholders are not overall profits, but profits after taxes.  And this changed significantly as a result of the new tax law pushed through Congress by Trump and the Republicans in December 2017.  It resulted in the effective corporate profits (income) tax being cut by more than half:

This chart is an update of one prepared for an earlier post on this blog (where one can see a further discussion of what lies behind it).  It shows corporate profit taxes at the federal level as a share of corporate profits (calculated from figures in the national income accounts issued by the BEA).  While Trump and the Republicans in Congress asserted the 2017 tax bill would not lead to lower corporate profit taxes being paid (as loopholes would be closed, they asserted), in fact they did.  And dramatically so, with the effective corporate tax rate being slashed by more than half –  from around 15 to 16% prior to 2017, to just 7% or so since the beginning of 2018 (and to just 6.3% most recently).

This cut therefore led to a significant increase in after-tax profits for any given level of before-tax profits, which has accrued to the shareholders.  Note that this would not be due to the corporations becoming more productive or efficient, but rather simply from taxing profits less and shifting the tax burden then on to others (i.e. a redistributive effect).  And based on a reduction in the taxes from 16% of corporate profits to 7%, after-tax profits would have gone from 84% of profits to 93%, an increase of about 11%.  For any given price/earnings ratio, one would then expect stock prices, for this reason alone, to have gone up by about 11%.

[Side note:  Technically one should include in this calculation also the impact of taxes on profits by other government entities – primarily those of state and local governments.  These have been flat at around 3 1/2% of profits, on average.  With these taxes included, after-tax profits rose from 80 1/2% of before-tax profits to 89 1/2%, an increase that is still 11% within round-off.]

One should therefore expect that stock prices following this tax cut (or in anticipation of it) would have been bumped up by an additional 11% above what they otherwise would have been.  Other things equal, the performance of the stock market under Trump should have looked especially good as a result of the shift in taxes away from corporations onto others.  But what has in fact happened?

C.  Trump vs. Obama

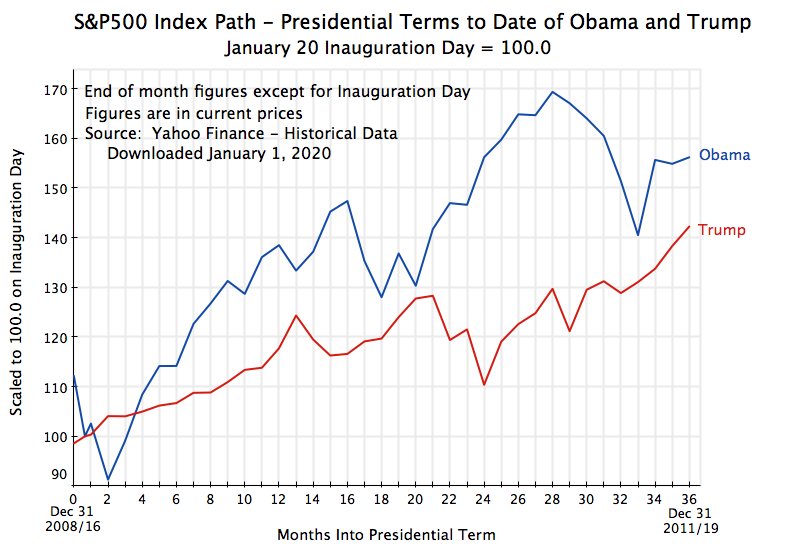
The chart at the top of this post compares the performance of the stock market during Trump’s term in office thus far (through December 31, 2019) to that under Obama to the same point in his first term in office.  The difference is clear.  Other than during Obama’s first few months in office, when he inherited from George W. Bush an economy in freefall, stock market performance under Obama was always better than it has been under Trump.  Even after slashing corporate profit taxes by more than half, the stock market under Trump did not do exceptionally well.

The S&P500 Index is being used as the measure of the US stock market.  Most professionals use this index as the best indicator of overall stock market performance, as it is comprehensive and broad (covering the 500 largest US companies as measured by stock market value, with the companies weighted in the index based on their market valuations).  The data were downloaded from Yahoo Finance, where it is conveniently available (with daily values for the index going back to 1927), but can be obtained from a number of sources.  The chart shows end-of-month figures, starting from December 31 of the month before inauguration, and going through to December 31 of their third year in office.  The index is scaled to 100.0 on exactly January 20 (with this presented as “month” 0.65).

So if one wants to claim “bragging rights” for which president saw a better stock market performance, Obama wins over Trump, at least so far in their respective terms.

D.  Trump vs. All Presidents Since Reagan

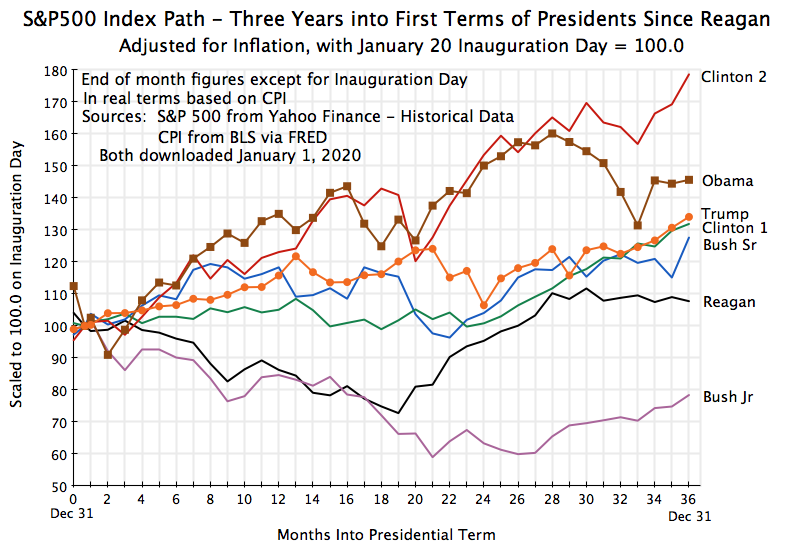
A comparison to just one president is limited.  How does the performance under Trump compare to that under other US presidents up to the same points in their terms in office?  Trump is roughly in the middle:

This chart tracks the performance under each president since Reagan up through the third year of their first terms in office.  I have adjusted here for inflation (using the CPI), as inflation was substantially higher during the Reagan and Bush Sr. terms in office than it has been since.  (I left the chart at the top of this post of just Obama vs. Trump in nominal terms as inflation in recent years has been steady and low.  But for those interested in the impact of this, one can see the Obama and Trump numbers in real terms in the current chart.)  I have included in this chart only the first terms of each president (with one exception) as the chart is already cluttered and was even more so when I had all the presidential terms.

The exception is that I included for perspective the stock market performance during Clinton’s second term in office.  The stock market rose over that period by close to 80% in real terms, which was substantially higher than under any other president since at least before Reagan in either their first or second terms.  The performance in Obama’s first term (of 146% in real terms) was the second-highest.  There was then a set of cases which, at the three-year mark, showed surprising uniformity in performance, with increases of between 32% and 34% in the second Reagan term, the first Clinton term, the second Obama term, and Trump’s term so far.  Bush Sr. was not far behind this set with an increase of 28%.

The worst performances were under Bush Jr. ( a fall of 22% to the third-year point in his first term), and Reagan (an increase of just 8% to that point in his first term).

So the performance of the market under Trump is in the middle – not the worst, but well below the best.

E.  Single Year Increases in the S&P500 from 1946 to 2019

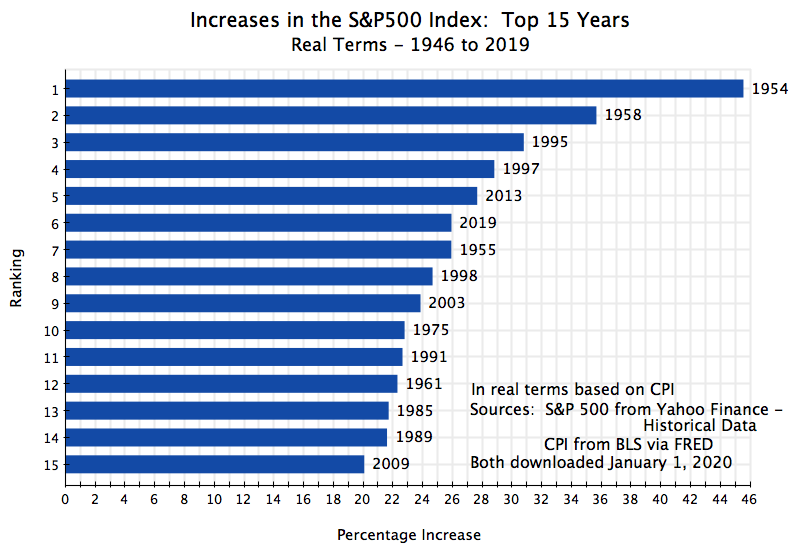
Finally, was the increase under Trump in his best single year so far (2019) a record?  No, it was not.  Looking at the single year performances (in real terms) since 1946, the top 15 were:

The increase in 2019, of 25.9%, was good, but only the sixth-highest of the 74 years between 1946 and 2019 (inclusive).  The stock market rose by more in 2013 during Obama’s term in office (by 27.7%), and in 1997 (28.8%) and 1995 (30.8%) which were both Clinton years.  And the highest increases were in 1958 (35.7%) and 1954 (45.6%) when Eisenhower was president.

The market also rose substantially in 2017, in Trump’s first year in office, by 16.9%.  But it then fell by 8.0% in 2018, in Trump’s second year in office.  Overall, the average rank (out of the 74 years from 1946 to 2019) of the individual year performances over the three years Trump has been in office so far, would place Trump in the middle third.  Not the worst, but also far from the best.  And comparing the three-year average while Trump has been president to rolling three-year averages since 1946, Trump’s average (of 11.6%) is well below the best.  The highest was an average return of 25.3% in 1995-97 during Clinton’s term in office.  And the three-year average return was also higher at 16.7% in 2012-14 during Obama’s term.

F.  Summary and Conclusion

Trump likes to brag that the performance of the stock market during his term in office has been exceptional.  But despite a slashing of corporate profit taxes (which, other things being equal would be expected to increase stock prices by 11%), the performance of the market during Trump’s term in office would put him in the middle.  Specifically:

a)  The market rose by more during the first three years of Obama’s term in office than it has under Trump;

b)  Compared to the first three years in office of all presidents since Reagan (whether first terms only, or first and second terms) would place Trump in the middle.  Indeed, the increase under Trump so far was almost exactly the same as the increases seen (at the three-year point) in Obama’s second term, in Reagan’s second term, and in Clinton’s first term.  And the return under Trump was well below that seen in Obama’s first term, and especially far below that in Clinton’s second term.

c)  The individual year performances during Trump’s three years have also not been exceptional.  While the performance in 2019 was good, it was below that of a number of other years since World War II, and below that of individual years during Obama’s and Clinton’s terms in office.

But as noted at the start of this post, stock market returns should not be over-emphasized.  An increase in the stock market does little for those who do not have the wealth to have substantial holdings in the stock market, and as a broader indicator of how the overall economy is performing, stock market returns are imperfect at best.

Still, one should be accurate in one’s claims.  And as on many things, Trump has not been.