GDP Growth is Strong – Perhaps Too Strong

A.  Introduction

On April 25, the Bureau of Economic Analysis released its initial estimates of the GDP accounts for the first quarter of 2024 – what it calls the “Advance Estimate”.  These initial estimates of the growth of GDP and of its components are eagerly awaited by analysts.  While revised and updated in subsequent months as more complete data become available, it provides the first good indication of what recent growth has been.

In the first quarter of 2024, real GDP grew at an estimated annual rate of 1.6%.  This was viewed by many analysts as disappointing, as the average expectation (based on a survey of economists by Dow Jones) was for 2.4% growth.  And it was a deceleration in the rate of growth of GDP from 4.9% in the third quarter of 2023 and 3.4% in the fourth quarter.  The Dow Jones Industrial Average then fell by 720 points in the first half hour of trading (1.9%), with this attributed to the “disappointing” report on GDP growth.  It later recovered about half of this during the day.

One should have some sympathy for the commentators who are called upon by the media to provide an almost instantaneous analysis of what such economic releases imply.  But if they had examined the release more closely, the conclusion should not have been that economic growth was disappointingly slow, but rather that it has been sustained at a surprisingly high level.  After two quarters of extremely fast growth in the second half of 2023, some moderation in the pace should not only have been expected but welcomed.

The economy under Biden has been remarkably strong.  The unemployment rate has been at 4.0% or less for 28 straight months, and has reached as low as 3.4%.  Unemployment has not been this low nor for this long since the 1960s.  And an economy at full employment can only grow at a potential rate dictated by labor force growth and productivity.  The ceiling is not a hard one in any one quarter (labor utilization rates, and hence productivity, can vary in the short term), plus there is statistical noise in the GDP estimates themselves.  But growth in what is called “potential GDP” sets a ceiling on what trend growth might be.  And if the economy is at or close to that ceiling (as it is now), it can only grow over time at the pace that the ceiling itself grows at.

B.  Potential GDP

There are various ways to determine what potential GDP might be.  A respected and widely cited estimate is produced by the Congressional Budget Office (CBO), with figures on potential GDP for both past and future periods (up to 10 years out).  It is based on estimates of what the potential labor force has been or will be, accumulated capital, and technological progress.  In any given year, the CBO estimates reflect what GDP could be with the capital stock that would be available and the production that capital would allow, along with labor utilization at “full employment”.

The chart at the top of this post shows what real GDP per capita has been over the 11 years from the start of Obama’s second term (2013Q1) to now (2024Q1), along with the estimate by the CBO of potential GDP (expressed in per capita terms).  Not only is the economy now close to the potential GDP ceiling, it is a bit beyond it.  This is possible with the CBO estimates of potential GDP as they assume the labor market cannot sustain for long an unemployment rate of below roughly about 4.5% (which can vary some over time, based on the structure of the labor force).  Hence if actual unemployment is below this – as it is now and as it was for a period in 2019 – “potential GDP” as estimated by the CBO can be below actual GDP.  There are other factors as well, but the level of unemployment is the most significant.

This is also why actual GDP was below potential GDP from 2013 to late 2017 in the chart.  Unemployment was still relatively high in 2013 coming out of the 2008/09 economic and financial collapse.  As discussed in earlier posts on this blog (see here and here) limitations on government spending imposed by the Republican-controlled Congress slowed the recovery from that downturn and kept GDP well below potential for far too long.  This was the first time government spending had been cut following a recession since the early 1970s.  Federal government spending on goods and services fell at an average annual rate of 3.2% each year (in real terms) from 2011 to 2014.  In 2015 and 2016 it was finally allowed to grow, but only at a slow 0.3% per year pace on average.  Only after Trump was elected did Congress allow federal government spending to rise at a more significant rate – at 2.6% per year between 2017 and 2019 (and then by much more in 2020 due to the Covid crisis, by which time Democrats controlled Congress).

This lack of a supportive fiscal policy following the 2008/09 economic and financial collapse slowed the pace of recovery.  Unemployment fell only slowly, but did still fall, and reached 4.7% by the end of Obama’s second term.  The gap between actual and potential GDP diminished, and as seen in the chart at the top of this post, actual GDP has been close to potential GDP since 2018 (with the important exception of the 2020 collapse due to Covid).

The economy is now at – or indeed a bit above – the CBO estimate of potential GDP.  Although there may be quarter-to-quarter fluctuations – as noted above – going forward one cannot expect GDP to grow on a sustained basis faster than that ceiling.  And the CBO forecasts that potential GDP is growing at a 2.2% pace currently, with this expected to diminish over time to a 2.0% pace by 2030 and a 1.8% pace by 2034.  This is primarily due to demographics:  Growth in the labor force is slowing.

Real GDP grew at an average annual rate of 4.1% in the second half of 2023 (3.4% in the third quarter and 4.9% in the fourth quarter).  This is well above the CBO’s estimate of potential GDP growing at a 2.2% rate.  Some slowdown should have been expected.  Even with the 1.6% rate for the first quarter of 2024, real GDP has grown at an average annual rate of 3.3% since mid-2023.  It should not be surprising if GDP growth in the second quarter of 2024 comes in at a relatively modest rate, as the economy returns to the trend growth that potential GDP allows.

However, the initial indication from the Atlanta Fed’s GDPNow indicator is that GDP growth in the second quarter of 2024 will in fact be quite high at a 3.9% rate (in its initial estimate made on April 26 – the most recent as I write this).  If that turns out to be the case, it would not be surprising if the Fed becomes concerned with a pace of growth that is excessively fast.

C.  Other Indicators of an Economy Fully Utilizing Its Potential

One wants an economy that is fully utilizing its potential.  With full employment, one is not throwing away goods and services – as well as the corresponding wages and income – that labor and producers would be eager and able to provide.  But once an economy has reached that potential, it can only grow over time at the rate that that potential grows.  This pace is dictated by demographics (growth in the labor force) and growth in productivity.  While this will be a slower pace than what would be possible for an economy with underutilized labor and other resources – where a period of more rapid growth is possible by bringing into employment those underutilized resources – once one is at the ceiling one cannot grow on a sustained basis at a pace higher than that.  Trying to do so leads to inflation.

With this perspective, a number of observations come together from this release on 2024 first-quarter growth in GDP and its components:

a)  The 1.6% growth rate was viewed as “low”.  But as noted above, this followed exceptionally high growth, of 4.9% in the third quarter of 2023 and 3.4% in the fourth quarter.  One should have expected a slowdown.

b)  There is also evidence of the economy reaching its capacity limits in how the particular components of the GDP figures changed.  Keep in mind that GDP, while derived in these accounts from estimates of what was sold for final demand uses (consumption, investment, etc.), is still a measure of production, not just sales.  That is, GDP – Gross Domestic Product – is a measure of what is produced, produced domestically, and in “gross” terms (because investment is counted in gross terms rather than net of depreciation).

The reason this indirect approach to estimating production works is because whatever is produced and not sold will end up as an increase in inventories.  And this change in inventories is treated as if it were a final demand category.  It can be viewed as a form of investment (investment in inventories), and is included in the accounts as part of overall investment (i.e. it is added to fixed investment, which is investment in machinery and structures).

Furthermore, foreign trade is included in net terms:  exports less imports.  Part of what is produced domestically is sold for exports, while imports supply products that can be used to satisfy domestic demands.

When an economy is operating at or close to potential GDP, one can expect final demands to be increasingly met by drawdowns of inventory (or less of an increase in inventories compared to before) plus a decline in the net trade balance (less exports and/or more imports).  Each can supply product to meet final demands when domestic production is constrained because the economy is operating at close to the ceiling.

One sees both of these in the 2024Q1 figures.  While inventories still rose (by $35 billion, in 2017 constant prices), they rose by less than they had in 2023Q4 (when they rose by $55 billion).  Thus, while GDP includes the change in inventories as one of the demand components along with consumption and other investments, the change in GDP will be based on the change in the change in inventories.  (See this earlier post on this blog.)  And that fell in 2024Q1, as inventory accumulation – while still positive – was not as high as it had been in the previous quarter.  That change in the inventories component reduced GDP growth by 0.35% points relative to what it would have been had domestic production been such that inventory accumulation would have matched what it had been in the preceding quarter.  That it did not can be a sign that domestic production is being constrained by capacity.

Similarly and more importantly, the net trade balance fell.  While exports grew slightly (0.1% of GDP) imports rose by much more (1.0% of GDP), and hence the net trade balance fell by 0.9% of GDP.  This is consistent with domestic production being constrained by an economy that was already at full employment and could not immediately produce much more, and hence with demand that was increasingly met by net imports.

The changes in the net trade balance and in net inventory accumulation totaled 1.2% of GDP (before rounding).  That is, production (GDP) would have had to increase by 2.8% rather than 1.6% to supply domestic purchasers of final (i.e. non-inventory) product.  But with production constrained by capacity limits, the economy had to import more and limit inventory accumulation to less than before.

I should emphasize that this is not a bad position to be in.  One wants an economy operating at full capacity.  But when the economy is operating at full capacity, there will be limits on how much can be supplied domestically.  And as noted before, one cannot expect growth going forward – on average and recognizing there will be period-to-period fluctuations – to exceed the rate at which potential GDP can grow.

c)  Another indication of an economy reaching its potential ceiling is what is happening to prices.  This is more disconcerting.  Price deflators are estimated as part of the GDP accounts in order to convert (deflate) the nominal estimates of the various GDP components into estimates of what the real changes were.  While people focus on changes in real GDP and its components – and properly so – some may not fully realize that the data the BEA collects on production and sales are all in nominal money terms.  It is not really possible for producers to report anything else.  The BEA then converts those nominal money figures to changes in real terms by applying price indices to “deflate” the nominal figures – hence the term “deflator”.  The BEA obtains those price indices – tens of thousands of them – separately, primarily from the price surveys carried out by the Bureau of Labor Statistics.

The initial estimates of the GDP accounts released on April 25 indicated that the price deflators for both overall GDP and for the Personal Consumption Expenditures (PCE) component of GDP demand rose at higher rates than in the preceding several quarters.  The GDP deflator rose in the first quarter of 2024 at an estimated annual rate of 3.1% and the PCE deflator at a rate of 3.4%.  The PCE deflator receives special attention as it is the primary measure of inflation that the Fed focuses on as it considers what monetary policy to follow.  The Fed pays attention to much more as well, of course, but the PCE deflator is special.  And the Fed target for the PCE deflator is 2.0%.

The annualized rates for the GDP and PCE deflators were at 1.6% and 1.8%, respectively, in the fourth quarter of 2023.  They had been generally coming down since mid-2022, and had averaged 2.2% and 2.3% respectively in the final three quarters of 2023.  The increase in the first quarter of 2024 was therefore of some concern, especially when coupled with the other indications (discussed above) that the economy is now at or even above the potential GDP ceiling.

But it is also important to keep in mind that – as often said – one period’s figures do not constitute a trend.  There have been, and will be, quarter to quarter fluctuations.  But the increase in the price deflators from below the Fed’s 2.0% target to a level a good deal higher, coupled with the other indications of an economy operating at or close to capacity, is something to watch.  And it suggests that the Fed is likely to remain cautious and not reduce interest rates from where they now are until they find out more about what is happening to prices.

D.  The Federal Fiscal Deficit is Large

Finally, while not part of the report on the GDP accounts, it should be noted that the federal fiscal deficit remains extremely high.  Recent figures on the Federal Government’s fiscal outlays, receipts, and deficit, expressed here as a share of GDP in the periods, are as follows:

Federal Government Fiscal Accounts

GDP shares

Receipts

Outlays

Deficit

FY2023

16.5%

22.7%

6.3%

CY2023

16.5%

23.0%

6.5%

FY2023 H1

15.4%

23.7%

8.3%

FY2023 H2

17.5%

21.8%

4.3%

FY2024 H1

15.6%

23.1%

7.6%

The GDP shares are calculated from the dollar figures reported in the Monthly US Treasury Statement for March 2024, coupled with the GDP estimates of the BEA.  The Monthly Treasury Statements are definitive in that the reported dollar figures up to the current month rarely change later (although forecasts for the full budget year of course may).  Note also that the reported monthly figures are not seasonally adjusted but are rather the actual fiscal receipts and outlays for the period, while the GDP figures are seasonally adjusted.

In a period of full employment, these deficit figures are all high.  As was discussed in an earlier post on this blog, while high fiscal deficits may well be necessary and appropriate when unemployment is high, one should balance this with lower deficits when the economy is at full employment – as it is now.  The fiscal deficits need not be zero, but a good rule of thumb is to aim for a deficit of perhaps 3% of GDP and no more than 4% of GDP in an economy that is at full employment.  At such deficits, the government debt to GDP ratio will be stable or falling over time, which can then balance out the times when the appropriate policy is to allow for a higher deficit in an economic downturn in order to support a recovery.

The math is simple.  As of March 31, 2024, the total federal debt held by the public was $27.5 trillion (as reported in the Monthly Treasury Statement).  Nominal GDP in 2024Q1 was $28.3 trillion (at an annual rate).  The debt to GDP ratio was thus 97.3% (before rounding), or close to 100%.  If, going forward, one should expect trend growth of about 2% per year in real GDP, inflation of 2% (the Fed’s goal), long-term Treasury interest rates of 4% (i.e. 2% inflation and a 2% real rate of interest on longer-term securities), then a debt to GDP ratio of 100% will stay at 100% if the federal fiscal deficit is 4% of GDP.  The debt ratio will fall with a lower deficit and rise with a higher deficit.

But despite being at full employment, the federal fiscal deficit was 7.6% of GDP in the first half of FY2024.  That is well above the 4% level needed to keep the debt to GDP ratio from rising further.  However, It is not clear whether the deficit has been trending higher or lower.  While the 7.6% deficit in the first half of FY2024 was higher than the 6.3% deficit in FY2023 as a whole, and substantially higher than the 4.3% deficit in the second half of FY2023, it is less than the 8.3% deficit in the first half of FY2023.  There is likely a significant degree of seasonality in the fiscal figures.  But under any reasonable scenario, the deficit will be well above 4% of GDP again this fiscal year.

The issue facing the Democrats is that every time over the past more than 40 years that they have cut the fiscal deficit during their term in office, the subsequent Republican administration has then increased it – through a combination of tax cuts and expenditure increases.  Comparing fiscal years (and avoiding recession years given their special nature, and based on data from the CBO), the fiscal deficit under Ford in FY1976 was 4.1% of GDP.  Carter brought that down by FY1979 to just 1.6% of GDP.  Reagan tax cuts and expenditure increases then raised the deficit to 5.9% of GDP in FY1983, and it was 4.5% of GDP under Bush I in FY1992.  The fiscal accounts then moved into a surplus under Clinton following the steady and strong growth in real GDP during his presidency, reaching a surplus of 2.3% of GDP in FY2000.  On taking office, Bush II at first advocated tax cuts because the economy was strong and the fiscal accounts were in surplus, but then after the downturn a few months after taking office, Bush II promoted tax cuts because the economy was weak.  The tax cuts did go through, and with fiscal revenues falling as a share of GDP while expenditures rose, the fiscal deficit reached 3.4% of GDP in FY2004 – a huge shift of 5.7% points of GDP from where it was in Clinton’s last year in office.

With the economic and financial collapse in 2008 in the last year of the Bush II presidency, the deficit rose to 9.8% of GDP in FY2009 in Obama’s first year.  This stabilized an economy that had been in freefall as Obama took office (with the sharpest downturn since the Great Depression), but as noted above, subsequent cuts in government spending then slowed the full recovery.  Eventually the economy did recover, and the fiscal deficit was reduced to 2.4% of GDP in FY2015 and a somewhat higher 3.1% of GDP in FY2016 when federal government spending was finally allowed to grow, albeit modestly.

Taxes were then once again cut under the Republican presidency of Trump, and despite an economy at full employment, the fiscal deficit rose to 4.6% of GDP in FY2019.  It then exploded with the Covid crisis, to 14.7% of GDP in FY2020 and 12.1% in FY2021, before falling under Biden to 5.4% of GDP in FY2022 and 6.3% of GDP in FY2023.

So what should be done?  This is not the place for a full analysis, but broadly, fiscal revenues as a share of GDP are low in the US.  Total tax revenue (including by state and local governments) is lower in the US than in any other high-income member of the OECD with just one exception (Switzerland), with US tax revenues more than 6% points of GDP less than the OECD average (in 2022).  A post on this blog from 2013 – now perhaps out of date – showed that the federal government debt to GDP ratio would have fallen sharply – rather than increase – in the years then following if the Bush II tax cuts had been allowed to expire in full at the end of 2012.  The figures would be different now, but the basic point remains that both compared to other high-income nations and to the historical record, the US suffers from a chronic fiscal revenue problem.

A reasonable target for federal fiscal revenues might be 20% of GDP – the same share of GDP as in FY2000.  That would be an increase of 3.5% of GDP from the 16.5% collected in FY2023.  Taxes collected in the US would still be less – as a share of GDP – of all but two of the higher-income OECD members (Australia and Switzerland), and also far less than the OECD average.

There are also always some fiscal expenditures that could also rationally be cut (but where there is always disagreement on which), but even with no cuts in expenditures, revenues of 20% of GDP in FY2023 would have brought the deficit down from 6.3% of GDP to 2.8%.  And as discussed above, a deficit of 2.8% of GDP would be expected to lead to a downward trend over time in the government debt to GDP ratio.

One option to get fiscal revenues back to around 20% of GDP would be simply to bring back the taxation rules of that year.  They were not excessively burdensome – the economy was performing well at the time with solid GDP growth and low unemployment.  But better would be to introduce true tax reforms, such as ending the disparities in the tax system where different forms of income are taxed differently (as discussed, for example, in this earlier post on this blog).  The most significant such disparity is that income from wealth (which is, not surprisingly, mostly held by the wealthy) is taxed at lower rates than income from wages.  But with Republicans in control of Congress, such a reform would never be passed.

E.  Summary and Conclusion

The economy is at full employment and is producing at or close to the ceiling allowed by its productive potential.  Going forward, one should not expect growth in real GDP to be greater than the pace at which this ceiling grows.  There may well be quarter-to-quarter fluctuations around this, as the ceiling is not absolute (labor utilization can vary) plus there is statistical noise in the GDP estimates themselves, but over time one should expect – and indeed welcome – growth that averages what that ceiling grows at.  The CBO estimates that potential GDP is growing at a rate of about 2.2% per annum currently, and expects this to fall over time to a 2.0% rate by 2030.

The 1.6% rate of growth in the first quarter of 2024 should be seen in this light.  Real GDP had grown at rates of 4.9% in the third quarter of 2023 and 3.4% in the fourth quarter, and a slowdown from such a pace should not only have been expected but welcomed.

Indeed, there may be a concern that GDP growth has been too rapid since mid-2023.  Even with the 1.6% growth of the first quarter of 2024, growth has averaged 3.3% since the middle of last year.  And there are signs in the GDP accounts themselves of an economy producing at capacity.  Inventory accumulation slowed relative to what it was before while the foreign trade balance fell as imports rose substantially.  The deflators for GDP and for Personal Consumption Expenditures also rose – to annualized rates of 3.1% and 3.4% respectively – after following a downward trend since mid-2022.  This is, however, an increase for the deflators for just one period at this point, and one should not assume until there is further evidence whether this marks a change in that previous trend.

For an economy at full employment, the current size of the fiscal deficit is a concern.  At full employment one should be aiming for a deficit of below around 4% of GDP in order at least to stabilize and preferably reduce the government debt to GDP ratio.  But in FY2023, the deficit was 6.3% of GDP.  The US has been facing chronic deficit issues for decades now – a consequence of the tax cut measures pushed through by Reagan, Bush II, and Trump.  A reasonable goal now would be a tax reform that removes the distortions from taxing different types of income differently, with rates then set to obtain fiscal revenues of around 20% of GDP – an increase of 3.5% points of GDP compared to the revenues collected in 2023.  The tax rates on income from wealth would rise from the preferential rates they now enjoy, while the tax rates on income from wages (and other “ordinary income”) might well fall.

Even with such an increase, fiscal revenues collected would still be well below the OECD average, and below that of all but only two of the higher-income OECD members.  In contrast, cuts in expenditures (as was done, as a share of GDP, during the presidencies of Carter, Clinton, and Obama), are likely to be followed in the next Republican administration with another round of tax cuts.

The Federal Deficit is High, Rising, and Unsustainable at This Level

The federal fiscal deficit fell sharply in Biden’s first year and a half in office.  This was largely due to the expiration of the huge Covid relief programs that had been approved both during Trump’s last year in office and then at the start of Biden’s term (totaling $5.7 trillion, and equivalent to 12.8% of the GDP of 2020 and 2021 together).  The deficit was an astonishing 16.5% of GDP in the last 12 months of the Trump administration, and peaked at 19.2% of GDP in the 12 months leading up to March 2021.  It then came down rapidly, reaching a trough of 3.9% of GDP in the 12 months leading up to July 2022.  But it then turned upward, and is now at about 8.5% of GDP.

The figures are shown in the chart above.  They were calculated from the regular Monthly Treasury Statement released by the US Treasury, which has monthly figures on federal government receipts (revenues collected), outlays (expenditures in a broad sense), and the resulting deficit.  The most recent such statement (the one used here) was released in mid-August with figures through July.  The figures once published are rarely changed, and thus appear to be actual revenue and expenditure numbers and not estimates of what they were in any given month.

The figures will always bounce around substantially from month to month, due to factors such as when major payments on income taxes are due (e.g. each April), when expenditures are bunched (due to the fiscal year cycle), and other such seasonal factors.  Thus for the chart here I have calculated 12-month rolling totals for the figures, ending on the dates shown.  And I have expressed them as a share of average GDP over the period.  Since GDP figures are only available on a quarterly basis, I estimated month-to-month GDP figures based on an assumed constant rate of growth over the three months within each quarter.  The GDP figures were downloaded from FRED.

I also extrapolated the figures to the end of fiscal year 2023 – i.e. through to September 2023.  I suspect there will be a good deal of discussion on the sharp growth in the federal fiscal deficit in FY2023 when the full fiscal year figures are released in early October.  This post can be considered a preview, where while the final numbers will not be exactly the same as those estimated here, they will likely be close.

For the extrapolation, I assumed that federal outlays, receipts, and resulting deficits in August and September 2023 will be the same as they were in August and September 2022.  This was more reasonable than extrapolating the recent trend as the monthly figures fluctuate sharply due to seasonal factors, as noted above.  But it may well underestimate what the deficits will be in August and September 2023 due to the underlying upward trend of the past year.

For GDP for the third quarter of 2023 (where the preliminary estimate will not be released until near the end of October), I used the most recent forecast of third-quarter GDP growth produced by the Atlanta Fed.   The Atlanta Fed’s “GDPNow” forecasts have generally been quite good (far better than various consensus forecasts of panels of economists), and are based on a mechanical method where the forecast is first produced and then updated in real-time when key data are released – during the course of the quarter – on elements of what goes into GDP.  Correlations were worked out based on historical data, with those correlations then used – every time new data is released – to update the forecast of what GDP will be when an estimate is ultimately provided by the BEA at the Department of Commerce.

I have gone into a bit of detail on the Atlanta Fed’s GDPNow forecasting process as its most recent forecast (as I write this) is for GDP growth in the third quarter of 2023 to be quite high – at an annualized real growth rate of 5.9%.  This is a good deal higher than the most recent official (BEA) estimates of GDP growth of 2.4% in the second quarter of 2023 and 2.0% in the first quarter.  It is also substantially higher than the “Blue Chip” consensus forecast of a panel of economists of just 1.6%.  We will see who ends up being closer to the final figure on GDP growth, but for the chart above I used the 5.9% rate.  With this relatively high rate of growth for GDP, the federal deficit and other figures as a share of GDP will be biased in the downward direction.  Despite this bias (as well as that following from the use of 2022 figures for August and September, despite the upward trend in the deficit this year), the resulting federal fiscal deficit for FY2023 (which ends in September 2023) is conservatively estimated to be 8.5% of GDP.

A fiscal deficit of 8.5% of GDP in a period when unemployment is low is huge.  The unemployment rate has been at 3.7% or less (and as low as 3.4% – with this all within the range of statistical uncertainty) since March 2022.  It has not been at a level so low for such an extended period since 1968/69 – more than a half-century ago.  The increase in federal expenditures certainly in part accounts for this (Keynes is once again shown to have been right), but a fiscal deficit of 8.5% of GDP is not sustainable.

The gross federal debt held by the public (the relevant concept, as intragovernmental holdings of public debt will net out) was 95% of GDP as of 2022.  Round this up to 100% of GDP.  It is then easy to see that if one assumes, going forward, that real GDP growth will average 2.0% per year, say (it averaged 1.93% per year from 2000 to 2023), and if the inflation rate (the GDP deflator) matches the 2.0% Fed target for general consumer inflation, then the public debt to GDP ratio will remain flat if the fiscal deficit equals 4.04% per year (as that equals the compounded effect of 2.0% real growth and 2.0% inflation).  A fiscal deficit of 8.5% of GDP is far above this.  At such a deficit, the debt to GDP ratio will grow.  At a deficit of 4% of GDP or less, then with 2% growth and 2% inflation the debt to GDP ratio will fall from where it is now.

Why has the fiscal deficit grown by so much since the trough at 3.9% of GDP in July 2022?  I do not know enough about the fiscal accounts to say, but a few points can be made.  First, it was not due to rising interest rates.  While the US Treasury will need to pay higher interest rates on newly issued debt as the Fed has been raising interest rates, most Treasury debt is longer term and only comes up for renewal slowly over time.  According to the July 2023 Monthly Treasury Report, gross interest payments rose by $136 billion in the fiscal year to date (i.e. from October 2022 through to July 2023) compared to the same period in the prior fiscal year.  This is just 0.6% of GDP if one extrapolates it out to a full 12-month period,

In terms of the broad categories shown on the chart above, what was far more important was a fall in federal receipts (revenues) over the last year.  Federal receipts came to 19.6% of GDP in the 12 months leading up to July 2022, and fell to 16.8% of GDP in the (forecast) 12 months leading up to September 2023.  This was a reduction in receipts of 2.8% of GDP, and accounts for about 60% of the increase in the deficit during this period (which went from 3.9% of GDP to a forecast 8.5%, an increase of 4.6% of GDP).  An increase in federal outlays, rising from 23.5% of GDP in the 12 months leading up to July 2022 to 25.3% in the 12 months leading up to September 2023 (an increase of 1.8% of GDP), accounts for the other 40%.

I am not sure why federal receipts fell over the last year, but a guess would be that they rose in the period from early 2021 to mid-2022 (keeping in mind that these will always be for trailing 12-month periods) due to rebound effects from the Covid relief programs.  Those programs included deferral of when taxes would be due, and also provided for higher government expenditures on a variety of Covid-related activities.  These would translate into higher incomes, with this then leading to higher taxes later becoming due.  There was also major direct income support, although most of this was not taxable.

But for whatever reason, federal government receipts as a share of GDP have fallen substantially since mid-2022 and account for the major share (60%) of the increase in the deficit.  However, it is also important to note that while federal receipts have fallen relative to mid-2022, they are now (as a share of GDP) roughly where they were in early 2020, prior to the onset of the Covid crisis.  In fact, they are a bit higher, at 16.8% of GDP now compared to 16.5% in the 12 months leading up to early 2020.

Federal outlays are, however, substantially higher than where they were in early 2020.  They are now at 25.3% of GDP, versus 21.4% of GDP in early 2020, an increase of 3.9% of GDP.  This more than accounts for the increase in the fiscal deficit since then – rising from 5.0% of GDP in early 2020 (during the Trump administration but pre-Covid) to 8.5% now.  I have discussed before why the deficit of 5% of GDP during the Trump years (pre-Covid) was unwise, exceptional for a period when the economy was at full employment, and not sustainable.  The same is true with a deficit of 8.5% of GDP during a period when the economy is also at full employment.

Much of the new expenditures of the Biden administration are certainly high priority.  Climate change needs to be addressed, for example, and the US has long neglected its public infrastructure and there is an urgent need to repair it.  But I do not have a detailed breakdown of the expenditures, how they compare to expenditures before, and the needs being addressed.  But regardless, the now Republican-controlled House of Representatives will certainly force major cuts in federal expenditures, just as the Republican-controlled House elected in 2010 forced through major expenditure cuts during the Obama presidency.  Fortunately, the economy is now at full employment, while unemployment was still high in 2011 when the Republicans started to force major expenditure cuts on the Obama administration.  There had not been such cuts in fiscal expenditures with unemployment still high in periods recovering from a recession since before World War II.  The result was the exceptionally slow pace of employment growth following the financial and economic collapse of 2008/2009.

Attention should also be given to increasing fiscal revenues as part of a program to reduce the fiscal deficit.  A return of federal receipts to the approximately 18% of GDP share towards the end of the Obama presidency in 2016 would help in reducing the deficit to a sustainable level.  A good start would be to reverse the Trump tax cuts rammed through the Republican-controlled Congress in late 2017 on party-line votes – tax cuts that led to corporate income taxes being reduced by half and which introduced numerous new tax loopholes and other measures favoring the rich.  But with Republicans now in control of the House, that will of course not happen.

A deficit of 8.5% of GDP is not sustainable.  It will need to come down, with a deficit of 4% of GDP or less a reasonable goal.  There is a need for a constructive debate on how best to do this.  Unfortunately, given the state of American politics, it is unlikely that any debate will be constructive.

=========================================================

Update:  October 31, 2023

Final figures have now been released for FY2023 federal government outlays and revenues, with the release of the September 2023 Monthly Treasury Statement. The initial estimate of GDP in the third quarter of 2023 has also now been provided.  From these, we can calculate what the federal fiscal deficit was as a share of GDP in FY2023, and compare that to the estimates made when only data through July 2023 were available.

The FY2023 fiscal deficit came in at 6.3% of GDP.  This deficit figure is still high – it is well above the 5% of GDP rule of thumb on when one should be concerned (in an economy at full employment), and above the figure of around 4% of GDP where the government debt to GDP ratio would be flat.

But the 6.3% of GDP deficit is substantially better than the 8.5% estimate provided in the post above.  That figure was based on extrapolations from data that, at the time, were only available through July 2023.  Why the difference?  It turns out to be due almost entirely due to substantially lower than expected fiscal outlays in the final two months of the fiscal year (i.e. August and September).  The estimates made in the post assumed that the fiscal deficit in August and September 2023 would be the same as the deficit in those two months in 2022.  But the deficit turned out to be 2.1% of annual GDP lower in 2023 than it was in those same two months in 2022.  Within round-off, this is the same as the 2.2% of GDP difference between the 8.5% of GDP forecast, and the 6.3% of GDP realization.

This was basically entirely due to lower federal expenditures (outlays).  Those expenditures were 2.3% less, in terms of annual GDP, in August and September 2023 than they were in those two months in 2022.  Federal revenues were also a bit less, but only by 0.2% of annual GDP.

Note that all these figures have been presented in terms of annual GDP for the fiscal years 2022 or 2023.  But GDP is a flow, and GDP in just the two months being considered will of course be far less.  Based on the advance estimate of GDP in the third quarter of 2023, and assuming GDP in the two months will be two-thirds of that in the three months in the quarter (and also taking GDP at the quarterly, not annual, rate), the reduction in the deficit in those two months relative to the same two months in 2022 comes to 12.3% of the GDP of those two months.  That is gigantic!  While there is substantial volatility in the monthly figures, it is surprising that fiscal expenditures would change by so much in that period compared to what it was in the same period of the prior year.


The Unemployment Rate, the Growth in Employment, and Productivity

A.  Introduction

The January jobs report (more properly the “Employment Situation” report) released by the Bureau of Labor Statistics (BLS) on February 3, was extraordinarily – and surprisingly – strong.  The unemployment rate fell to 3.4% – the lowest it has been since May 1969 more than a half-century ago.  And despite the low unemployment rate, the number of “new jobs created” (also a misnomer – it is actually the net increase in non-farm payroll employment) was a surprising 517,000.  But it was not only this.  The regular annual revisions undertaken each January to reflect revised population controls and weights for the employment estimates led this year to significantly higher labor force and employment estimates.  With the new industry weights, the increase in the estimated number of those employed in 2022 (the number of `”new jobs”) rose to 4.8 million.  The earlier estimate had been 4.5 million.

All this is an extraordinarily strong jobs report.  However, one should not go too far.  It is important to understand what lies behind these estimates, as well as some of the implications.  For example, strong growth in the total number employed while GDP growth is more modest implies that productivity (GDP per person employed) went down.  That could be a concern, except that when viewed in the context of the last several years we will see that productivity growth has in fact been rather good.

This post will first examine the new figures on unemployment and then on employment growth.  We will then look at the change in productivity – both in the recent past and from a longer-term perspective.

B.  The Unemployment Rate and Its (Non)-Impact on Inflation

The unemployment rate in January fell to 3.4%.  This is the lowest it has been since May 1969.  And if it falls a notch further to 3.3% in some upcoming month, it will have fallen to the lowest since 1953.

A 3.4% unemployment rate is certainly low.  But what is more significant is that the unemployment rate has been almost as low for most of the past year.  It fell to just 3.6% in March 2022, and until last month varied within the narrow range of 3.5 to 3.7% – hitting the 3.5% rate several times.  It is now at 3.4%, but what is most significant is that it has been at 3.7% or less for almost a year.

One needs to recognize that the unemployment rate is derived from a survey of a sample of households (implemented by the Census Bureau) called the Current Population Survey (CPS).  The CPS sample includes approximately 60,000 households each month, in a rotating panel, and from this they derive estimates on the labor force participation rate, the unemployment rate, and much more.  It complements the Current Employment Statistics (CES) survey, which covers a much larger sample of 122,000 businesses and government agencies representing 666,000 individual worksites (with each employing many workers).  Hence employment figures are generally taken from the CES as there will be less statistical noise.  But the employers surveyed for the CES cannot know how many workers are unemployed (they will only know how many workers are employed by them), so the smaller CPS needs to be used for that.  (A brief explanation of the CPS and CES is provided by the BLS as a “Technical Note” included in each of the monthly Employment Situation reports.)

Due to the size of the sample, the estimated unemployment rate is actually only known within an error limit of +/- 0.2 percentage points, using a 90% confidence interval.  That is, simply due to the statistical noise a change in the unemployment rate of 0.1 percentage point from one month to the next should not be considered statistically significant, and 10% of the time even a 0.2 percentage point change may have just been a consequence of the statistical variation.  However, repeated observations over several months in a row of an unemployment rate at some level will be a measurement one can have much more confidence in.  That can no longer be a consequence of simply statistical noise.  Thus one should not place too much weight on the January change in the unemployment rate to 3.4% from 3.5% the month before.  But the fact that the unemployment rate has consistently been within the relatively narrow – and extremely low – range of 3.4 to 3.7% since March 2022 is highly significant.

An unemployment rate anywhere close to a range of 3.4 to 3.7% is also far below the rate at which economists used to believe would be possible without the rate of inflation accelerating – i.e. without inflation going higher and higher.  This was given the acronym name of “NAIRU” (for Non-Accelerating Inflation Rate of Unemployment).  It was held that at an unemployment rate of less than the NAIRU rate, the rate of inflation would rise from whatever pace it was at to something higher.  This was viewed as unsustainable, and hence the proper goal of economic policy was, in this view, to manage macro conditions so that the unemployment rate would never fall below the NAIRU rate.  That rate was also sometimes called the “full employment rate of unemployment”.

The question then is what the NAIRU rate might be.  While different economists came up with different estimates, estimates generally fell within the range of 5 to 6%.  An unemployment rate of less than this would then (under this theory) lead to a rise in inflation.

But that did not happen.  The unemployment rate fell to below 5% in 2016, and inflation remained low.  It fell to below 4% in 2018 and inflation remained low.  It fell to 3.5% in 2019 and into early 2020 and inflation remained low.

With the once again very strong labor market – with unemployment hitting 3.4% – has this now changed?  The rate of inflation did rise in 2021 and into 2022.  But if one looks at this chart, one sees that the timing is wrong:  Inflation rose earlier – in 2021 – when the unemployment rate was still well over 6% early in the year.  Furthermore, nominal wages only rose later:

Inflation (measured here by the consumer price index – the CPI – for all goods and services) can be volatile, but the upward trend began already in the second half of 2020 (although in part this was initially due to a recovery in prices from depressed levels earlier in 2020 due to the Covid crisis).  The chart shows the rates in terms of 3-month rolling averages (at annual equivalent rates and in arrears, so the figure for a January, say, would be for the months of November through January).  The pace of change in nominal wages (also as 3-month rolling averages and at annual rates) did not start to rise until mid-2021.  The increase in nominal wages appears to be more in response to the prior increase in prices – as firms found it profitable to employ more workers in an economy that grew strongly in 2021 – rather than a cause of those higher prices.  This is consistent with the view that the inflation was primarily due to demand-pull, rather than cost-push, factors.

[Technical Note:  The figures on changes in the nominal wage come from data assembled by the Federal Reserve Bank of Atlanta, drawing on data that can be obtained in the underlying micro-data files of the CPS.  The rotating panel of households in the CPS are interviewed for four months, not interviewed for the next eight months, and then interviewed again for four months.  New households are added each month and then removed after month 16 for them.  This allows the researchers to match individuals with their reported wages to what they had earned 12 months before.  It also allows them to examine the wage changes broken down by individual characteristics – such as age, gender, race, education level, occupation, where they are in the income distribution, and more – as these are all recorded in the CPS.  It is all very interesting, and worth visiting their website where they make it easy to see the impact on the measured changes in wages of many of these different factors.

The matching of wage changes by individuals also provides a much more reliable index than the commonly cited changes in average wages provided in the monthly Employment Situation report.  The latter comes from what employers report in the CES survey on the average wages they are paying.  Those averages will be affected by compositional effects.  For example, the reported average wages will often jump at the start of an economic downturn – such as it did in 2020 – as the less experienced and lower-wage workers are generally laid off first.  This leaves a greater share of more highly paid workers, which will lead the reported average wage to rise even though the economy had entered into a downturn.]

Not only did the rise in inflation precede the more modest increase in the pace at which nominal wages rose, but since mid-2022 the rate of inflation has come down while the job market has, if anything, become tighter.  The unemployment rate, as noted above, has been in the 3.4 to 3.7% range since March 2022, and is now at 3.4%.  Despite this, the three-month average increase in the seasonally adjusted CPI fell from 11.0% (at an annual rate) in the three months ending in June 2022, to just 1.8% in the three months ending in December.  If a tight labor market was driving inflation, one would have expected inflation to have kept going up rather than fall – and certainly not to fall by such a degree.

Furthermore, growth in nominal wages fell slightly from a peak of over 6.7% in the three months ending in June and also July 2022 (at an annual rate), to 6.1% as of December.  One would have expected the pace of change in wages to have continued to go up, rather than start to ease.

It is still early to be definitive on any of this.  Trends could change again.  Importantly, a significant part of the sharp fall in inflation in the second half of 2022 (when measured by the full CPI) was due to a fall in the prices of oil and other energy products.  However, while more recent, there are also early indications that core inflation (where food and energy prices are left out) is also falling.  In terms of the core CPI (again the seasonally adjusted index), the pace of inflation fell from a peak of 7.9% (at an annual rate) in the three months ending in June 2022, to just 3.1% in the three months ending in December.

That measure of inflation – the core CPI, which is often taken to be a better measure of underlying inflationary trends than the overall CPI as food and energy prices are volatile and go down as well as up – is now falling despite unemployment at the lowest rate it has been in more than a half-century.  If a tight labor market was driving inflation, then one would expect the pace of inflation to be rising, not falling.

C.  Employment Growth

The January jobs report was also noteworthy for its figures on employment growth.  Nonfarm payroll employment rose by 517,000 – far higher than most expected.  It is not that an increase in employment of a half million in a month is unprecedented.  It is rather that there was such an increase even though the unemployment rate was already at an extremely low 3.5% in the prior month.  (And while nonfarm payroll employment excludes those working in agriculture, that number is now small at only 1.4% of the labor force – based on estimates from the CPS and including those in agriculture who are self-employed.  It also excludes the self-employed outside of agriculture – a more substantial 5.6% of the labor force according to the CPS – but still not that large.  In terms of changes in the numbers from one period to the next, the impact on the employment estimates will be small.)

In addition, the January report also reflected revisions – undertaken every January – where new weights are used to generalize from what is found in the sample in the CES of firms and other entities (such as government agencies) that employ workers to what is estimated for the economy as a whole.  The re-weighting is based on a comprehensive count of payroll jobs in March of the year, with this then used to revise the estimates for all of the year (2022 in this case).

Due to the new weights, the increase in the number of jobs in the economy rose from the earlier estimate of 4.5 million in 2022 (i.e. from December 2021 to December 2022) to 4.8 million.  Between January 2022 and January 2023 the increase was an estimated 5.0 million additional jobs.  That is, between January 2022 and January 2023, the number employed increased by an average of 414,000 per month.

The 4.8 million growth in the number employed in 2022 was remarkable not only because it is a big number, but also because it came after the even stronger growth in employment in 2021.  Employment grew by 7.3 million in 2021.  In absolute terms, the 4.8 million figure in 2022 is higher than that of any year (other than 2021) in the statistics going back to when they started to be collected in the present form in 1939 (using BLS data).  Such a comparison is more than a bit unfair, of course, as the US economy has been growing and there are far more people employed now than decades ago.  But taking 2021 and 2022 together, the percentage growth over the two years – at 8.5% – was exceeded since 1951 only by greater increases in 1977-78 (10.2%), in 1965-66 (9.7%), and in 1964-65 (8.7% – that is, there was strong growth in the three straight years of 1964, 1965, and 1966).  Joe Biden was right when he said job growth in the first two years of his presidency (of 12.1 million) was greater than that of any other president, but it is not really a fair comparison as the economy is now larger.  But even in percentage terms, his record is excellent.

But such growth in the number employed cannot continue much longer.  To put this in perspective, the total adult population in the US (as reflected in the CPS, and with the new population controls) rose by only 1.8 million between January 2022 and January 2023, or 150,000 per month on average.  And the labor force figure, as estimated in the CPS, grew by only 1.3 million over that period, or 111,000 per month.  One cannot keep adding 414,000 per month to the number employed (as we saw in the year to January 2022) when the labor force is only growing by 111,000 per month, when the unemployment rate is already at a historical low of 3.4%.

[Note that one cannot simply subtract the January 2022 figures reported from the new January 2023 figures, since in the CPS they do not go back and revise the previous year figures to reflect the new population controls.  But they do show what the impact would have been on the December 2022 figures, and I assumed that they would have had the same impact on the January 2023 numbers.  The impacts should be similar.  One can then do the subtractions on a consistent basis.]

An increase in the number employed of an estimated 414,000 per month when the labor force was growing by only an estimated 111,000 per month was possible in 2022 in part because the unemployment rate came down (from 4.0% in January 2022 to 3.4% in January 2023), and in part because the labor force participation rate went up slightly (from 62.2% in January 2022 to 62.4% in January 2023).

But also a factor is that these are surveys from two different sources (households for the CPS and firms and other employers for the CES), and the sample estimates will not always be fully consistent with each other.  As was discussed in an earlier post on this blog, the estimates can differ from each other sometimes for significant periods of time.  However and importantly, over the long term the two estimates will eventually have to approach each other.  The population estimates used for the CPS will yield (for a given labor force participation rate) figures on the labor force, and hence growth in the adult population will yield figures on growth in the labor force.  For a given unemployment rate, the number employed – within the bounds of the statistical estimates – cannot grow faster than this.

With the unemployment rate now at 3.4%, one should not expect much if any further fall.  Indeed, the general expectation (and the more or less openly stated hope of the Fed) is that it will start to rise.  It is possible that the labor force participation rate will rise, but changes in this are generally pretty slow, driven mostly by demographics and social factors (the share of people aging into the normal age of retirement; the share of the young entering into the labor force given their decisions on whether and for how long to enroll in colleges and universities; decisions by households on whether one or both spouses will work; and similarly).

While there will be uncertainty in what will happen to the unemployment rate and the labor force participation rate, for given levels of each of these, employment cannot grow any faster than the labor force does.  (Indeed it is slightly less:  At an unemployment rate of 3.4%, employment will only grow at 96.6% of what the labor force grows by.)  With the labor force growing by 111,000 per month in the year ending in January 2023 (with this already reflecting a small increase in the labor force participation rate from 62.2% to 62.4%), it will not be possible for the monthly increase in employment to grow by much more than this.

Looking forward, one should not, therefore, expect growth in the number employed to be sustained at a level that is anywhere close to the 517,000 we had in January.  There will be month to month fluctuations, but one should not expect an average increase over several months that would be much in excess of the 111,000 figure for the growth in the labor force seen in the year ending in January 2023.

D.  Productivity

Politicians like strong job growth.  It is indeed popular.  But the flip side of this is that while the number employed grew rapidly in 2021 (by 3.2% December to December), GDP growth was less (1.0% from the fourth quarter of 2021 to the fourth quarter of 2022, based on the most recent estimates).  With the number employed growing faster than GDP, the mathematical consequence is that GDP per person employed went down.  That is:  Productivity fell in the year.

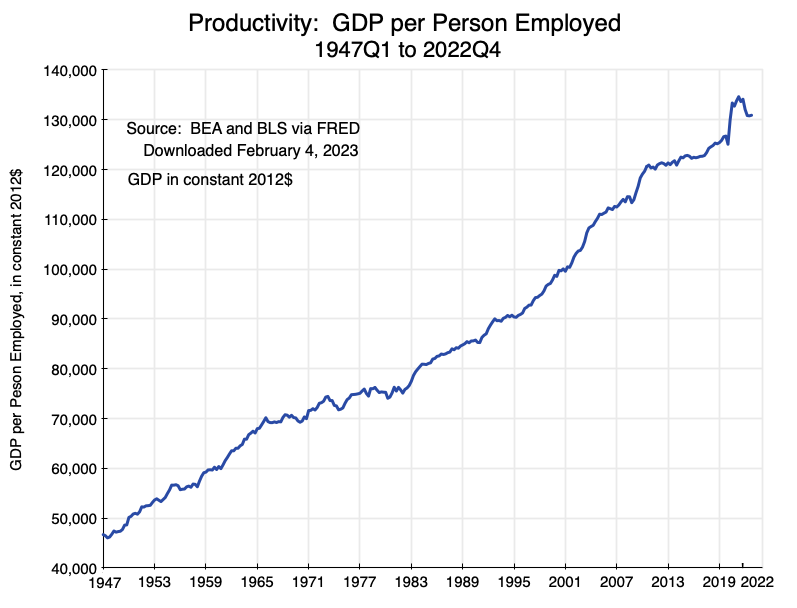
Higher productivity is ultimately what allows for higher living standards.  Falling productivity would thus be a problem.  However, in the context of the last several years, productivity growth has in fact been pretty good:

We are once again seeing the consequences of the highly unusual circumstances surrounding the Covid crisis.  With the onset of a downturn, firms will lay off workers.  But they may often lay off more workers than their output falls.  This might be because of uncertainty on how much the demand for whatever they make will fall in the downturn (and they will wish to be careful and if anything to overcompensate, given the difficulty of obtaining finance in a downturn and the very real possibility of bankruptcy); or because special government programs during the downturn reduce the cost to them and their workers of these layoffs (for example through the common response of extending unemployment benefits and making them more generous); or because the first workers being laid off are the least productive ones (possibly because they are relatively new and do not yet have as much experience as others working there) so that they end up with a workforce which is on average more productive.  Or, and very likely, it could be a combination of all three factors.  It looks very much like Schumpeter’s “creative destruction”.

The consequence is that productivity can in fact jump up in a downturn.  One sees such a clear jump in the chart in 2020, at the time of the sharp collapse due to the Covid crisis.  One also sees it in 2008-09, with the financial and economic collapse in the last year of the Bush administration and then the turnaround that began in mid-2009.  In terms of the numbers:  Real GDP fell by 1.3% between the first quarter of 2020 and the third quarter of 2020 (in absolute terms – not annualized).  But employment over this period fell by 7.4%.  As a result, productivity (real GDP per person employed) jumped by 6.6% in this half year.  In 2008/2009, real GDP was basically flat between the last quarter of 2008 and the last quarter of 2009 – rising by just 0.1%  But employment over this period fell by 4.1%, leading to an increase in productivity of 4.4%.

Following these brief periods where businesses are scrambling to survive the downturn by producing more (or perhaps not too much less) with many fewer workers, firms then enter into a more normal period where, as the economy recovers, they are able to sell more of their product.  They hire additional workers who are, by definition, less experienced in the work of that firm than their existing workforce.  The new workers might also be less capable or have a less applicable skill mix.  Productivity may then level off or even go down.  The latter situation is in particular likely when the economy recovers quickly and firms scramble to keep up with the increased demand for their product.

The latter fits well with what we saw in 2021.  GDP in 2021 rose by 5.9%, the highest of any year since 1984.  And the Personal Consumption component of GDP rose by 8.3% in 2021, the highest of any year since 1946.  This was spurred by the series of Covid relief packages passed in 2020 (under Trump) and in 2021 (under Biden), which totaled $5.7 trillion in the two years, or 12.8% of GDP of 2020 and 2021 together.  Personal savings rose to an unprecedented level as a share of GDP (other than during World War II, with data that go back to 1929), which then supported the strong growth in personal consumption in 2021.  This is consistent with a demand-led inflation that got underway in late 2020 or early 2021 (discussed above) – a risk of inflation that Larry Summers had warned of in early February 2021 when Biden’s $1.9 trillion Covid package was first proposed (and eventually passed, largely as proposed).

But what matters to long-term living standards is not so much the changes in average productivity in the periods surrounding economic downturns, but rather the trends in productivity growth over time.  A ten-year moving average is a useful metric:

The chart shows rolling ten-year averages starting from 1947/57 through to 2012/22 of the growth in GDP, in employment, and in productivity (GDP per person employed).  Productivity growth was relatively high at about 2% per annum in the 1950s and through most of the 1960s.  But it then started to fall in the 1970s to less than 1% a year before recovering and returning to about 2% a year in the ten-year period ending in 2004.  It then fell to roughly 0.8% a year since about 2017 (in terms of the ten-year averages), with some sharp fluctuations around that rate associated with the 2020 Covid crisis.  As of the end of 2022, the most recent ten-year average growth rate for productivity was 0.80%.

This has important implications for GDP growth might be going forward.  The labor force grew by 0.8% in 2022 (the adult population grew by 0.7%).  With unemployment close to a record low, employment will not be able to grow faster than the labor force – as discussed above.  And the labor force cannot grow faster than the adult population unless labor force participation rates increase.  But while there major disruptions in labor force participation in 2020 and 2021 surrounding the Covid crisis – with its lockdowns, economic collapse and then recovery, as well as health concerns affecting many – labor force participation largely returned to previous patterns in 2022.  Labor force participation rates have been slowly trending downwards since the late 1990s, and while it is possible this pattern might be reversed, it is difficult to see why it would.  There might well be short-term fluctuations for a period of a few years, but longer-term patterns are driven mostly by demographics (the age structure of the population) and social customs (e.g. whether women decide to enter into the paid labor force).

What follows from this is that if the labor force continues to grow at 0.8% a year (as it did in 2022 – and it grew only at a lower rate of 0.6% a year in the ten-year period ending in 2022), and productivity grows at 0.8% a year (as it did in the ten-year period ending in 2022), then GDP can at most grow at 1.6% a year on average.  This would be disappointing to many.  While there certainly can be and will be significant year to year variation around such a trend, faster growth would require either higher productivity growth or more entering into the labor force.

E.  Summary and Conclusion

The January jobs report was strong.  The unemployment rate is now at the lowest it has been in more than a half-century, and the number employed grew by more than a half million – a very high figure when the unemployment rate is so low.  While these are still preliminary figures and are subject to change as additional data become available, they present a picture of an extremely strong labor market.

The fall in the unemployment rate by one notch to 3.4% from the previous 3.5% should not, in itself, be taken too seriously.  That is well within the normal statistical error for this figure.  But what is indeed significant is that the unemployment rate has been within the narrow range of just 3.4 to 3.7% since March 2022.  That is low.  And it was in this low range during a period (in the second half of 2022) when inflation was coming down.  While changes in the price of oil have been a major factor in driving the inflation rate in 2022, the core rate of inflation (which excludes energy prices as well as those for food) has also started to come down.  The rate of change in nominal wages did start to grow in mid-2021, but this appears more to be a consequence of the rising prices rather than a cause of them.  And there has been a slight reduction in the pace of change in wages in recent months.

One does not see in this any evidence that a tight labor market with extremely low unemployment (the lowest in more than a half-century), has led to higher inflation.  The opposite has happened.  Inflation has come down at precisely the time the labor market has been the tightest.

GDP grew rapidly in 2021, but then slowed to a more modest 1.0% rate in 2022 (from fourth quarter to fourth quarter).  Coupled with rapid employment growth in the year, productivity (as measured by GDP per employed person) fell.  However, this appears more to be a continued reaction to changes surrounding the disruptions resulting from the 2020 Covid crisis.  During that crisis, GDP fell but employment fell by much more, leading to a jump in productivity despite the downturn.  As the economy recovered and the situation normalized, workers were hired to bring workforces back to desired levels.  Viewed in a longer timeframe, productivity growth has been similar to what it has now been since the mid-2010s.

That productivity growth is not especially high.  It was 0.8% at an annual rate in the most recent ten-year average.  Coupled with a labor force that grew at 0.8% in 2022, and going forward might grow by even less (it grew at 0.6% a year in the ten-year period ending in 2022), the ceiling on GDP growth would be 1.6% a year, or less.  That is not high, but expectations need to adjust.

That is also a ceiling on what GDP growth might be.  Many expect that there very well could be a recession either later in 2023 or in 2024.  Much will depend on whether the government will be able to respond appropriately if the economy appears to be heading into a downturn.  But with Republicans now in control of the House of Representatives, and threatening to force the US Treasury into default on the nation’s public debt if their demands for drastic spending cuts are not met, one cannot be optimistic that the government will be allowed to respond appropriately.